The Conversation (0)
Dec. 05, 2013 04:30AM PST
2014 could be the year for investors looking for good news in the uranium market.
In the last few weeks, both Dundee Capital Markets’ David Talbot and Raymond James’ David Sadowski have released industry research reports hinting none too subtly at bullish uranium market factors. While revisiting the notion of a bullish market might have some investors rolling their eyes and calling the signs ‘old hat’ — particularly given that 2013 has been less than impressive thus far — the flurry of market activity from acquisitions, financings and supply disruptions indicates that something positive is coming.
For its part, Dundee points to significant pieces of industry news that could act as catalysts for uranium prices moving into the new year. To start with, in September, Cameco (TSX:CCO) delayed the start up of Cigar Lake by six months, while mid-November marked the official end to the HEU agreement as the last shipment of low-enriched uranium (LEU) left Russian shores; furthermore, Russia and Kazakhstan called a halt to future development of uranium projects. With those events on the docket, uranium is looking at a shortage of supply, which is good news when it comes to prices. Over the last few weeks, the uranium spot price has climbed to roughly $36 per pound of U3O8, which has Dundee wondering if we’ve seen the bottom in uranium prices.
Also weighing in on the bullishness of the uranium market, Raymond James wrote that it sees some strength in prices and equities continuing early into the coming year before picking up midway through 2014. The firm cites three catalysts that it sees as driving prices in the coming year: Japanese reactor restarts; utilities emerging from a historic hiatus in contracting to address the growing demand of 2016 and beyond; and the possibility of more mine shutdowns.
Shortage of supply could coax price spike
By 2020, Dundee expects uranium demand to be somewhere between 240 and 260 million pounds of uranium; meanwhile, supply is only slated at 200 million pounds.
One of the driving factors behind the reductions in uranium production is low prices, which have made it difficult for most companies to remain profitable. Raymond James writes that “[u]ntil now, the main supply-side victims of post-Fukushima uranium price weakness have been planned development projects – the likes of Trekkopje, Imouraren and Olympic Dam expansion (we estimate over 80 Mlbs/year in pipeline mine supply has been shelved since mid-2011); but only over the last several weeks have we started to see a meaningful reduction of production guidance from existing mines – the CEO of world top producer Kazatomprom is now guiding for flat growth through to 2015; ARMZ/Uranium One is throttling back growth plans in Russia and effectively halting operations in the US and Australia; and Energy Fuels, the US’ only conventional producer, is placing its White Mesa mill on care and maintenance.”
The unfortunate reality is that if uranium prices continue at under $40 per pound, we could be seeing a lot more mine closures in the future. Raymond James sees the potential casualties being “(i) high cost, low grade operations; (ii) owned by publicly-traded companies; (iii) with high (or ramping) exposure to market prices.”
The flip side of that coin, however, is that the lack of supply will spark another price run.
As far as long-term prices are concerned, Dundee is holding its long-term price at US$65 per pound of U3O8. Raymond James is slightly more positive with a long-term price of US$70 per pound.
Securities Disclosure: I, Vivien Diniz, hold no direct investment interest in any company mentioned in this article.
Featured Energy Investing Stocks
Investor Insight
Generation Uranium offers investors high-leverage exposure to a potential major discovery in Canada’s underexplored and resource-rich Thelon Basin, led by a management team with a proven track record of securing high-value exits.
Overview
Generation Uranium (CSE:GEN, OTCQB:GENR, FRA:W85) is a Canadian exploration company focused on wealth creation through discovery within the uranium sector. The company’s primary strategy is to build a high-caliber exploration team that can rapidly test and drill high-potential targets, de-risking projects for potential takeover by larger producers. Currently centered in the prolific Thelon and Angikuni Basins of Nunavut, the company is also actively evaluating additional project acquisitions in the Athabasca Basin to expand its portfolio.
The company is led by a veteran management team with nearly 30 years of experience in mineral development. CEO Michael Collins has a significant track record of building and exiting public companies, including the co-founding of Bluerock Resources, a conventional uranium producer during the 2000-2008 cycle. This expertise is paired with a focused business model that leverages modern geophysical targeting to accelerate exploration timelines and reduce costs, ensuring the company can deliver results quickly in a bullish uranium market.
Company Highlights
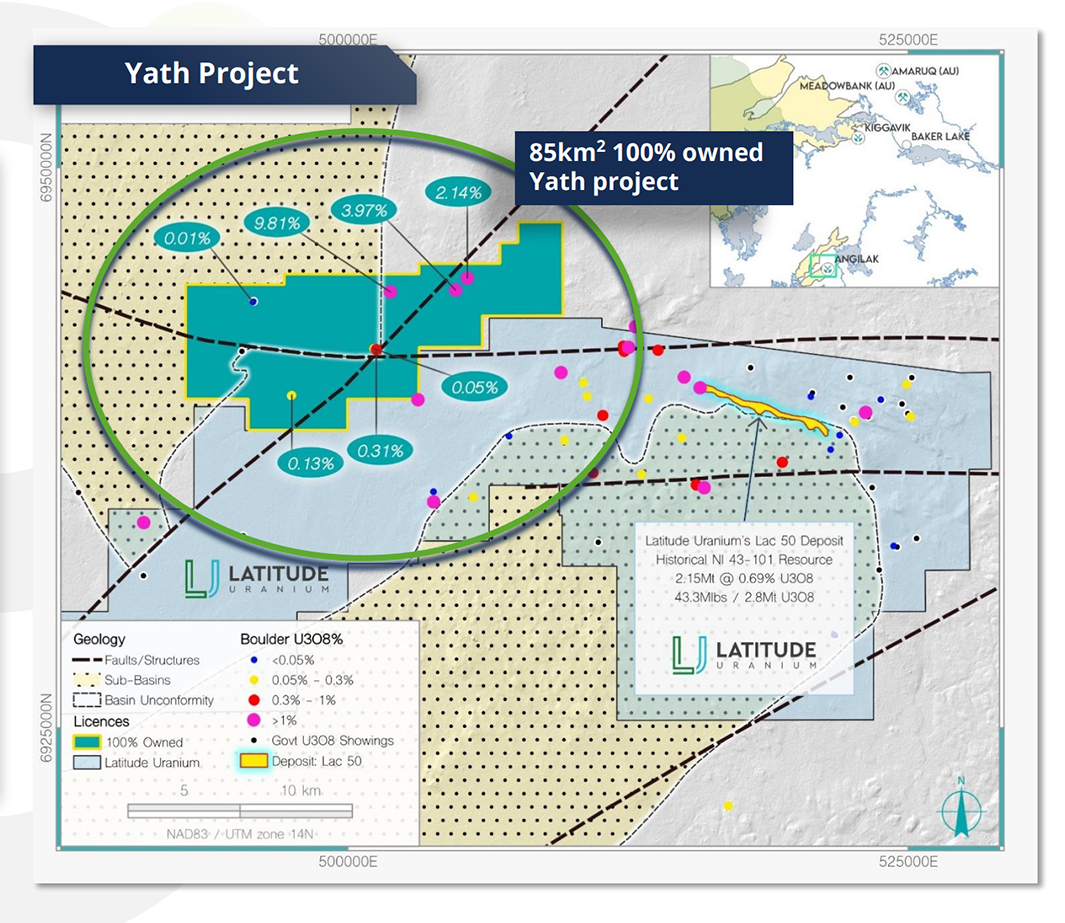
- Strategic Location in a Premier Uranium District: The flagship Yath Project is located in Nunavut’s Thelon Basin, contiguous to ATHA Energy’s Angilak Project, which hosts the high-grade Lac 50 deposit.
- High-Grade Discovery Potential: Historical surface sampling at the Yath Project has yielded exceptional uranium grades, including boulders testing at 9.81 percent, 3.95 percent, and 2.14 percent U3O8.
- Expert Management with Exit Experience: Led by CEO Michael Collins, the team has decades of experience in mineral exploration and a history of co-founding companies that were later acquired, such as Prime Mining and Nuclear Fuels.
- Low-Cost, Rapid Exploration Strategy: By leveraging modern geophysics and extensive historical data, the company aims for a "short road to discovery," de-risking projects quickly to maximize shareholder value.
- Bullish Market Fundamentals: Generation Uranium is well-positioned to meet the growing global demand for carbon-free nuclear power, supported by a projected supply deficit and increased interest from major tech companies seeking clean energy.
Key Project
Yath Project - Nunavut, Canada
The Yath Project is Generation Uranium’s flagship project. This 100 percent owned property covers about 120 square kilometers within the underexplored Thelon Basin in Nunavut, Canada. The project is located where the Yathkyed and Angikuni sub-basins meet, which is a region known globally for high-grade uranium potential. It sits directly along the same trend as the Angilak Project owned by ATHA Energy (TSXV:SASK, OTCQB:SASFK, FWB:XSU.F), which contains the Lac 50 deposit, one of the highest-grade uranium resources found outside of the Athabasca Basin with a historical mineral resource estimate of 43.3M lbs at an average grade of 0.69 percent U3O8.
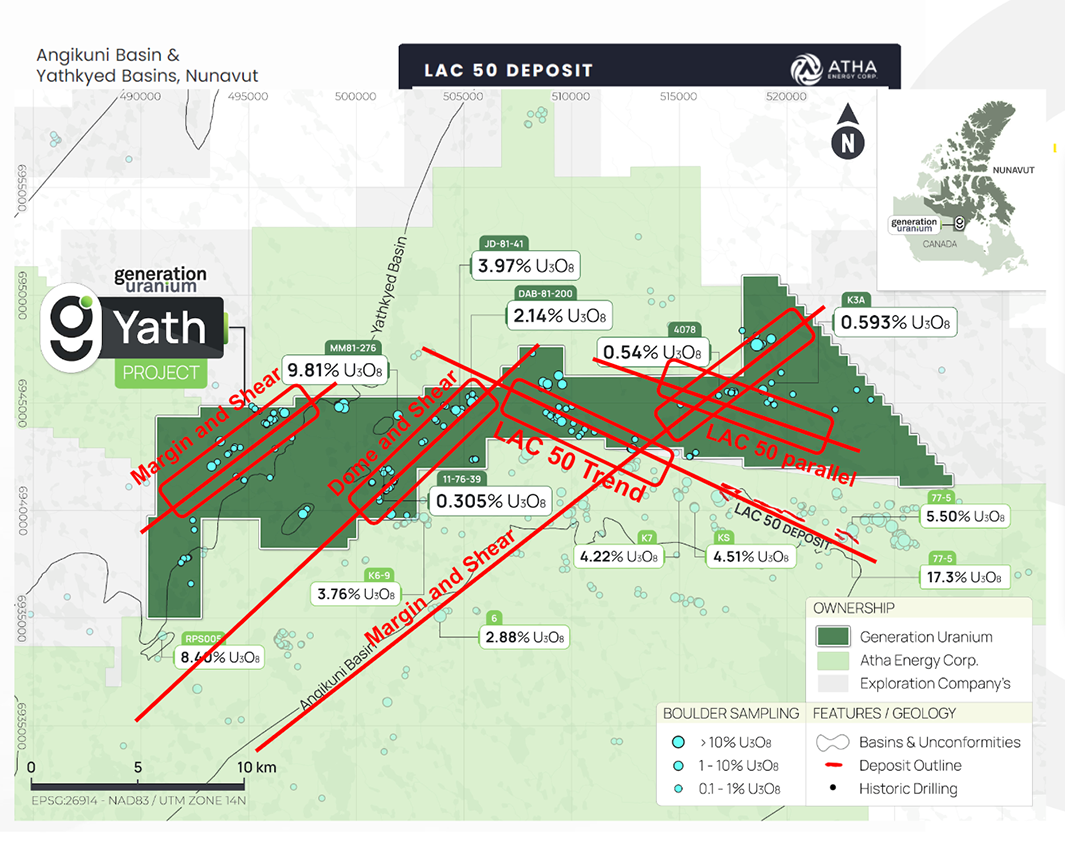
The Yath Project is contiguous to the Lac 50 trend and is crossed by several regional faults and basin boundaries. Past exploration work has already identified high priority targets, while surface sampling in the area has produced uranium grades from boulders, with some testing at 9.81 percent, 3.95 percent, and 2.14 percent U3O8.
The company has commenced its initial field program at the site, set to define and rank drill targets. Historic showings will be combined with new anomalies from the MMT geophysics survey, preparing the project for an anticipated drill permit.
Management Team
Michael Collins - CEO & Director
Michael Collins is a professional geoscientist with nearly 30 years of experience in mineral exploration. He has co-founded several public companies, including Exploits Discovery, Prime Mining (acquired in 2025), and Nuclear Fuels (merged with Premier American Uranium in 2025). He is also currently a director of First Atlantic Nickel.
Christoph Bruening - Director
Christoph Bruening is the founder and managing partner of Value Relations GmbH, a full-service investor relations and public relations agency in Frankfurt with over 25 years of excellence, focusing on mining, exploration, biotech and health care. In addition, he has listed over 600 companies on the Frankfurt Stock Exchange and is a speaker and author of several publications, including on rare earths and uranium.
Dallas Miller - Director
Dallas Miller has been working within the international mining industry for over 15 years, working with BHP and Santos Ltd. He has experience on the ground from an operational standpoint, as well as being an integral part of raising millions of dollars in capital funding for both private and public companies in recent years.
Roger Leschuk - VP Corporate Development
Roger Leschuk has been in corporate management for over two decades, with the past 15 years dedicated to corporate development and investor relations. He has experience participating in and assisting with mergers and acquisitions, and was an investment advisor for various services such as stocks, mutual funds and tax-sheltered investments. He is a Chartered Investment Manager and a Fellow of the Canadian Securities Institute.
Monty Sutton - CFO
Monty Sutton brings over 35 years of experience in public markets and corporate governance. He previously served as CFO for Nuclear Fuels from its IPO through its acquisition.