The Conversation (1)
Oct. 19, 2026 01:55PM PST
Fact CheckedThis article has been reviewed and updated according to INN's rigorous fact-checking process. Our staff editors verify all articles against information and data from primary sources, reputable publishers and experts.
Sebastian / Adobe Stock
Copper prices climbed to record highs in Q3 as the market stayed tight.
Expectations of US tariffs on refined copper drove momentum, drawing metal into Comex warehouses and draining stocks from overseas warehouses controlled by the London Metal Exchange (LME) and the Shanghai Futures Exchange (SHFE). However, movements cooled in September after the White House said it had not made a final decision.
The ongoing conflict between the US and Iran also affected copper prices, driving up producer costs, most notably through supply constraints for sulfuric acid. Likewise, mine supply continued to be impacted by reduced output at the Grasberg and Kamoa-Kakula mines as they recovered from significant shutdowns in 2025.
On the demand side, data centers and the energy transition are adding to base-level growth from urbanization in the Global South and grid upgrades worldwide. Looking ahead, attention is turning to forecasts of a widening supply deficit.
What happened to the copper price in Q3?
Copper prices were volatile at the start of Q3, but largely saw upward momentum, starting at US$6.18 per pound on July 1, and rising over the course of the month to close at US$6.47 on the Comex on July 31.
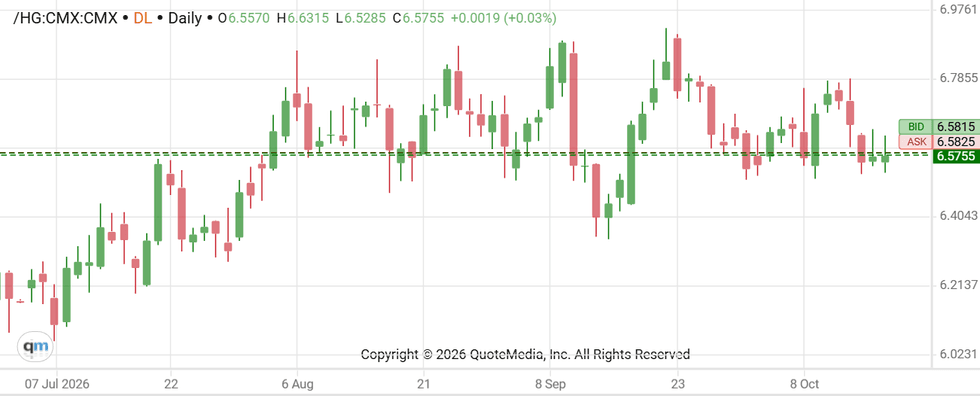
Copper price, July 1 to October 19, 2026.
Chart via the Investing News Network.
High trading volumes pushed prices from US$6.54 on August 3 to US$6.69 on August 31.
Comex copper hit a fresh all-time high on September 9, climbing to US$6.89. While prices retreated as the quarter closed, they remained elevated compared to the rest of the year, closing September 30 at US$6.62.
Prices also rose in London, with the standard three month contract on the LME on an upward trajectory for the quarter, rising from US$13,298.50 per metric ton (MT) on July 1 to US$14,410 on September 30.
Copper prices hit a new LME record on September 9 as well, reaching an intraday high of US$14,858, beating the previous record of US$14,527 set on January 29.
Tariff fears pull copper into US warehouses
US trade policy was the biggest single driver of copper prices in Q3.
When copper tariffs were first implemented in 2025, refined copper was spared, but recommended phased levies were set at 15 percent starting in January 2027 and rising to 30 percent in 2028. US traders have accelerated domestic stockpiling for that reason, with larger quantities of refined product reaching domestic warehouses.
The movements have created a premium, making it more profitable to buy copper on the LME and ship it into the US. This dynamic pushed imports into American warehouses to a record 225,094 MT in July.
By October 13, Comex inventories stood at approximately 787,616 short tons.
Inventories elsewhere fell sharply during the quarter.
LME warehouse inventories sank to 231,275 MT on October 9, down from 324,850 MT on June 30. Likewise, SHFE stocks had fallen more than 80 percent since March, hitting 69,731 MT by mid-August.
In an email to the Investing News Network (INN), SP Angel partner and mining analyst John Meyer explained that despite declines in inventory, demand outside the US remains robust.
“We believe demand in China for copper remains strong. News suggests China is still buying up available physical copper. We feel visible inventories are more representative than they have been for many years with high process attracting metal into LME warehouses from cheaper storage locations,” he commented.
The White House acknowledged that it had received recommendations from the Department of Commerce on June 30 regarding whether tariffs should be implemented on refined copper starting on January 1, 2027.
A decision was widely expected by September; however, Reuters reported on September 10 that no decision had been made; that caused rising copper prices to stabilize through the end of the quarter.
Shanghai Metals Market notes that until the White House rules out refined copper tariffs, copper inventories are likely to remain tied to the US, with room for renewed inflows if the Comex premium widens.
Middle East war drives up producer costs
The Iran war continued to raise input costs for copper producers in Q3, though pressure on sulfuric acid eased late in the quarter. Solvent extraction and electrowinning operations, which account for 22 percent of global mined copper output, rely on sulfuric acid to leach copper from oxide ore, and the Middle East is a key source of the sulfur it requires.
Chile, the world’s top copper producer, has been particularly exposed.
Spot acid prices at the Chilean port of Mejillones doubled to US$380 per MT in April, and China, which supplied 37.1 percent of Chile’s acid imports in 2025, restricted exports in May.
However, there were signs of relief by the end of Q3. China sent its first acid shipment to Chile since May at 32,000 MT, though it covers only a fraction of Chile’s needs, and acid prices have eased since peaking in Q2.
Diesel, the other major cost pressure for open-pit mines, has also been trading near record prices through much of the third quarter. The fuel powers haul trucks and other heavy equipment essential to mine operations.
Earlier in the year, Codelco said higher diesel and supply costs would add roughly 10 cents per pound to its cash costs, an increase of about 5 percent. While President Donald Trump said in October that the US had cut a deal with Russia to provide the market with diesel, analysts suggest the quantities are too small to significantly impact prices.
Copper supply disruptions continue
Copper mine supply stayed constrained in the third quarter. The two major operations that shut down in 2025 are still recovering, and new risks emerged in Chile and the Democratic Republic of Congo (DRC).
At Freeport-McMoRan's (NYSE:FCX) Grasberg mine in Indonesia, mill throughput averaged about 140,000 MT of ore per day in Q3, roughly 67 percent of normal rates before the September 2025 mud rush. Freeport expects to reach 80 percent of capacity in mid-2027 and near full capacity by the end of 2027. Meanwhile, at Ivanhoe Mines' (TSX:IVN,OTCQX:IVPAF) Kamoa-Kakula mine in DRC, copper production ticked up to 76,401 MT in Q3, up from 64,328 MT in Q2. Ivanhoe said 2026 output is trending toward the low end of its 290,000 to 310,000 MT guidance.
It's worth noting that in August, the DRC banned copper concentrate exports to support domestic processing.
However, the impact is expected to be limited, with the biggest effects felt in Zambia, which processes most of the raw copper the DRC exports. The majority of DRC’s copper exports consist of refined copper products, and Kamoa-Kakula’s concentrate is now smelted in the country.
“DRC copper concentrate used to go to Zambia for smelting, and I suspect some still does. Am sure cobalt still leaks out of the DRC,” Meyer said.
Strike threats in Chile
Labor talks broke down at two major Chilean mines in late September.
At Antofagasta's (LSE:ANTO,OTCPL:ANFGF) Centinela, which produced 240,400 MT of copper in 2025, two unions representing 708 workers voted 98.73 percent to strike. Although the workers took to the picket lines on October 7, Antofagasta is maintaining its full-year output forecast.
Days after the Centinela strike vote, 95 percent of participating members for the supervisors' union at BHP's (ASX:BHP,NYSE:BHP,LSE:BHP) Escondida, the world’s largest copper mine, rejected the company’s final contract offer. The vote came after a worker at the mine was killed in a maintenance-related accident on September 23.
BHP requested government mediation, effectively halting any potential worker job action. On October 13, the company and union representatives reached a tentative agreement that included improved benefits and will be presented to union workers for ratification. The deal averts a walkout that could have potentially come that same day.
In an interview with INN on the sidelines of the Precious Metals Summit, McEwen Copper Managing Director Michael Meding said these incidents point to structural deficits in the copper market.
“Some of the most important mines have been hit with unfortunate events, whether that is Grasberg, whether that's Kamoa, whether there that been Cobre Panama,” he said. While he noted that these incidents are only temporary, Meding also raised a more serious issue: declining grades at some of the world’s largest mines.
Meyer echoed that point, suggesting it’s the more serious problem facing copper’s supply side.
“Almost all supply disruptions are temporary. In Chile it was storms, but a fall off in grades is a more permanent issue. In Indonesia, Grasberg is coming back to capacity, albeit slowly. The DRC will always have issues,” he said.
Copper demand builds on growing base
Disruptions and lower output are only half the problem, and come at a time when demand for the red metal is surging.
Even though artificial intelligence (AI) and data centers get most of the attention, they sit atop a much larger demand base for copper. In a January 2026 report titled "Copper in the Age of AI," S&P Global projects that global copper demand will rise from 28 million MT in 2025 to 42 million MT by 2040, driven by four cumulative categories: core economic demand; the energy transition; AI and data centers; and defense.
Core economic demand, which covers construction, machinery, cooling and appliances, is the largest category. S&P expects it to grow from 18 million MT to 23 million MT over that period. While China’s construction sector has slowed over the past five years, urbanization in Southeast Asia and India is offsetting it.
Grid investment is the other core driver. S&P estimates the world will need US$7.5 trillion in transmission and distribution spending through 2040 to replace and expand aging infrastructure.
The energy transition and AI add to an already stressed copper market.
S&P forecasts energy transition demand will rise from 8.5 million MT in 2025 to 15.6 million MT in 2040, while data center demand will more than double, going from 1.1 million MT to 2.5 million MT.
Copper price forecast for 2026
Copper’s record run fed through to equities in Q3. The Nasdaq Sprott Copper Miners Net Total Return Index (INDEXNASDAQ:NSCOPPN) gained 17.11 percent in August, bringing its year-to-date return to 30.51 percent, while the junior copper miners index rose 20.76 percent over the month and 21.9 percent since the start of the year.
The quarter also saw several significant deals, including the announcement of Faraday Copper's (TSX:FDY,OTCQX:CPPKF) planned acquisition of BHP’s San Manuel property in Arizona. The all-share deal would give BHP about 30 percent of Faraday and combine San Manuel with the adjacent Copper Creek project.
The Anglo American (LSE:AAL,OTCQX:AAUKF) and Teck Resources (TSX:TECK.A,TSX:TECK.B,NYSE:TECK) merger is still facing one final hurdle, as Chinese regulators requested firm commitments on copper supply before approval. The merger is targeted to complete between September 2026 and March 2027.
Looking ahead, UBS Group (NYSE:UBS) expects the global copper deficit to widen from 219,000 MT in 2026 to 379,000 MT in 2027, with prices reaching US$15,500 during 2027.
However, not every forecaster sees a deficit. The International Copper Study Group continues to report a surplus of 104,000 MT in 2026, with that amount widening to 368,000 MT in 2027.
For his part, Meyer predicts prices will remain elevated, targeting US$14,750 by the end of 2026 and US$15,000 by the end of the first quarter of next year; however, he also expects volatility along the way.
Catalysts investors should monitor include whether the US decides on refined copper tariffs, which could increase US stockpiling toward the end of 2026. Other issues include labor disputes in Chile, the ramp up of operations at Grasberg and Kamoa Kakula and supply of sulfuric acid from the Middle East.
Don’t forget to follow us @INN_Resource for real-time news updates!
Securities Disclosure: I, Dean Belder, hold no direct investment interest in any company mentioned in this article.
Editorial Disclosure: The Investing News Network does not guarantee the accuracy or thoroughness of the information reported in the interviews it conducts. The opinions expressed in these interviews do not reflect the opinions of the Investing News Network and do not constitute investment advice. All readers are encouraged to perform their own due diligence.
From Your Site Articles
- Copper Price 2025 Year-End Review ›
- What Was the Highest Price for Copper? ›
- When Will Copper Go Up? ›
- Is Now a Good Time to Invest in Copper? Experts Tout Bullish Fundamentals ›
Related Articles Around the Web
https://x.com/INN_Resource
https://www.linkedin.com/in/deanbelder
dbelder@investingnews.com
Featured Copper Investing Stocks

Learn about our editorial policies.