
The Conversation (0)
Featured Precious Metals Investing Stocks
Investor Insight
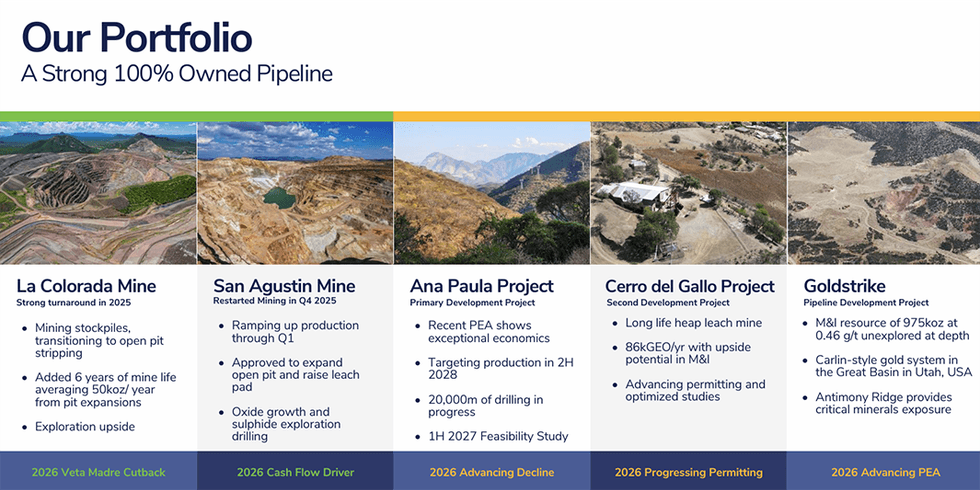
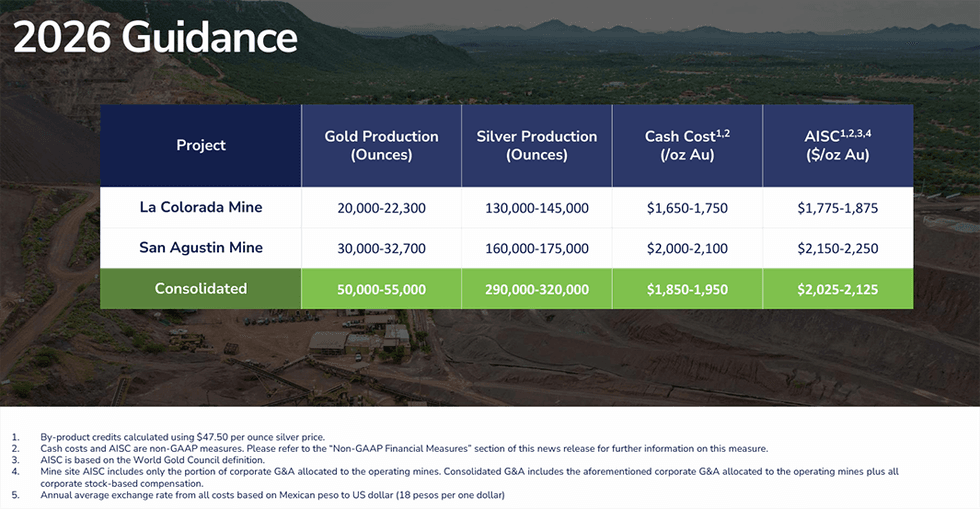
Heliostar combines production of ~50,000–55,000 oz in 2026 with a pipeline of high-margin development assets in Mexico led by Ana Paula. Supported by operating cash flow from La Colorada and San Agustin, a debt-free balance sheet and strategic expansion into the US with the Goldstrike project in Utah, the company is positioned to scale into a 500,000 oz per year gold producer.
Overview
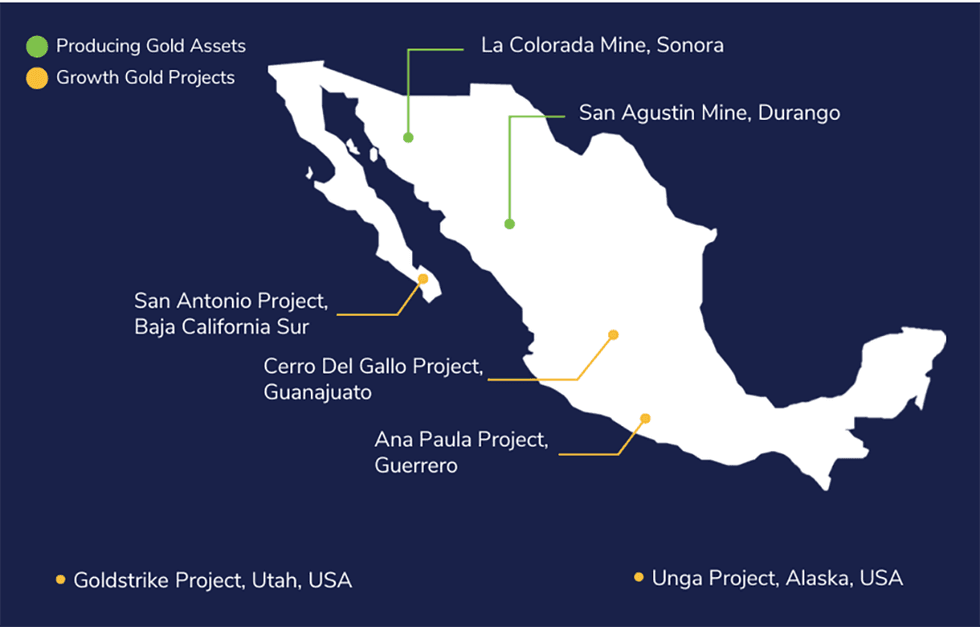
Heliostar Metals (TSX:HSTR,OTCQX:HSTXF,FRA:RGG1) is an emerging gold producer focused on building a mid-tier, multi-asset production platform, anchored in Mexico and complemented by strategic expansion into the United States.
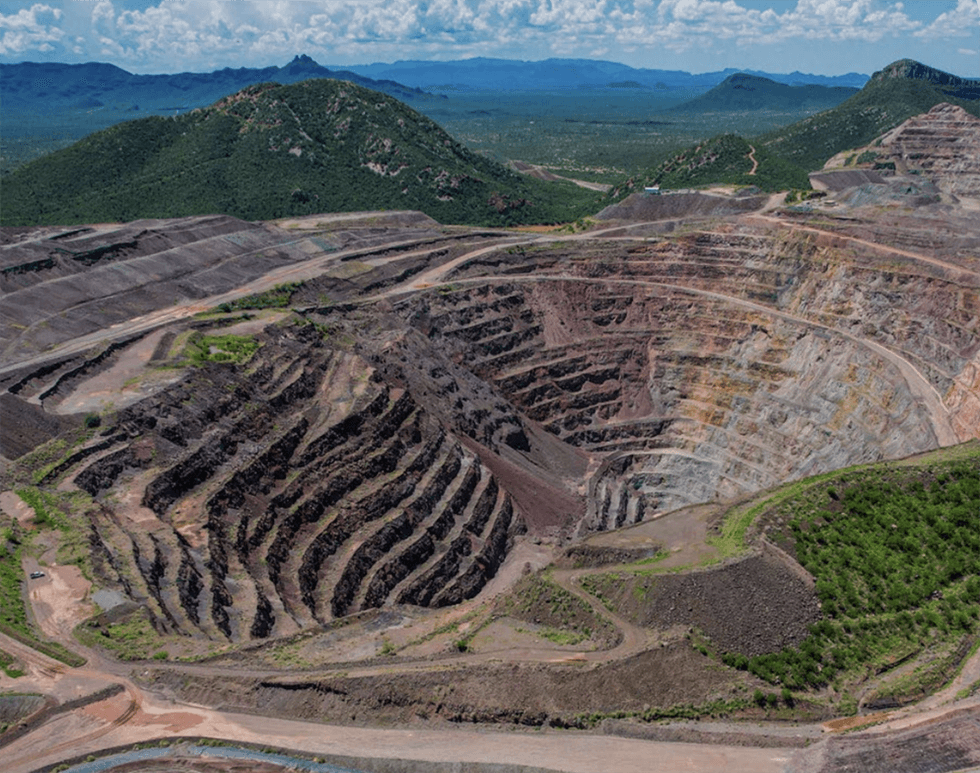
The company has rapidly transformed from an explorer into a producer through disciplined, value-accretive acquisitions, assembling a 100 percent-owned portfolio of producing mines, advanced development projects and exploration assets. This platform provides both immediate cash flow and long-term scalability.
In 2025, Heliostar produced 34,098 gold equivalent ounces, generated US$47.4 million in mine operating earnings, and ended the year with US$40.6 million in cash and no debt, demonstrating strong execution and financial discipline.
Production is expected to increase to 50,000–55,000 oz in 2026, driven by La Colorada and San Agustin. Development of Ana Paula and Cerro del Gallo supports a clear pathway to 500,000 oz annual production by 2030.
In 2026, Heliostar formed part of the OTCQX’s Best 50 top-performing companies. The company ranked 8th overall, joining 7 other mining companies in the top 10.
Beyond its core Mexican portfolio, the addition of the Goldstrike project in Utah introduces further growth optionality, reinforcing Heliostar’s strategy of acquiring and advancing underexplored assets with strong development potential. With a staged growth strategy, strong margins and an expanding resource base, Heliostar is positioned to evolve into a 500,000 oz per year gold producer by 2030.
Company Highlights
- Growing Production Base: Two producing mines targeting 50,000–55,000 oz of gold in 2026, generating cash flow to fund development.
- Clear Path to Mid-Tier Scale: Staged growth targeting annual production of 500,000 oz by 2030.
- High-Margin Flagship Asset: The Ana Paula PEA outlines 101,000 oz/year production (post ramp-up) with strong economics, including US$1,012M NPV5% and 51.3% IRR at higher gold price assumptions, supporting a 2028 production target.
- Self-Funded Growth Model: Generated US$47.4 million in mine operating earnings (2025) with US$40.6 million in cash and zero debt, reducing reliance on equity dilution.
- Robust Resource Base: Approximately 7.3 Moz measured and indicated gold resources plus ~1.4 Moz inferred, supporting long-term scalability.
- High-Quality Development Pipeline: Cerro del Gallo targeting 86,000 GEO/year at US$1,390 AISC, alongside San Antonio’s production potential.
- Strategic Expansion in the US: Acquisition of the Goldstrike project in Utah adds near-surface oxide potential and long-term growth optionality.
- Strong Institutional Backing: Approximately 53 percent institutional ownership, complemented by high-net-worth investors and management alignment.
Key Projects
Ana Paula (Flagship Development Project)
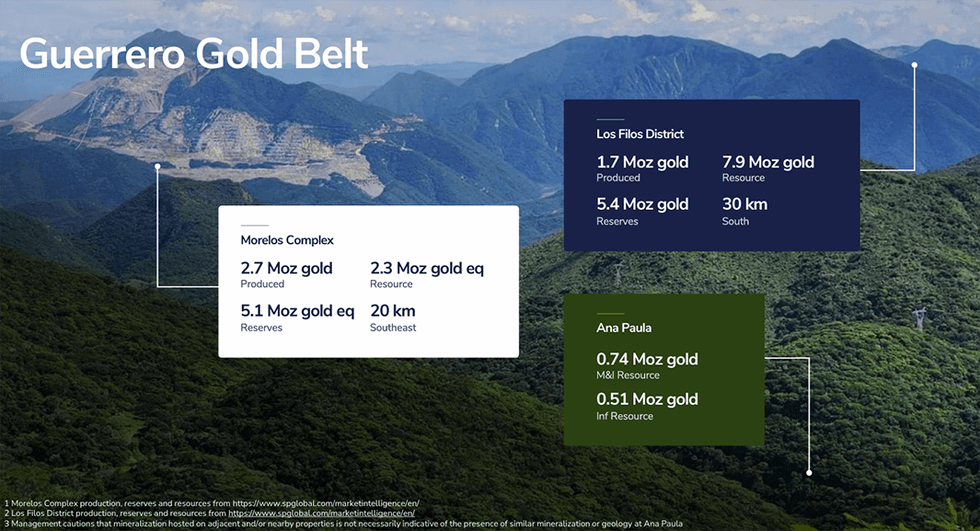
Ana Paula is a high-grade underground gold project in Guerrero and the cornerstone of Heliostar’s long-term growth strategy.
The November 2025 PEA outlines a 9 year mine life with 101,000 oz/year production, 874,700 oz total output, and strong economics, including a US$1,012M NPV5% and a 51.3 percent IRR, supported by a low AISC of US$1,011/oz.
The project hosts approximately 742,000 oz measured and indicated at 5.4 g/t and 514,000 oz inferred, highlighting its high-grade profile and expansion potential.
With a feasibility study targeted for H1 2027 and construction expected in H2 of the same year, Ana Paula is expected to become the primary driver of Heliostar’s transition to mid-tier production.
The company is targeting production at Ana Paula in 2028.
La Colorada Mine
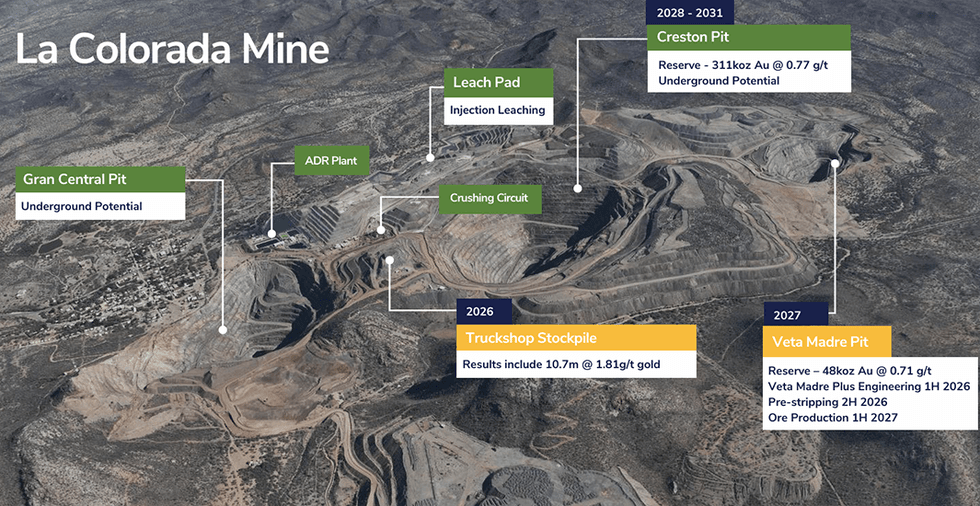
La Colorada in Sonora is a key cash-flowing asset that underwent a successful turnaround in 2025. The mine hosts reserves of 376,000 ounces of gold grading 0.68 g/t in 17.1 million tonnes of ore.
The mine is expected to produce 20,000–22,300 oz in 2026 at AISC of US$1,775–1,875/oz, supported by a six-year mine life and approximately 286,000 oz total production profile.
Mining at the project’s Veta Madre pit commenced in August 2026, a milestone that the company ties to its plan to secure cash flow through 2027 and 2028 to support construction at Ana Paula.
Ongoing drilling, pit expansions and underground potential provide meaningful upside, reinforcing its role as a core funding engine for development.
San Agustin Mine
San Agustin in Durango is a restarted oxide heap-leach operation providing near-term production growth and cash flow.
2026 guidance targets 30,000–32,700 oz of gold at AISC of US$2,150–2,250/oz, following a low-capital restart funded from the company’s balance sheet.
The asset offers additional upside through oxide expansion and sulphide exploration, supporting potential mine life extension.
Cerro del Gallo Project
Cerro del Gallo is a large-scale gold-silver development project in Guanajuato and a key driver of future production growth.
The 2025 PFS outlines ~86,000 GEO/year over a 15-year mine life at US$1,390 AISC, with strong economics, including US$972 million NPV5% and 59.3 percent IRR at higher gold price assumptions.
The project is expected to play a central role in advancing Heliostar towards the goal of 500,000 oz annual production by 2030.
San Antonio Project
San Antonio is a 100%-owned heap-leach development project offering strong optionality and long-life production potential.
The project hosts approximately 1.74 million ounces of measured and indicated gold and demonstrates attractive optionality, including potential 80,000 oz/year production and low AISC of US$1,063/oz.
As permitting advances, San Antonio represents a key medium-term growth opportunity within the portfolio.
Goldstrike Project (Utah, USA)
Goldstrike is a newly acquired gold project that expands Heliostar’s footprint in the United States and adds exploration and development optionality. The property currently hosts an Indicated resource of 975 kilo ounces at 0.46 g/t of gold.
The project hosts a near-surface oxide gold system with historical production of approximately 209,000 ounces of gold and defined mineralization, offering potential for low-cost, open-pit heap-leach development. Its geological setting and existing dataset provide a strong foundation for resource growth and technical advancement.
Goldstrike complements Heliostar’s acquisition strategy by adding a scalable, underexplored asset outside its core Mexican portfolio, enhancing long-term growth potential.
Drilling is underway at Goldstrike to test the antimony and gold potential of both Antimony Ridge and Antimony Knoll, with results expected towards the end of 2026.
Management Team
Charles Funk – President & CEO
Charles Funk has over 20 years of experience in exploration and business development, including senior roles at Newcrest Mining and OZ Minerals. He led the Panuco discovery for Vizsla Silver, demonstrating strong capability in identifying high-value deposits. At Heliostar, he has driven the company’s transformation into a multi-asset gold producer through disciplined acquisitions. His leadership is focused on building a scalable, mid-tier gold platform.
Gregg Bush – Chief Operating Officer (COO)
Gregg Bush is a proven mine builder with extensive experience in mine development, integration and operations. He previously served as COO of Capstone Mining and held senior leadership roles at Equinox Gold. Bush brings deep expertise in optimizing operating assets and advancing projects into production. He plays a key role in executing Heliostar’s production growth strategy.
Sam Anderson – VP Projects
Sam Anderson has approximately 25 years of experience in mine geology and project development, including 17 years at Newmont. He played a key role in advancing the Merian Mine from resource stage through construction to steady-state production. His expertise spans exploration, resource expansion and project execution. At Heliostar, he leads the advancement of key development assets.
Mike Gingles – VP Corporate Development
Mike Gingles brings more than 35 years of experience in the mining industry, specializing in corporate development and M&A. He played a leadership role in major transactions including Pueblo Viejo and Turquoise Ridge. His expertise includes project evaluation, deal structuring and strategic partnerships. He supports Heliostar’s acquisition-driven growth strategy.
Hernan Dorado – VP Sustainability & Special Projects
Hernan Dorado is a fifth-generation miner with over 20 years of experience in mining operations, particularly in Mexico. He was a founding member of Guanajuato Silver, where he served as COO. His expertise includes permitting, community engagement and sustainability practices. He ensures responsible development across Heliostar’s operations.
Vitalina Lyssoun – Chief Financial Officer (CFO)
Vitalina Lyssoun is a Chartered Professional Accountant (CPA, CA) with more than 16 years of experience in financial management within the resource sector. She has extensive expertise in public company reporting, compliance and internal controls. Prior to joining Heliostar, she led the corporate accounting function at Gatos Silver. Her experience spans multiple international jurisdictions.
Stephen Soock – VP Investor Relations & Development
Stephen Soock has nearly 20 years of experience across mining operations and capital markets. He began his career in technical roles at mine sites before transitioning to equity research, where he spent eight years covering growth-stage mining companies. He is a mining engineer and CFA Charterholder. At Heliostar, he leads investor relations and supports capital markets strategy.
Investor Insight
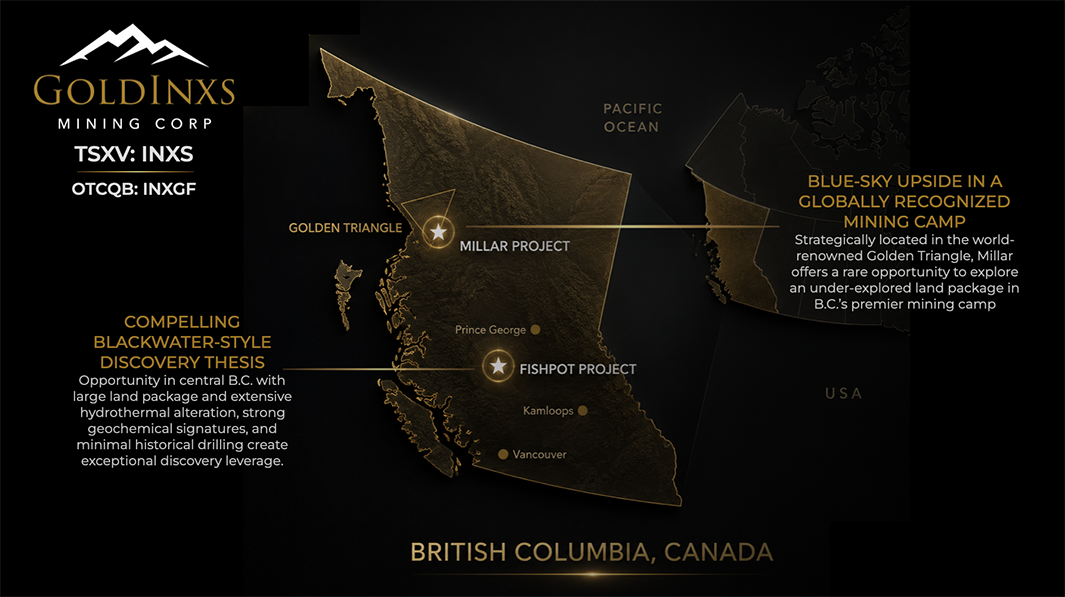
GoldInxs Mining Corp. (TSXV:INXS, OTCQB: INXGF) provides investors with exposure to early-stage gold-copper exploration in British Columbia, leveraging a portfolio of high-potential projects in Tier 1 jurisdictions, within established gold districts, surrounded by strong regional infrastructure and led by an experienced management team committed to accelerating discovery and delivering shareholder value.
Overview
GoldInxs Mining Corp. is a discovery-focused mineral exploration company dedicated to identifying and advancing high-potential copper-gold assets in proven geological belts. The Company's strategy centers on acquiring overlooked and underexplored projects with large-scale potential, applying modern exploration techniques to rapidly evaluate targets and unlock shareholder value through discovery.
The Company’s. common shares started trading on the TSX Venture Exchange in July 2026 under the symbol INXS, positioning itself to capitalize on favorable copper and gold market fundamentals.
Copper demand is forecasted to grow steadily through 2030, with the global copper market expected to expand to over US$340 billion by 2030, driven by electric vehicles, renewable energy and infrastructure growth.
On the other hand, gold continues to provide a safe-haven hedge against policy risks and market volatility, making GoldInxs’ dual focus on copper and gold particularly compelling for investors.
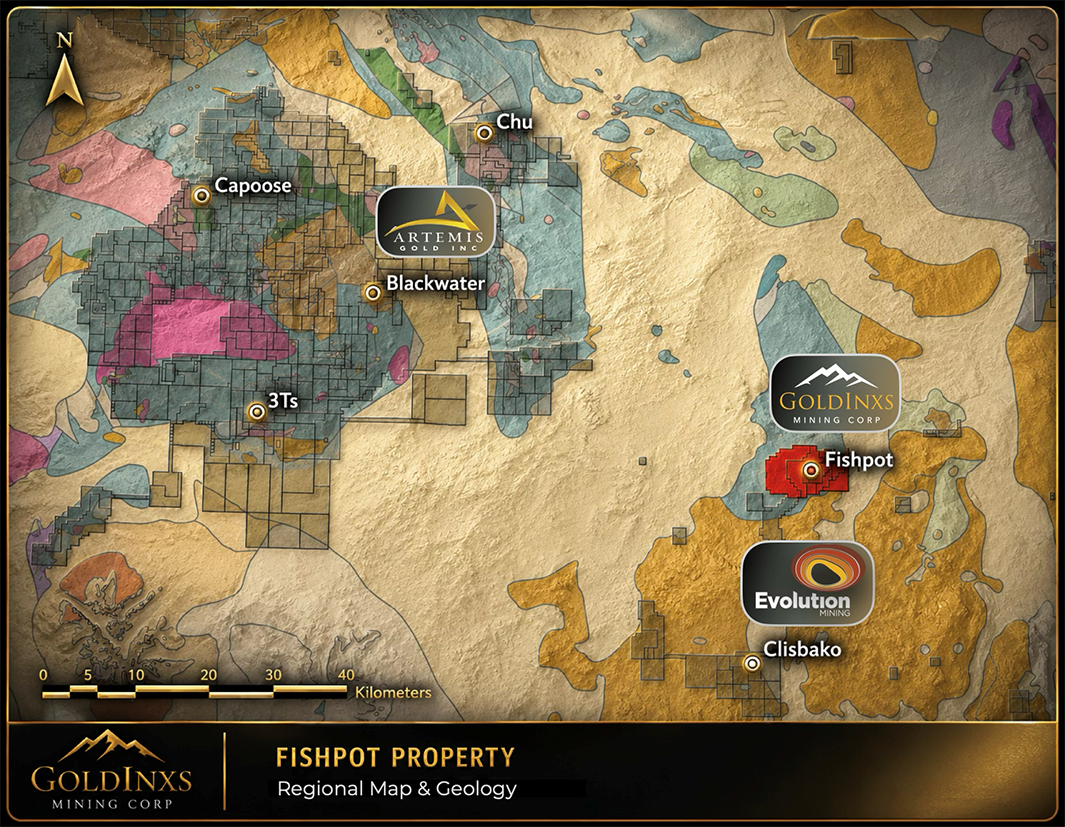
The Company’s portfolio is anchored by two priority projects: the Fishpot Project in central British Columbia, interpreted as an emerging, large epithermal system with strong infrastructure access and jurisdiction quality as well as early indications of blackwater-style mineralization, and the non-core Millar Project in the prolific B.C Golden Triangle, a district renowned for world-class discoveries. While surrounding deposits attracted billions of dollars in investment, Fishpot received only sporadic historical exploration despite widespread hydrothermal alteration and numerous anomalous gold, silver and copper results. Artemis Gold’s Blackwater Mine has announced tripling production with an intended $1.56B investment, which sits only 65 km from the Fishpot property.
Backed by a management team with expertise in exploration, project development and capital markets, GoldInxs is positioned to rapidly advance its assets, deliver near-term exploration catalysts and create shareholder value through discovery and strategic growth.
Company Highlights
- Mining-friendly jurisdiction: Projects are in British Columbia, which ranked second in Canada and 20th globally in the 2025 Fraser Institute investment attractiveness rankings.
- Flagship and district-scale assets: Portfolio is anchored by the flagship Fishpot Project (“Fishpot”) in central B.C., showing strong geological indicators of mineralization, blackwater-style mineralization potential and immense exploration upside potential with only 378 meters of historical drilling. Fishpot is strategically located in the same region as Artemis Gold’s Blackwater Mine and Evolution Mining’s optioned Clisbako property.
- Clear path to 2026 catalysts: GoldInxs secured a drill permit for an upcoming maiden 2,000-metre drill program at Fishpot, near-term exploration programs are designed to define mineralized systems, outline blackwater-style potential and create shareholder value following the completion of a 3D IP survey and drill targeting.
Key Projects
Fishpot Project
The Fishpot Project represents the cornerstone asset within the GoldInxs portfolio. Covering up to 5,500 hectares in Central British Columbia, and located ~95 km north of Quesnel, Fishpot hosts a large hydrothermal alteration system that exhibits many of the geological characteristics observed in major epithermal and intrusion-related gold systems throughout the region. Fishpot encompasses five claim blocks, held under an option to acquire 100 percent subject to a 2 percent NSR, representing a significant exploration opportunity in a highly prospective region.
Fishpot represents a largely untested hydrothermal mineral system where multiple independent exploration datasets, including gold-silver-copper surface geochemistry, alteration and geology, airborne magnetics, 3D IP chargeability/resistivity and identified epithermal-to-potential-porphyry target environments, are converging to define drill targets, despite only 378 metres of historical drilling across two holes.
Fishpot is situated within the highly prospective Stikine Terrane and is underlain by Hazelton Group volcanic rocks and intrusive units comparable to those associated with several significant deposits in British Columbia. Extensive quartz-sericite alteration, hydrothermal brecciation, pyrite mineralization and multi-element geochemical anomalies support the interpretation of a robust mineralizing system. Fishpot is strategically positioned near active and historical mining operations, including Artemis Gold’s Blackwater Deposit, Newton Gold Project, Capoose and 3Ts Project, underscoring its large-scale discovery potential. Importantly, based on early-exploration results, Fishpot shares several regional geological characteristics commonly associated with Blackwater-style gold systems, including felsic volcanics, strong alteration, pyrite-rich mineralization and gold-silver geochemical associations. Despite the similarities the Company cannot yet make any formal connections to the surrounding properties, nor can they guarantee that such deposits exist on their ground.
Fishpot Exploration Technology: GoldInxs advanced its Fishpot targeting program by combining a conventional 3D IP survey with emerging Virtual DRILL™ remote-sensing technology as an additional targeting layer, using multiple geological, geochemical and geophysical datasets to refine and prioritize targets ahead of a planned ~2,000-metre drill program.
Fishpot Drill Permit & Expansion: GoldInxs has received the required drilling permits and expanded Fishpot to 5,509 hectares, positioning the Company to proceed with its inaugural ~2,000-metre modern drill program on a property that has seen very limited historical drilling, while refining targets through integrated geological, geochemical and geophysical data.
Despite multiple encouraging exploration indicators, Fishpot has been subjected to only two historic drill holes totaling 378 metres, leaving the broader mineral system largely untested and providing significant leverage to future exploration success.
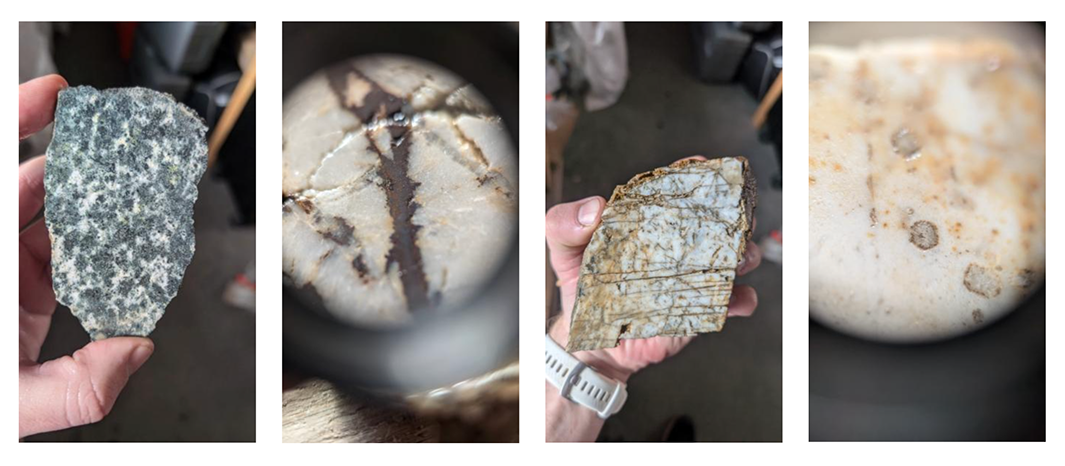
Recent exploration completed by GoldInxs generated the highest reported gold value on Fishpot to date, returning up to 5.65 g/t Au from surface sampling, while airborne geophysical surveys identified multiple coincident magnetic and geochemical anomalies that have strengthened the Company's exploration model and target pipeline.
The 2025 program returned rock samples of up to 5.65 g/t Au, 11.35 g/t Ag and 0.42% Cu, while historical work reportedly returned up to 4.36 g/t Au and 3.2% Cu.
The property exhibits the potential low-sulphidation epithermal targets at Fishpot North, intermediate-sulphidation signatures at Fishpot East, and a large central magnetic high being evaluated for potential porphyry mineralization at depth. The Company is focused on finalizing drill targeting and preparing for the inaugural diamond drill campaign at Fishpot in the coming months following completion of the IP survey. GoldInxs is preparing to drill-test a 5,509-hectare, largely undrilled hydrothermal system in central British Columbia where high-grade surface gold-silver-copper results, Blackwater-style geological characteristics and multiple coincident geophysical targets have converged to define a portfolio of high-priority exploration targets.
Management Team
Nick Michael – President and CEO
Mr. Michael is a veteran mining executive and technical director with over 37 years of global experience spanning mine development, engineering and operational leadership. His expertise covers the full project lifecycle, including design, construction, technical due diligence and Independent Engineer assignments for institutional investors and project financiers. He also leads CJK Milling, a company focused on reprocessing historical mine waste to recover discarded gold decades ago, when it was less valuable.
Carlo Rigillo, CPA, Chief Financial Officer
Mr. Rigillo is an experienced Chartered Professional Accountant with over two decades of experience. He holds a Bachelor of Commerce from the University of Toronto.
Barry Miller – Executive Chairman and Director
Mr. Miller brings over 30 years of experience in public markets, including roles as a broker, consultant and financier. He is the founder of GoldInxs and has been actively involved in the resource sector through leadership positions, including as director of Tinova Resources Corp., an exploration company focused on tin and rare earth elements in British Columbia and Alaska.
Tara Asfour - Vice President, Corporate Development and Communications
An executive consultant with over 13 years of experience, Tara Asfour holds expertise in corporate development, capital markets, investor relations and strategic communications. She has led strategic financings, partnerships and offtake initiatives within the resource sector through previous corporate development and investor relations roles with multiple publicly listed companies.
Al Fabbro – Director
With over three decades of experience spanning both the mining and finance sectors, Mr. Fabbro previously led Yorkton Securities’ retail trading department and was part of its Natural Resources Group. He later served as Lead Director of Roxgold Inc. and currently holds executive leadership roles in the mining industry.
Darcy Vis, P.Geo. – VP Exploration and Director
Mr. Vis is an economic geologist with over 17 years of experience in mineral exploration. He has held senior technical roles across multiple exploration companies and is the President of Tripoint Geological Services Ltd. His expertise includes target generation, project evaluation and exploration program execution.
Stephen Soock, P.Eng., CFA – Director
Mr. Soock is a mining professional with nearly 20 years of experience spanning both technical operations and capital markets. He currently serves as Vice President, Investor Relations and Development at Heliostar Metals.
Christopher Kelly, PQS, FCIArb – Director
Mr. Kelly has over 15 years of experience in construction and natural resources. He holds a BSc in Construction Economics and Management and an MSc in Construction Law and Dispute Resolution, and runs Trachtala Consulting Ltd.