• Connect with us
    • Information
      • About Us
      • Contact Us
      • Careers
      • Partnerships
      • Advertise With Us
      • Authors
      • Browse Topics
      • Events
      • Disclaimer
      • Privacy Policy
    • Australia
      North America
      World
    Login
    Investing News NetworkYour trusted source for investing success
    • North America
      Australia
      World
    • My INN
    Videos
    Companies
    Press Releases
    Private Placements
    SUBSCRIBE
    • Reports & Guides
      • Market Outlook Reports
      • Investing Guides
    • Button
    Resource
    • Precious Metals
    • Battery Metals
    • Base Metals
    • Energy
    • Critical Minerals
    Tech
    Life Science
    Precious Metals Market
    Precious Metals News
    Precious Metals Stocks
    • Precious Metals Market
    • Precious Metals News
    • Precious Metals Stocks
    gold investing

    Jeb Handwerger: Position Yourself for Fall Fireworks

    Written by Investing News Network
    |
    Aug. 11, 2014 03:00PM PST

    Investors are all too familiar with the KABOOM in precious metals prices in the fall of 2011 and the echo that’s still reverberating. Three years later Jeb Handwerger, founder of GoldStockTrades.com, believes it could be the broad market’s turn—and soon. In this interview with The Gold Report, Handwerger explains why it’s important to position yourself for some fall fireworks and suggests some stocks with booming fundamentals.

    Source: Brian Sylvester of The Gold Report (8/11/14)

    Investors are all too familiar with the KABOOM in precious metals prices in the fall of 2011 and the echo that’s still reverberating. Three years later Jeb Handwerger, founder of GoldStockTrades.com, believes it could be the broad market’s turn—and soon. In this interview with The Gold Report, Handwerger explains why it’s important to position yourself for some fall fireworks and suggests some stocks with booming fundamentals.

    The Gold Report: On June 11, on GoldStockTrades.com you wrote, “Some of my charts are showing a potential reversal in the precious metals.” What are those charts telling you in late July?

    Jeb Handwerger: In early June it appeared that the junior miners—tracked by the Market Vectors Junior Gold Miners ETF (GDXJ), which I use as a proxy for the junior gold miners—was making an inverse head-and-shoulders pattern between $34 and $35. Then the junior miners had a very strong rally in June, with an intraday high of $46. Now we’re forming what I believe is a potential crossing of the 50-day and the 200-day moving averages—a golden cross. This could signal the final turn from a secular bear market to the beginning of an uptrend.

    TGR: Is gold close to a golden cross?

    JH: Yes, it did in early July and I believe it will hold. Gold is now trading below both the three-year and five-year moving average. That’s very rare. The last time we saw the gold price move below the long-term moving averages was in the 1999–2001 bear market. If you can get gold at a discount, then it’s a great opportunity. The greatest opportunity may be the Philadelphia Gold and Silver Index (XAU), an index of 16 gold miners.

    The miners are usually closely correlated to gold, but are much more volatile. For instance, in the 2008–2009 correction we saw the Philadelphia Gold and Silver Index decline from 200 to below 80—more than a 50% decline—even though gold only corrected from $1,000 per ounce ($1,000/oz) to $700/oz.

    Now we’re seeing higher lows in the $1,200/oz range and the Philadelphia Gold and Silver Index is trading around $100. If gold moves up even $50 or $100/oz, the miners and the index could have much larger percentage gains, so the leverage opportunity is really in the miners. The miners outperformed gold by a wide margin from 2000–2008.

    TGR: Should investors buy the ETF or the miners?

    JH: If you’re able to beat the Market Vectors Gold Miners ETF (GDX) and the Market Vectors Junior Gold Miners ETF, then buy them directly. I try to find companies that outperform the large producers and their junior peers. If you find companies that are leading both in fundamentals and technical data, you have a good chance of beating the indexes.

    TGR: What ranges do you expect gold and silver to trade in at the end of 2014?

    JH: The three-year trailing moving average is around $1,510/oz; the five-year is about $1,415/oz. That is where gold should be trading. Throughout the 2002–2011 rally gold was trading at a huge premium to the three-year and five-year trailing moving average. Now it’s trading at a discount.

    TGR: What about silver?

    JH: The long-term charts for silver and the Philadelphia Gold and Silver Index are closely correlated and leading indicators to gold; silver and the miners will usually top a few months ahead. They were also the strongest gainers after the 2008 crash. Silver has pulled back to that crucial $20/oz range—a major breakout point in 2011 when quantitative easing was announced and silver ran close to $50/oz. Now that it has pulled back to that breakout point again, silver should provide leverage and outside gains to gold.

    I also like platinum group metals. In 2012, I became bullish on platinum and palladium because both were trading at a discount to gold. Palladium is now breaking out on concerns about supply from South Africa and Russia, while industrial and investment demands are increasing. There are few platinum group metal major assets. Investors should check out the juniors with advanced platinum group metals resources in North America.

    TGR: In the same June 11 commentary you posited that institutional buyers were returning to junior mining equities. What are some signs that you’re correct?

    JH: One sign is a huge uptick in volume in the Market Vectors Junior Gold Miners ETF. The volume increase in the first seven months of 2014 has been exceptional, whereas volume is decreasing in a rising market in the SPDR S&P 500 ETF (SPY:NYSE), an ETF tracking the S&P 500. The rising volume in the juniors may indicate accumulation, whereas decreasing volume in a rising market may indicate that the rally in the S&P 500 is overbought and running out of steam. The equity market has not had a significant correction in more than three years and it’s dangerous territory for a correction.

    To be clear, by institutional buyers, I meant value investors. Value investors are buying junior mining companies at book value per share (Note: cash on the balance sheet/share float) that is double or triple the market caps. There are other companies that have spent millions on their projects, yet the market cap is only a fraction of what they have spent. I’ve spoken to fund managers that I haven’t spoken to in years, people who have made money in previous cycles and have been out of the market. Those people are finally dipping their toes back into the junior sector.

    TGR: Are you expecting a broad market correction in the near term?

    JH: Yes. That’s why I’m expecting inflation to pick up and that’s going to make things difficult for some of the overvalued equities. I see a big rotation from the overbought large-cap equities into the small-cap base and precious metals junior miners and energy plays. I expect the fall to be quite busy. After Labor Day we’re going to see some fireworks.

    TGR: On June 25 you wrote, “Investors need to pick carefully in the junior mining space and research the asset, share structure, balance sheet, jurisdiction, growth profile and investigate to see if management is ethical.” Let’s examine those criteria more closely, beginning with assets.

    JH: If you think gold is going to be flat, you have to ask: Will this company survive at the current gold price? If it’s a high-cost mine, it’s going to have more challenges, yet a low-cost or higher-grade mine can usually withstand difficult times.

    Good financial backing is also crucial. Most of the companies I follow are oversubscribed when a financing is offered. I stay away from companies that are desperate for money.

    Share structure: I like a company that doesn’t have too many shares outstanding. The ownership mix would preferably be a good institution that’s a long-term investor with around 19.9% ownership. I like finding companies with a significant position held by a major producer or a well-respected fund because they have done a lot of the homework for you. Those companies have strong geological and technical research teams.

    Balance Sheet: Cash that equals something close to 20 times the active burn rate.

    Jurisdiction: There’s a lot of geopolitical risk in today’s world. Stable jurisdictions are at a premium. Some of the majors have had to take huge write-downs in places like Argentina and Chile, whereas investment interest is growing in places like Nevada. Nevada has by far the most economic gold mines.

    If it weren’t for Nevada, major producers like Barrick Gold Corp. (ABX:TSX; ABX:NYSE) and Newmont Mining Corp. (NEM:NYSE) would be in serious trouble. Barrick’s most profitable mines are in Nevada’s Cortez and Carlin trends. In Canada, there’s a lot of merger and acquisition activity in Ontario. Québec recently elected a government that’s pro-mining. There are pockets of opportunity in Africa but you have to look at specific areas. And some of these jurisdictions are changing, such as in Colombia where three or four juniors have been bought by majors over the past few years.

    I recently returned from a site visit to Red Eagle Mining Corp.’s (RD:TSX.V) Santa Rosa project. The market cap is $20 million ($20M) and the company is 18 months from production. There are exceptional opportunities right now.

    Management: How do you know if management is ethical? You look at the salary and ask questions. Does the company have higher general and administrative expenses than its peers? Does management own shares? Did management partake in the last round of financing? I tend to shy away from any companies where management is selling stock. I like to see management ideally own 15–20%. One red flag is when we see a CEO with only a few shares and the rest in options. Track record is important, too. Has management done this before? All these things are publicly disclosed and you can find them with the click of a button.

    TGR: You talked about Nevada. What are some companies you’re following there?

    JH: Canamex Resources Corp. (CSQ:TSX.V; CX6:FSE) is one. It has two major shareholders, Hecla Mining Co. (HL:NYSE) and Gold Resource Corp. (GORO:NYSE.MKT; GORO:OTCBB; GIH:FSE). Canamex has hit some phenomenal near-surface results at its Bruner project—one intercept hit 44.2 meters grading 6.97 grams per tonne (6.97 g/t) gold.

    TGR: Canamex has two major shareholders in Gold Resource and Hecla, but it doesn’t seem to get a lot of attention. Why aren’t more people following that story?

    JH: Now people are becoming more aware. I started covering and buying the stock in December 2013 at around $0.06/share. That was one-third of what Hecla paid for it. Now it’s trading around $0.18/share, so that’s a triple for my subscribers. Then Gold Resource took a position and this summer Canamex has been hitting incredible drill results at Bruner—near-surface, high-grade material that’s amenable to heap leaching. I think it’s just the beginning. Canamex is going to publish soon a maiden resource. I believe that this is a takeout target because it’s an asset that would probably have low capital costs and a quick payback. We’re probably going to see Hecla or Gold Resource make an offer or finance another round.

    TGR: You recently visited several gold projects in Nevada. Tell us about some.

    JH: I recently visited NuLegacy Gold Corporation (NUG:TSX.V; NULGF:OTCPK). The company is sitting next to Barrick’s Goldrush deposit, probably one of the best discoveries in the world at 15.6 million ounces (15.6 Moz) gold in all categories. The company partnered with Barrick, which is rare in the junior sector and only happened because of NuLegacy’s management’s team. COO Roger Steininger was one of the people who discovered the Pipeline gold deposit in Nevada’s Cortez Trend for Royal Gold Inc. (RGL:TSX; RGLD:NASDAQ); the project has since been purchased by Barrick. NuLegacy is beginning to outline a deposit in an area of Nevada where there are potential elephants. I’m excited to see the results of its exploration program, especially the Avocado Anomaly, throughout the summer and fall.

    Gold Standard Ventures Corp. (GSV:TSX.V; GSV:NYSE) is on my watchlist as it has made multiple discoveries in Nevada’s historic and famous Carlin Trend, which is home to a bunch of majors such as Newmont and Barrick. Gold Standard just consolidated the Pinion asset, which may have nearer-term production capabilities. The company is planning to release an NI 43-101 resource estimate in the near term, which will give me a better sense of the asset. The geological team has several additional targets that they will follow up on after the publication of the resource.

    TGR: Perhaps one or two more in Nevada?

    JH: I also like Corvus Gold Inc. (KOR:TSX), which is exploring the North Bullfrog project in Nevada. I’ve been following Corvus Gold since it was spun out from International Tower Hill Mines Ltd. (ITH:TSX; THM:NYSE.MKT) almost three years ago. It went over $2/share in a difficult market and has since pulled back. The company continues to make high-grade discoveries at the Yellowjacket deposit, part of North Bullfrog. Corvus’ technical team is very strong. CEO Jeff Pontius has made other million-ounce discoveries, including the Livengood gold deposit in Alaska. In Nevada, it looks as if Corvus is just beginning to scratch the surface of a major gold discovery.

    Another one in Nevada that is quite exciting is Comstock Mining Inc. (LODE:NYSE.MKT). The company is increasing production and lowering costs in the historic Comstock district. This year Comstock is putting some of that capital into drilling an area with some of the best exploration potential in Nevada.

    TGR: Comstock’s ultimate goal is to produce 200,000 ounces per year (200 Koz/year) via heap leaching. Is that realistic?

    JH: It started off at 10 Koz/year; now it’s targeting 40 Koz/year. Comstock could likely make it to 100 Koz/year by 2016–2017. In the meantime, the company could make another discovery. Some drill results in the Chute Zone look promising. It could be onto something there.

    TGR: What else do you own?

    JH: I took a large position in Red Eagle Mining in Colombia. I recently returned from a trip to Medellín to visit the Santa Rosa project with analysts from major financial institutions. I like the project for a few reasons. In my opinion it could be the first permitted major gold producer in Colombia. Red Eagle is only a few weeks away from publishing a bankable feasibility study on Santa Rosa, which should reach production in the next 18 months. It’s a very large project—it could be a district, it’s already 320 square kilometers. An earlier preliminary economic assessment (PEA) showed production of around 50 Koz/year with cash costs around $620/oz. This means the mine could cash flow close to $60M even if gold stays around $1,300/oz. The PEA showed a payback period of 1.4 years, which is impressive. The bankable feasibility study should be published by the end of September.

    TGR: Why is the share price not performing?

    JH: Some people are concerned about the mining license. I was there and saw the community support, especially from La Universidad de Antioquia, the local university. It assisted the company with the development of the environmental impact studies. And COO Robert Bell has helped build 10 to 12 mines. It’s going to have an exciting second half if Red Eagle gets the necessary financing and a mining license. It has a strong shareholder in Liberty Metals & Mining Holdings LLC, which owns about 20%. Management owns around 12%.

    TGR: Red Eagle recently bought the San Ramon extension from AngloGold Ashanti Ltd. (AU:NYSE; ANG:JSE; AGG:ASX; AGD:LSE). What does that mean for shareholders?

    JH: It’s a strategic piece of land on the exploration package. Some valuable opportunities could be there. One of the knocks on Red Eagle is that it doesn’t have a huge resource, but the goal is to get into production. Once it is in production and generating cash flow, there will be further exploration to build reserves and resources. I believe there is a lot more gold there than most investors realize.

    TGR: What are some other equities that you’re telling your readers about?

    JH: One of our favorite companies, Integra Gold Corp. (ICG:TSX.V; ICGQF:OTCQX), recently closed a private placement that was oversubscribed due to major demand from investors. There’s so much interest in Lamaque because it is one of the highest-grade undeveloped gold projects in Québec with over 3.3 million tons at over 7 g/t gold. An updated resource incorporating the latest drill results should be out soon.

    TGR: Integra’s PEA showed an internal rate of return of 38% with a payback period of 1.8 years. Why didn’t the market respond more favorably?

    JH: The market wants to see all the pending assays from the 57,000m of drilling that has yet to be added to the previous resource. An updated resource with all this exciting drilling data will make the majors take notice.

    TGR: Could that lead to a takeover bid?

    JH: Integra could be a classic takeover target. Osisko Mining Corp., which had the nearby 10 Moz Malartic gold project, was bought by Yamana Gold Inc. (YRI:TSX; AUY:NYSE; YAU:LSE) and Agnico-Eagle Mines Ltd. (AEM:TSX; AEM:NYSE). Integra’s Lamaque project sits right next to Agnico-Eagle’s 1.6 Moz Goldex mine in an area with great infrastructure and skilled labor.

    TGR: Perhaps one or two others before we leave the gold space?

    JH: Another one that investors may want to look into is Barisan Gold Corp. (BG:TSX.V). The company hit 412m of 1.1% copper equivalent in a gold-copper porphyry at its Upper Tengkereng discovery. It’s in Indonesia, which just elected a more business-friendly prime minister. Barisan is publishing some of the best drill results that I’ve recently seen in the junior mining space.

    TGR: Any others?

    JH: It’s not in Nevada, but keep a close eye on International Tower Hill Mines. It has one of the largest resources in the junior gold space in Alaska. If we’re hitting the bottom, we want situations that are going to provide a lot of leverage to a rising gold price. Tocqueville Asset Management has been buying International Tower Hill shares throughout 2014. Some of the smart money may be looking at a bottom here.

    I love Alaska even though it is currently out of favor. It is stable and secure in a chaotic world. NOVAGOLD (NG:TSX; NG:NYSE.MKT) is on our watchlist as it owns the Donlin project, where it is partnered with Barrick. It has around 45 Moz gold in the Resource category. Donlin could possibly produce over a million ounces of gold annually at a high grade of 2.2 g/t. It can be purchased at a major discount. NOVAGOLD is currently trading under $4/share. In previous gold bull markets, the company was trading in the mid-teens. As the sector turns, I wouldn’t be surprised if it makes that move again.

    TGR: Would you tell us about some action that the Alaskan government recently took?

    JH: The Alaskan government is approving up to $145M in financing support for Ucore Rare Metals Inc.’s (UCU:TSX.V; UURAF:OTCQX) Bokan project near Ketchikan. The rare earth sector is beginning to wake up from a multiyear slumber. Investors are returning as more people realize that these metals are critical for automobiles, batteries, smart phones, wind turbines and military equipment. It’s a $4 billion industry and China controls it, especially the heavy rare earths. The Market Vectors Rare Earth/Strategic Metals ETF (REMX) is breaking above the 200-day moving average and I’ve been alerting readers to a potential bottom.

    One of the best potential projects in the West is Ucore Rare Metals’ Bokan deposit, which has incredible financial and permitting support from the State of Alaska. It also has a great partner in the U.S. Department of Defense. There are plenty of rare earth projects, but very few are making authentic progress. Ucore is doing that technically and financially, and Ucore is moving closer to a bankable feasibility study. Pull up a chart of Ucore versus Molycorp Inc. (MCP:NYSE) and you will see the outperformance. I think that’s just the beginning.

    TGR: The PEA for the Bokan Mountain Rare Earth Element project pegs capital costs at $221M. It has loans for up to $145M but that still leaves Ucore $76M short. Where’s that capital going to come from?

    JH: That’s a good question. All the rare earth equities have to face these questions but only Ucore has up to a $145M loan guarantee from the State of Alaska. Ucore has a good shot and other financiers may be more confident to lend to Alaska as they see the strong lead backing by the State of Alaska.

    TGR: Please give our readers one final thought to ponder.

    JH: We’re in a period known as the summer doldrums, yet we’re seeing a lot of activity in precious metals. There is geopolitical instability both in Eastern Europe and the Middle East. The potential for black swan events is increasing and that is the fuel that lights up the gold sector. We could still see another pullback but post-Labor Day should bring a powerful seasonality effect. Now may be the time to position in August for what I believe is going to be an exciting fall season for precious metals and the junior resource sector.

    TGR: Thank you for talking with us, Jeb.

    Jeb Handwerger is an author, speaker and founder of GoldStockTrades.com. He studied engineering and mathematics at University of Buffalo and earned a master’s degree at Nova Southeastern University. After teaching technical analysis to professionals in South Florida for over seven years, Handwerger began a daily newsletter, which grew to include thousands of readers from over 40 nations.

    DISCLOSURE:

    1) Brian Sylvester conducted this interview for Streetwise Reports LLC, publisher of The Gold Report, The Energy Report, The Life Sciences Report and The Mining Report, and provides services to Streetwise Reports as an independent contractor. He owns, or his family owns, shares of the following companies mentioned in this interview: None.

    2) The following companies mentioned in the interview are sponsors of Streetwise Reports: Comstock Mining Inc., Gold Standard Ventures Corp., Integra Gold Corp., NOVAGOLD, NuLegacy Gold Corp., Red Eagle Mining Corp. and Ucore Rare Metals Inc. Streetwise Reports does not accept stock in exchange for its services.

    3) Jeb Handwerger: I own, or my family owns, shares of the following companies mentioned in this interview: Ucore Rare Metals Inc., International Tower Hill Mines Ltd., Barisan Gold Corp., Integra Gold Corp., Canamex Resources Corp., NuLegacy Gold Corp., Corvus Gold Inc., Comstock Mining Inc. and Red Eagle Mining Corp. I personally am, or my family is, paid by the following companies mentioned in this interview: None. My company has a financial relationship with the following companies mentioned in this interview as they are sponsors on my website: Ucore Rare Metals Inc., International Tower Hill Mines Ltd., Barisan Gold Corp., Integra Gold Corp., Canamex Resources Corp., NuLegacy Gold Corp., Corvus Gold Inc., Comstock Mining Inc. and Red Eagle Mining Corp. I was not paid by Streetwise Reports for participating in this interview. Comments and opinions expressed are my own comments and opinions. I had the opportunity to review the interview for accuracy as of the date of the interview and am responsible for the content of the interview.

    4) Interviews are edited for clarity. Streetwise Reports does not make editorial comments or change experts’ statements without their consent.

    5) The interview does not constitute investment advice. Each reader is encouraged to consult with his or her individual financial professional and any action a reader takes as a result of information presented here is his or her own responsibility. By opening this page, each reader accepts and agrees to Streetwise Reports’ terms of use and full legal disclaimer.

    6) From time to time, Streetwise Reports LLC and its directors, officers, employees or members of their families, as well as persons interviewed for articles and interviews on the site, may have a long or short position in securities mentioned. Directors, officers, employees or members of their families are prohibited from making purchases and/or sales of those securities in the open market or otherwise during the up-to-four-week interval from the time of the interview until after it publishes.

    bokan mountainargentinachilechinacanadagold investingcarlin trend
    The Conversation (0)

    Go Deeper

    AI Powered
    Canadian Maple Leaf gold coin floating over stacked gold bars with glowing red lights.

    Top 5 Junior Gold Mining Stocks on the TSXV in 2026

    Pile of gold bars over black background.

    5 Best-performing Gold Stocks on the TSX in 2026

    Latest News

    New Break Announces $550,000 Non-Brokered Private Placement Offering of Flow-Through Shares

    Sirios Resources Inc. Announces Results of Shareholder Meeting

    Quarterly Activities Report for the Period Ended 30 September 2026

    Quarterly Activities/Appendix 5B Cash Flow Report

    Quarterly Activities/Appendix 5B Cash Flow Report

    More News

    Outlook Reports world

    Resource
    • Precious Metals
      • Gold
      • Silver
    • Battery Metals
      • Lithium
      • Cobalt
      • Graphite
    • Energy
      • Uranium
      • Oil and Gas
    • Base Metals
      • Copper
      • Nickel
      • Zinc
    • Critical Metals
      • Rare Earths
    • Industrial Metals
    • Agriculture
    Tech
      • Artificial Intelligence
      • Cybersecurity
      • Gaming
      • Cleantech
      • Emerging Tech
    Life Science
      • Biotech
      • Cannabis
      • Psychedelics
      • Pharmaceuticals

    Featured Precious Metals Investing Stocks
    OneGold

    OneGold (/GCSPUSD)
    /GCSPUSD

    Heliostar Metals

    Heliostar Metals (HSTR:CC)
    HSTR:CC

    Investor Insight

    Heliostar combines production of ~50,000–55,000 oz in 2026 with a pipeline of high-margin development assets in Mexico led by Ana Paula. Supported by operating cash flow from La Colorada and San Agustin, a debt-free balance sheet and strategic expansion into the US with the Goldstrike project in Utah, the company is positioned to scale into a 500,000 oz per year gold producer.

    Overview

    Heliostar Metals (TSX:HSTR,OTCQX:HSTXF,FRA:RGG1) is an emerging gold producer focused on building a mid-tier, multi-asset production platform, anchored in Mexico and complemented by strategic expansion into the United States.
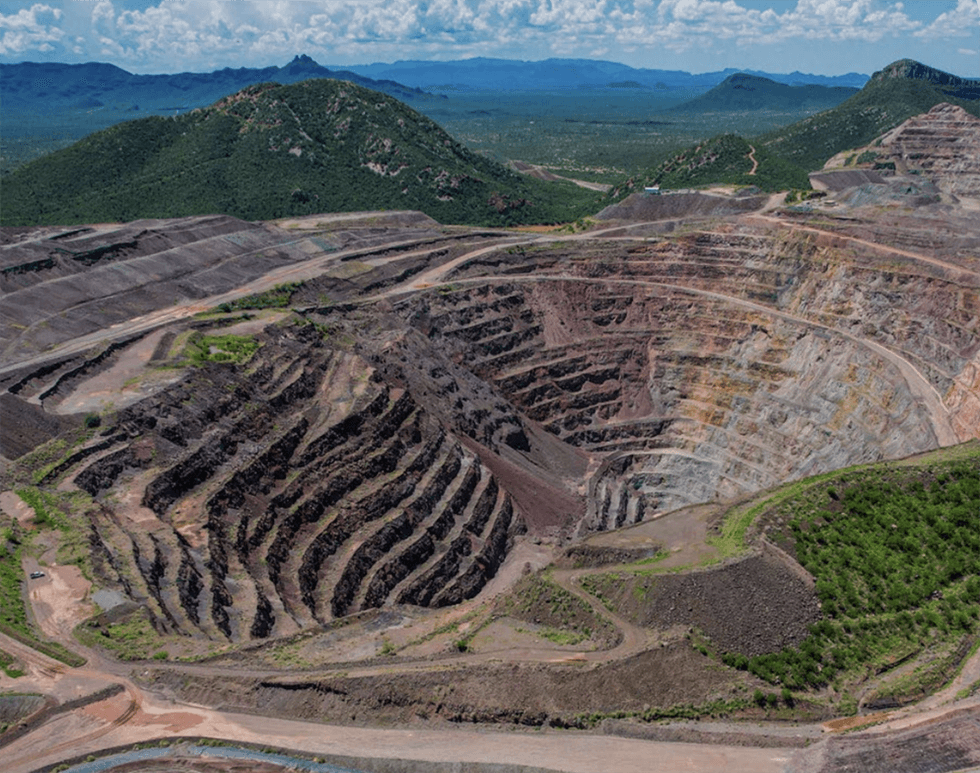
    Heliostar Metals - open-pit mine

    The company has rapidly transformed from an explorer into a producer through disciplined, value-accretive acquisitions, assembling a 100 percent-owned portfolio of producing mines, advanced development projects and exploration assets. This platform provides both immediate cash flow and long-term scalability.

    In 2025, Heliostar produced 34,098 gold equivalent ounces, generated US$47.4 million in mine operating earnings, and ended the year with US$40.6 million in cash and no debt, demonstrating strong execution and financial discipline.

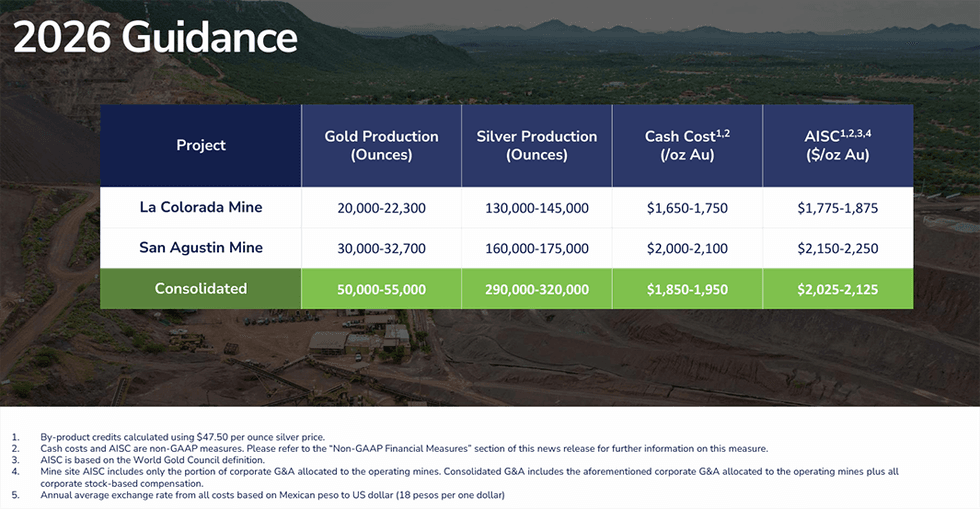
    Production is expected to increase to 50,000–55,000 oz in 2026, driven by La Colorada and San Agustin. Development of Ana Paula and Cerro del Gallo supports a clear pathway to 500,000 oz annual production by 2030.
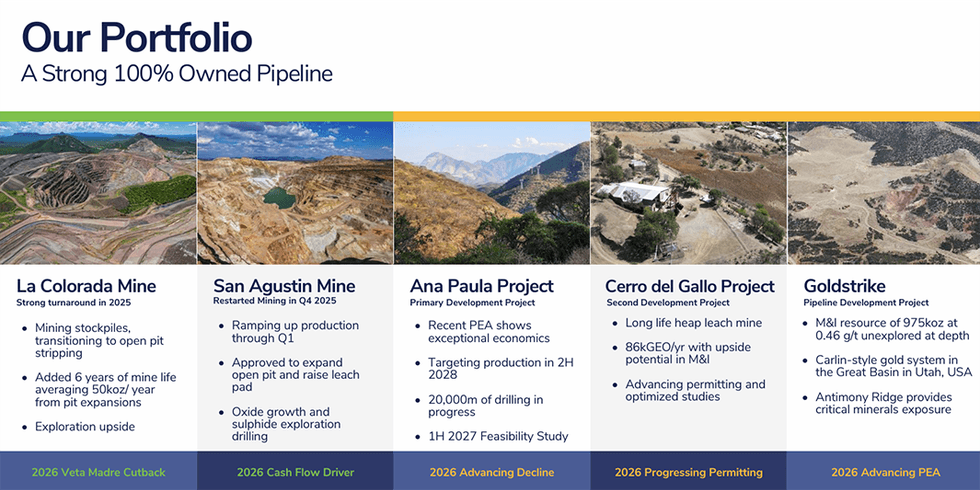
    Heliostar Metals portfolio

    In 2026, Heliostar formed part of the OTCQX’s Best 50 top-performing companies. The company ranked 8th overall, joining 7 other mining companies in the top 10.

    Beyond its core Mexican portfolio, the addition of the Goldstrike project in Utah introduces further growth optionality, reinforcing Heliostar’s strategy of acquiring and advancing underexplored assets with strong development potential. With a staged growth strategy, strong margins and an expanding resource base, Heliostar is positioned to evolve into a 500,000 oz per year gold producer by 2030.

    Company Highlights

    • Growing Production Base: Two producing mines targeting 50,000–55,000 oz of gold in 2026, generating cash flow to fund development.
    • Clear Path to Mid-Tier Scale: Staged growth targeting annual production of 500,000 oz by 2030.
    • High-Margin Flagship Asset: The Ana Paula PEA outlines 101,000 oz/year production (post ramp-up) with strong economics, including US$1,012M NPV5% and 51.3% IRR at higher gold price assumptions, supporting a 2028 production target.
    • Self-Funded Growth Model: Generated US$47.4 million in mine operating earnings (2025) with US$40.6 million in cash and zero debt, reducing reliance on equity dilution.
    • Robust Resource Base: Approximately 7.3 Moz measured and indicated gold resources plus ~1.4 Moz inferred, supporting long-term scalability.
    • High-Quality Development Pipeline: Cerro del Gallo targeting 86,000 GEO/year at US$1,390 AISC, alongside San Antonio’s production potential.
    • Strategic Expansion in the US: Acquisition of the Goldstrike project in Utah adds near-surface oxide potential and long-term growth optionality.
    • Strong Institutional Backing: Approximately 53 percent institutional ownership, complemented by high-net-worth investors and management alignment.

    Key Projects

    Ana Paula (Flagship Development Project)
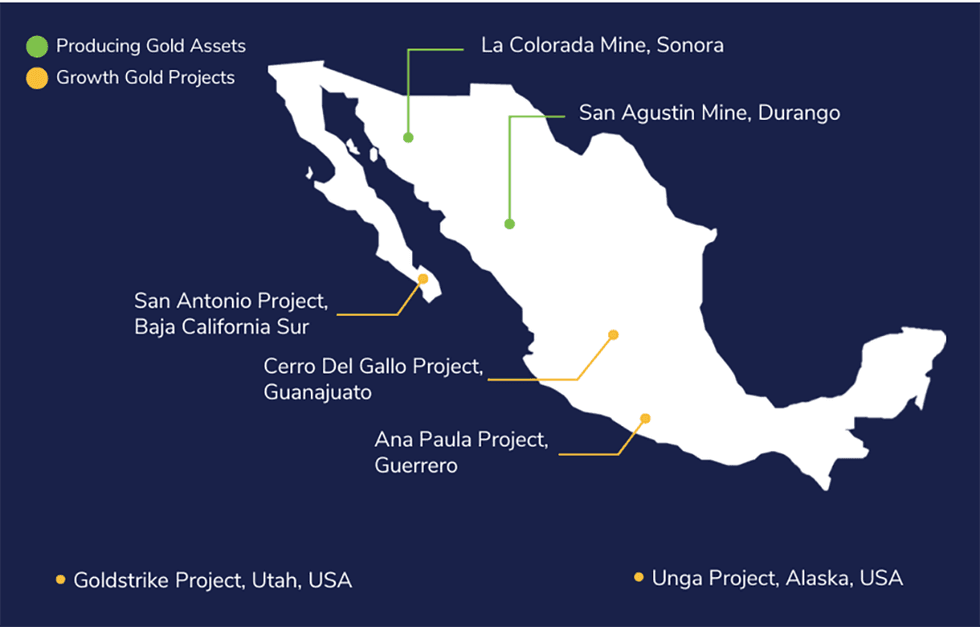
    Heliostar Metals \u200bAna Paula Project

    Ana Paula is a high-grade underground gold project in Guerrero and the cornerstone of Heliostar’s long-term growth strategy.

    The November 2025 PEA outlines a 9 year mine life with 101,000 oz/year production, 874,700 oz total output, and strong economics, including a US$1,012M NPV5% and a 51.3 percent IRR, supported by a low AISC of US$1,011/oz.

    The project hosts approximately 742,000 oz measured and indicated at 5.4 g/t and 514,000 oz inferred, highlighting its high-grade profile and expansion potential.
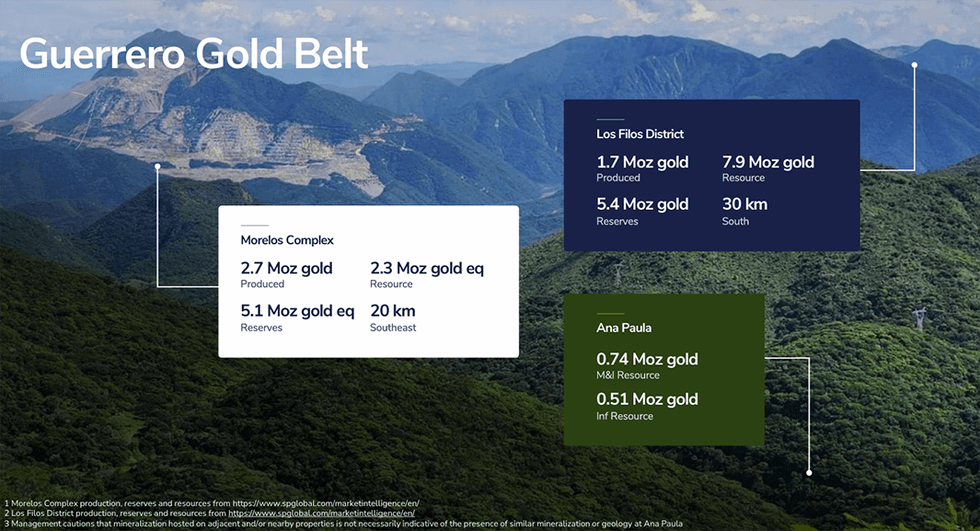
    Heliostar Metals Guerrero Gold Belt

    With a feasibility study targeted for H1 2027 and construction expected in H2 of the same year, Ana Paula is expected to become the primary driver of Heliostar’s transition to mid-tier production.

    The company is targeting production at Ana Paula in 2028.

    La Colorada Mine
    Heliostar Metals \u200bLa Colorada Mine

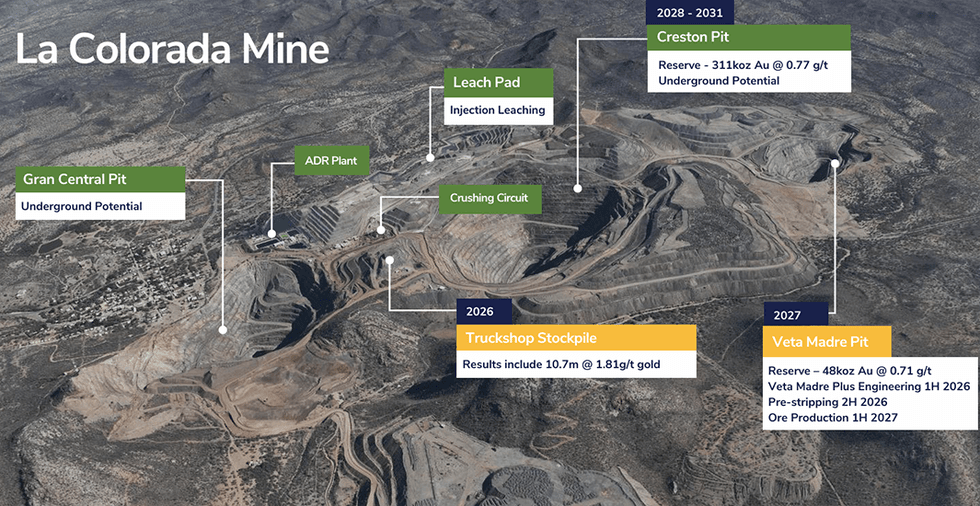
    La Colorada in Sonora is a key cash-flowing asset that underwent a successful turnaround in 2025. The mine hosts reserves of 376,000 ounces of gold grading 0.68 g/t in 17.1 million tonnes of ore.

    The mine is expected to produce 20,000–22,300 oz in 2026 at AISC of US$1,775–1,875/oz, supported by a six-year mine life and approximately 286,000 oz total production profile.

    Mining at the project’s Veta Madre pit commenced in August 2026, a milestone that the company ties to its plan to secure cash flow through 2027 and 2028 to support construction at Ana Paula.

    Ongoing drilling, pit expansions and underground potential provide meaningful upside, reinforcing its role as a core funding engine for development.
    Heliostar Metals 2026 Guidance

    San Agustin Mine

    San Agustin in Durango is a restarted oxide heap-leach operation providing near-term production growth and cash flow.

    2026 guidance targets 30,000–32,700 oz of gold at AISC of US$2,150–2,250/oz, following a low-capital restart funded from the company’s balance sheet.

    The asset offers additional upside through oxide expansion and sulphide exploration, supporting potential mine life extension.

    Cerro del Gallo Project

    Cerro del Gallo is a large-scale gold-silver development project in Guanajuato and a key driver of future production growth.

    The 2025 PFS outlines ~86,000 GEO/year over a 15-year mine life at US$1,390 AISC, with strong economics, including US$972 million NPV5% and 59.3 percent IRR at higher gold price assumptions.

    The project is expected to play a central role in advancing Heliostar towards the goal of 500,000 oz annual production by 2030.

    San Antonio Project

    San Antonio is a 100%-owned heap-leach development project offering strong optionality and long-life production potential.

    The project hosts approximately 1.74 million ounces of measured and indicated gold and demonstrates attractive optionality, including potential 80,000 oz/year production and low AISC of US$1,063/oz.

    As permitting advances, San Antonio represents a key medium-term growth opportunity within the portfolio.

    Goldstrike Project (Utah, USA)

    Goldstrike is a newly acquired gold project that expands Heliostar’s footprint in the United States and adds exploration and development optionality. The property currently hosts an Indicated resource of 975 kilo ounces at 0.46 g/t of gold.

    The project hosts a near-surface oxide gold system with historical production of approximately 209,000 ounces of gold and defined mineralization, offering potential for low-cost, open-pit heap-leach development. Its geological setting and existing dataset provide a strong foundation for resource growth and technical advancement.

    Goldstrike complements Heliostar’s acquisition strategy by adding a scalable, underexplored asset outside its core Mexican portfolio, enhancing long-term growth potential.

    Drilling is underway at Goldstrike to test the antimony and gold potential of both Antimony Ridge and Antimony Knoll, with results expected towards the end of 2026.

    Management Team

    Charles Funk – President & CEO

    Charles Funk has over 20 years of experience in exploration and business development, including senior roles at Newcrest Mining and OZ Minerals. He led the Panuco discovery for Vizsla Silver, demonstrating strong capability in identifying high-value deposits. At Heliostar, he has driven the company’s transformation into a multi-asset gold producer through disciplined acquisitions. His leadership is focused on building a scalable, mid-tier gold platform.

    Gregg Bush – Chief Operating Officer (COO)

    Gregg Bush is a proven mine builder with extensive experience in mine development, integration and operations. He previously served as COO of Capstone Mining and held senior leadership roles at Equinox Gold. Bush brings deep expertise in optimizing operating assets and advancing projects into production. He plays a key role in executing Heliostar’s production growth strategy.

    Sam Anderson – VP Projects

    Sam Anderson has approximately 25 years of experience in mine geology and project development, including 17 years at Newmont. He played a key role in advancing the Merian Mine from resource stage through construction to steady-state production. His expertise spans exploration, resource expansion and project execution. At Heliostar, he leads the advancement of key development assets.

    Mike Gingles – VP Corporate Development

    Mike Gingles brings more than 35 years of experience in the mining industry, specializing in corporate development and M&A. He played a leadership role in major transactions including Pueblo Viejo and Turquoise Ridge. His expertise includes project evaluation, deal structuring and strategic partnerships. He supports Heliostar’s acquisition-driven growth strategy.

    Hernan Dorado – VP Sustainability & Special Projects

    Hernan Dorado is a fifth-generation miner with over 20 years of experience in mining operations, particularly in Mexico. He was a founding member of Guanajuato Silver, where he served as COO. His expertise includes permitting, community engagement and sustainability practices. He ensures responsible development across Heliostar’s operations.

    Vitalina Lyssoun – Chief Financial Officer (CFO)

    Vitalina Lyssoun is a Chartered Professional Accountant (CPA, CA) with more than 16 years of experience in financial management within the resource sector. She has extensive expertise in public company reporting, compliance and internal controls. Prior to joining Heliostar, she led the corporate accounting function at Gatos Silver. Her experience spans multiple international jurisdictions.

    Stephen Soock – VP Investor Relations & Development

    Stephen Soock has nearly 20 years of experience across mining operations and capital markets. He began his career in technical roles at mine sites before transitioning to equity research, where he spent eight years covering growth-stage mining companies. He is a mining engineer and CFA Charterholder. At Heliostar, he leads investor relations and supports capital markets strategy.
    Silver Hammer Mining

    Silver Hammer Mining (HAMR:CC)
    HAMR:CC

    Renforth Resources

    Renforth Resources (RFR:CC)
    RFR:CC

    Orosur Mining

    OMI:CC

    GoldInxs Mining

    GoldInxs Mining (INXS:CC)
    INXS:CC

    Investor Insight

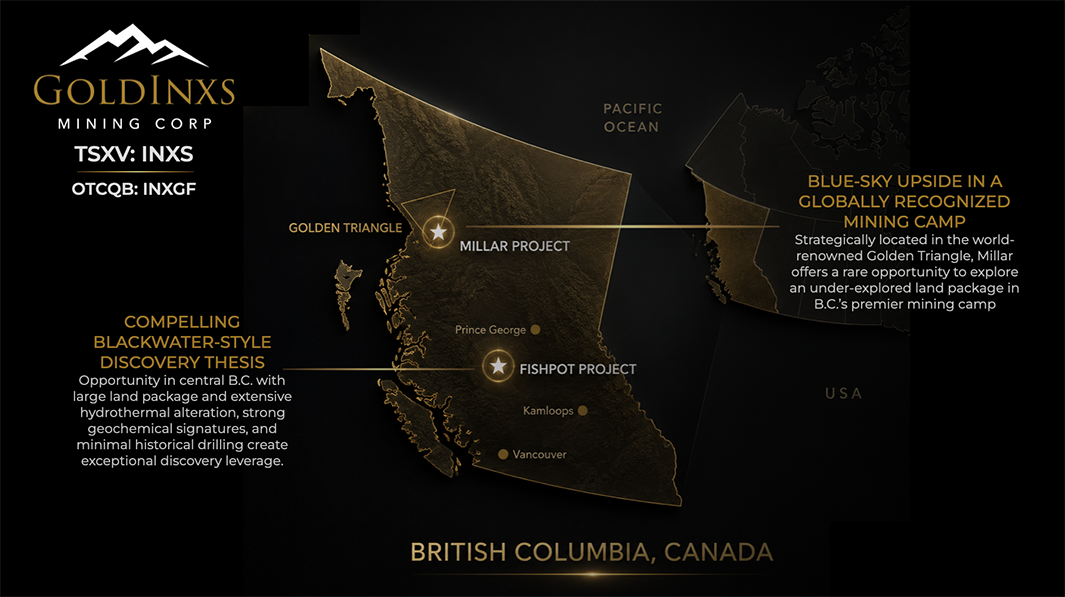
    GoldInxs Mining Corp. (TSXV:INXS, OTCQB: INXGF) provides investors with exposure to early-stage gold-copper exploration in British Columbia, leveraging a portfolio of high-potential projects in Tier 1 jurisdictions, within established gold districts, surrounded by strong regional infrastructure and led by an experienced management team committed to accelerating discovery and delivering shareholder value.
    GoldInxs Mining Corp

    Enjoy the videos and music you love, upload original content, and share it all with friends, family, and the world on YouTube.

    Overview

    GoldInxs Mining Corp. is a discovery-focused mineral exploration company dedicated to identifying and advancing high-potential copper-gold assets in proven geological belts. The Company's strategy centers on acquiring overlooked and underexplored projects with large-scale potential, applying modern exploration techniques to rapidly evaluate targets and unlock shareholder value through discovery.

    The Company’s. common shares started trading on the TSX Venture Exchange in July 2026 under the symbol INXS, positioning itself to capitalize on favorable copper and gold market fundamentals.
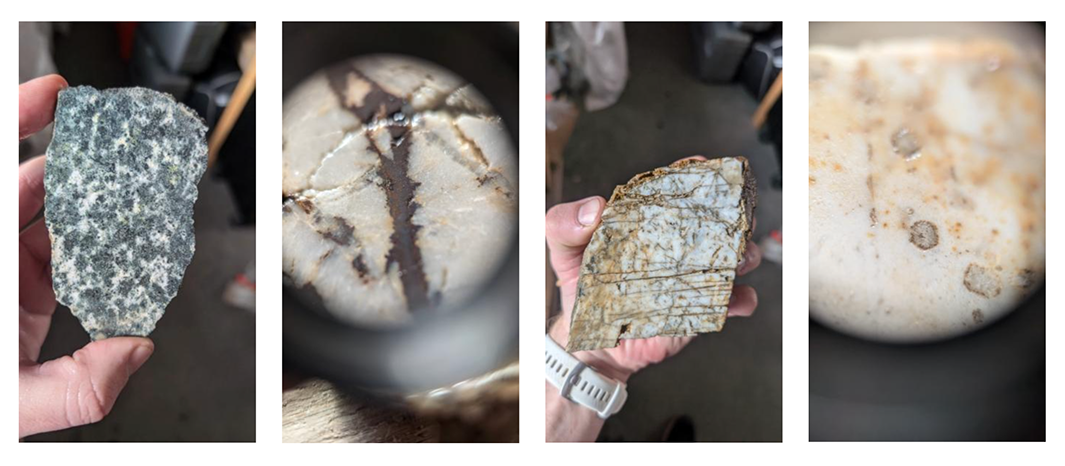
    GoldInxs Mining sample rocks

    Copper demand is forecasted to grow steadily through 2030, with the global copper market expected to expand to over US$340 billion by 2030, driven by electric vehicles, renewable energy and infrastructure growth.

    On the other hand, gold continues to provide a safe-haven hedge against policy risks and market volatility, making GoldInxs’ dual focus on copper and gold particularly compelling for investors.

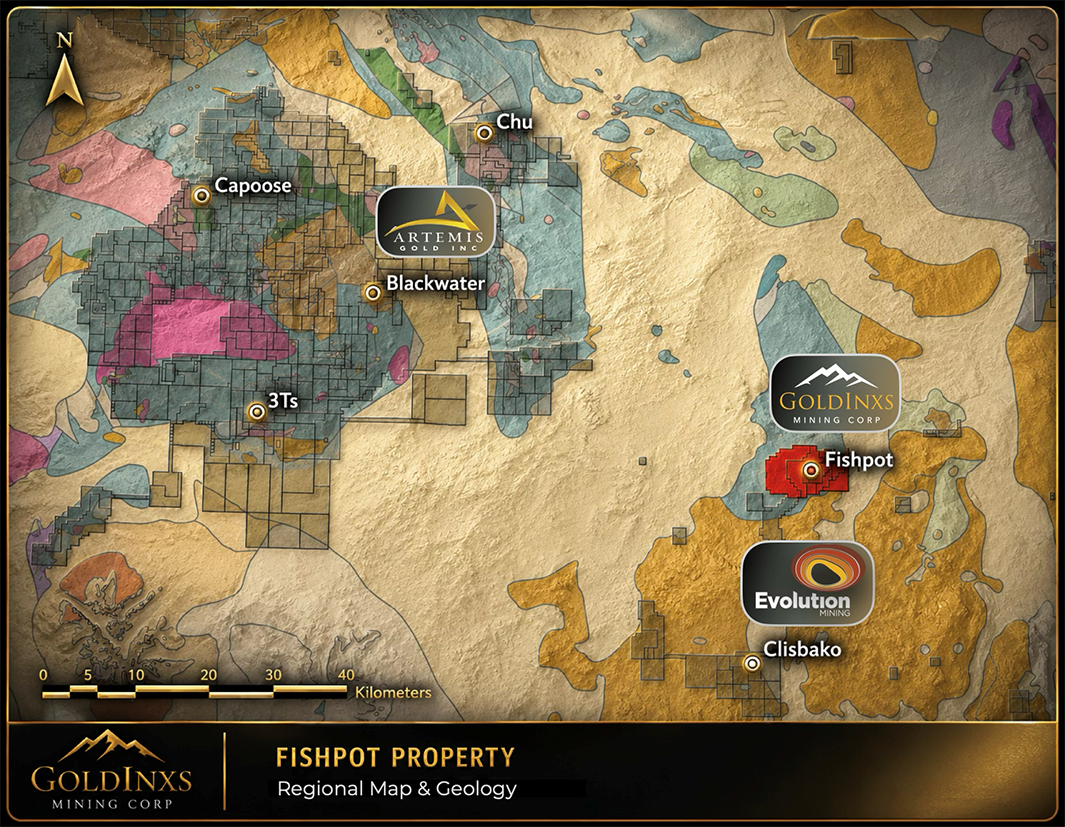
    The Company’s portfolio is anchored by two priority projects: the Fishpot Project in central British Columbia, interpreted as an emerging, large epithermal system with strong infrastructure access and jurisdiction quality as well as early indications of blackwater-style mineralization, and the non-core Millar Project in the prolific B.C Golden Triangle, a district renowned for world-class discoveries. While surrounding deposits attracted billions of dollars in investment, Fishpot received only sporadic historical exploration despite widespread hydrothermal alteration and numerous anomalous gold, silver and copper results. Artemis Gold’s Blackwater Mine has announced tripling production with an intended $1.56B investment, which sits only 65 km from the Fishpot property.

    Backed by a management team with expertise in exploration, project development and capital markets, GoldInxs is positioned to rapidly advance its assets, deliver near-term exploration catalysts and create shareholder value through discovery and strategic growth.

    Company Highlights

    • Mining-friendly jurisdiction: Projects are in British Columbia, which ranked second in Canada and 20th globally in the 2025 Fraser Institute investment attractiveness rankings.
    • Flagship and district-scale assets: Portfolio is anchored by the flagship Fishpot Project (“Fishpot”) in central B.C., showing strong geological indicators of mineralization, blackwater-style mineralization potential and immense exploration upside potential with only 378 meters of historical drilling. Fishpot is strategically located in the same region as Artemis Gold’s Blackwater Mine and Evolution Mining’s optioned Clisbako property.
    • Clear path to 2026 catalysts: GoldInxs secured a drill permit for an upcoming maiden 2,000-metre drill program at Fishpot, near-term exploration programs are designed to define mineralized systems, outline blackwater-style potential and create shareholder value following the completion of a 3D IP survey and drill targeting.

    Key Projects

    Fishpot Project
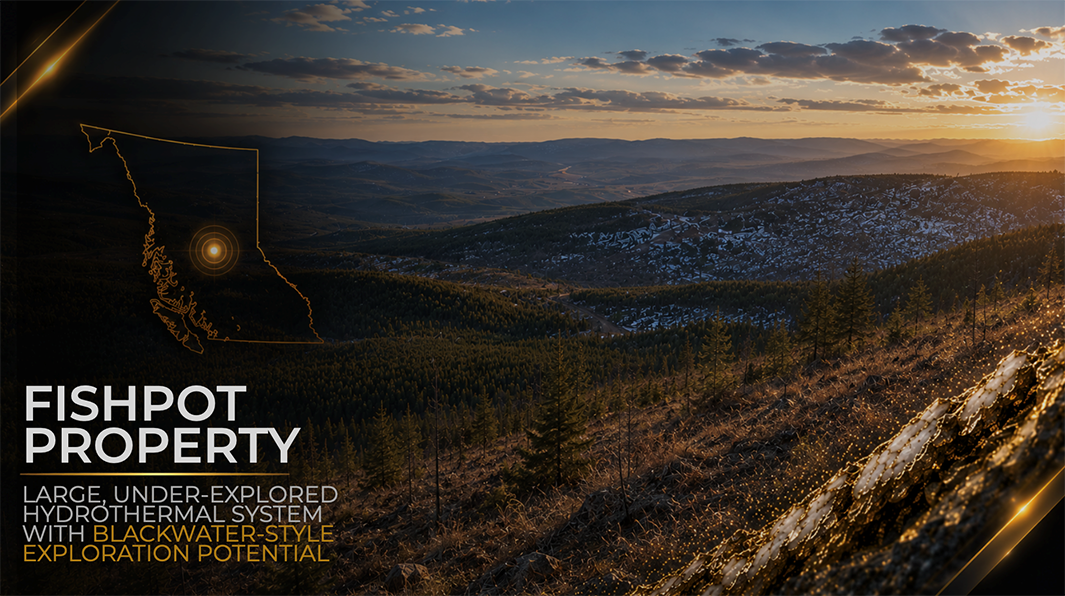
    GoldInxs Mining Fishpot Project


    Fistpot property

    The Fishpot Project represents the cornerstone asset within the GoldInxs portfolio. Covering up to 5,500 hectares in Central British Columbia, and located ~95 km north of Quesnel, Fishpot hosts a large hydrothermal alteration system that exhibits many of the geological characteristics observed in major epithermal and intrusion-related gold systems throughout the region. Fishpot encompasses five claim blocks, held under an option to acquire 100 percent subject to a 2 percent NSR, representing a significant exploration opportunity in a highly prospective region.

    Fishpot represents a largely untested hydrothermal mineral system where multiple independent exploration datasets, including gold-silver-copper surface geochemistry, alteration and geology, airborne magnetics, 3D IP chargeability/resistivity and identified epithermal-to-potential-porphyry target environments, are converging to define drill targets, despite only 378 metres of historical drilling across two holes.

    Fishpot is situated within the highly prospective Stikine Terrane and is underlain by Hazelton Group volcanic rocks and intrusive units comparable to those associated with several significant deposits in British Columbia. Extensive quartz-sericite alteration, hydrothermal brecciation, pyrite mineralization and multi-element geochemical anomalies support the interpretation of a robust mineralizing system. Fishpot is strategically positioned near active and historical mining operations, including Artemis Gold’s Blackwater Deposit, Newton Gold Project, Capoose and 3Ts Project, underscoring its large-scale discovery potential. Importantly, based on early-exploration results, Fishpot shares several regional geological characteristics commonly associated with Blackwater-style gold systems, including felsic volcanics, strong alteration, pyrite-rich mineralization and gold-silver geochemical associations. Despite the similarities the Company cannot yet make any formal connections to the surrounding properties, nor can they guarantee that such deposits exist on their ground.

    Fishpot Exploration Technology: GoldInxs advanced its Fishpot targeting program by combining a conventional 3D IP survey with emerging Virtual DRILL™ remote-sensing technology as an additional targeting layer, using multiple geological, geochemical and geophysical datasets to refine and prioritize targets ahead of a planned ~2,000-metre drill program.

    Fishpot Drill Permit & Expansion: GoldInxs has received the required drilling permits and expanded Fishpot to 5,509 hectares, positioning the Company to proceed with its inaugural ~2,000-metre modern drill program on a property that has seen very limited historical drilling, while refining targets through integrated geological, geochemical and geophysical data.

    Despite multiple encouraging exploration indicators, Fishpot has been subjected to only two historic drill holes totaling 378 metres, leaving the broader mineral system largely untested and providing significant leverage to future exploration success.

    Recent exploration completed by GoldInxs generated the highest reported gold value on Fishpot to date, returning up to 5.65 g/t Au from surface sampling, while airborne geophysical surveys identified multiple coincident magnetic and geochemical anomalies that have strengthened the Company's exploration model and target pipeline.

    The 2025 program returned rock samples of up to 5.65 g/t Au, 11.35 g/t Ag and 0.42% Cu, while historical work reportedly returned up to 4.36 g/t Au and 3.2% Cu.

    The property exhibits the potential low-sulphidation epithermal targets at Fishpot North, intermediate-sulphidation signatures at Fishpot East, and a large central magnetic high being evaluated for potential porphyry mineralization at depth. The Company is focused on finalizing drill targeting and preparing for the inaugural diamond drill campaign at Fishpot in the coming months following completion of the IP survey. GoldInxs is preparing to drill-test a 5,509-hectare, largely undrilled hydrothermal system in central British Columbia where high-grade surface gold-silver-copper results, Blackwater-style geological characteristics and multiple coincident geophysical targets have converged to define a portfolio of high-priority exploration targets.

    Management Team

    Nick Michael – President and CEO

    Mr. Michael is a veteran mining executive and technical director with over 37 years of global experience spanning mine development, engineering and operational leadership. His expertise covers the full project lifecycle, including design, construction, technical due diligence and Independent Engineer assignments for institutional investors and project financiers. He also leads CJK Milling, a company focused on reprocessing historical mine waste to recover discarded gold decades ago, when it was less valuable.

    Carlo Rigillo, CPA, Chief Financial Officer

    Mr. Rigillo is an experienced Chartered Professional Accountant with over two decades of experience. He holds a Bachelor of Commerce from the University of Toronto.

    Barry Miller – Executive Chairman and Director

    Mr. Miller brings over 30 years of experience in public markets, including roles as a broker, consultant and financier. He is the founder of GoldInxs and has been actively involved in the resource sector through leadership positions, including as director of Tinova Resources Corp., an exploration company focused on tin and rare earth elements in British Columbia and Alaska.

    Tara Asfour - Vice President, Corporate Development and Communications

    An executive consultant with over 13 years of experience, Tara Asfour holds expertise in corporate development, capital markets, investor relations and strategic communications. She has led strategic financings, partnerships and offtake initiatives within the resource sector through previous corporate development and investor relations roles with multiple publicly listed companies.

    Al Fabbro – Director

    With over three decades of experience spanning both the mining and finance sectors, Mr. Fabbro previously led Yorkton Securities’ retail trading department and was part of its Natural Resources Group. He later served as Lead Director of Roxgold Inc. and currently holds executive leadership roles in the mining industry.

    Darcy Vis, P.Geo. – VP Exploration and Director

    Mr. Vis is an economic geologist with over 17 years of experience in mineral exploration. He has held senior technical roles across multiple exploration companies and is the President of Tripoint Geological Services Ltd. His expertise includes target generation, project evaluation and exploration program execution.

    Stephen Soock, P.Eng., CFA – Director

    Mr. Soock is a mining professional with nearly 20 years of experience spanning both technical operations and capital markets. He currently serves as Vice President, Investor Relations and Development at Heliostar Metals.

    Christopher Kelly, PQS, FCIArb – Director

    Mr. Kelly has over 15 years of experience in construction and natural resources. He holds a BSc in Construction Economics and Management and an MSc in Construction Law and Dispute Resolution, and runs Trachtala Consulting Ltd.

    More featured stocks

    Browse Companies

    Resource
    • Precious Metals
    • Battery Metals
    • Energy
    • Base Metals
    • Critical Metals
    Tech
    Life Science
    MARKETS
    COMMODITIES
    CURRENCIES