The Conversation (0)
Featured Energy Investing Stocks
Investor Insight
Coelacanth Energy is a pure-play Montney oil and natural gas company advancing one of the largest contiguous land positions in the Montney light oil window of northeastern British Columbia. Supported by a substantial discovered and undiscovered hydrocarbon resource base, growing production, established infrastructure and a management team that has built and sold six successful energy companies, Coelacanth is executing a strategy focused on increasing both near-term cash flow and long-term resource value.
Overview
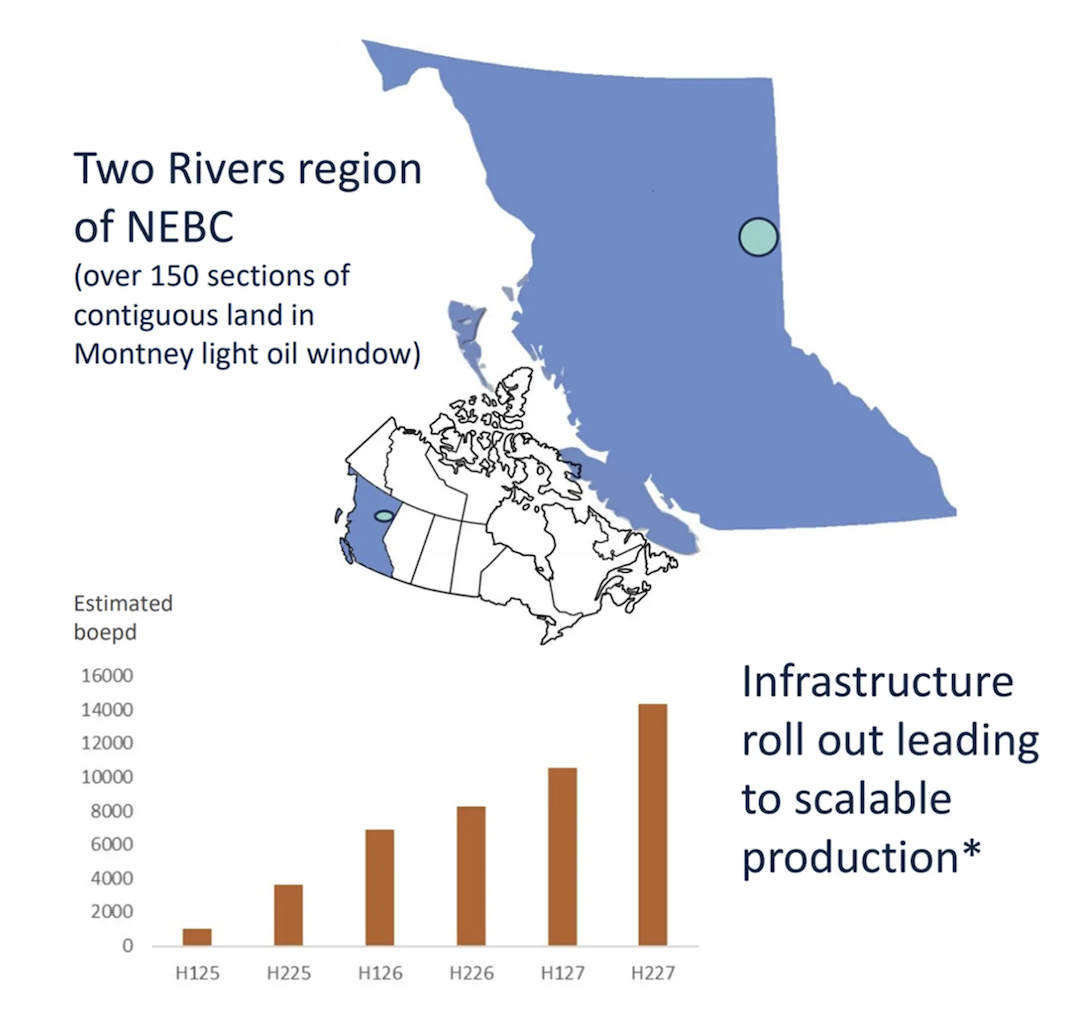
Coelacanth Energy (TSXV:CEI) is a Canadian oil and natural gas exploration and development company focused on the Montney Formation in northeastern British Columbia. The company controls over 150 contiguous sections in the Two Rivers region, a strategically positioned acreage block within the Montney light oil window. As one of the largest landholders in this highly prospective area, Coelacanth has assembled a large-scale resource platform with significant development potential.
The company’s asset base is supported by substantial petroleum initially-in-place estimates prepared by GLJ. These include 6.9 billion barrels of discovered oil PIIP and 8.3 billion barrels of undiscovered oil PIIP, alongside 5.9 Tcf of discovered gas PIIP and 7.1 Tcf of undiscovered gas PIIP. The resource spans multiple Montney intervals, including the Upper, Lower, Basal and Middle Montney, providing extensive opportunities for future development and delineation.
Coelacanth’s strategy combines near-term production growth with long-term resource value creation. The company has secured critical infrastructure, contracted gas takeaway and processing capacity, and advanced development activities across its Two Rivers assets. Average production reached 7,632 boe/d in Q2 2026, reflecting continued progress in transitioning from delineation and infrastructure buildout toward scalable production growth.
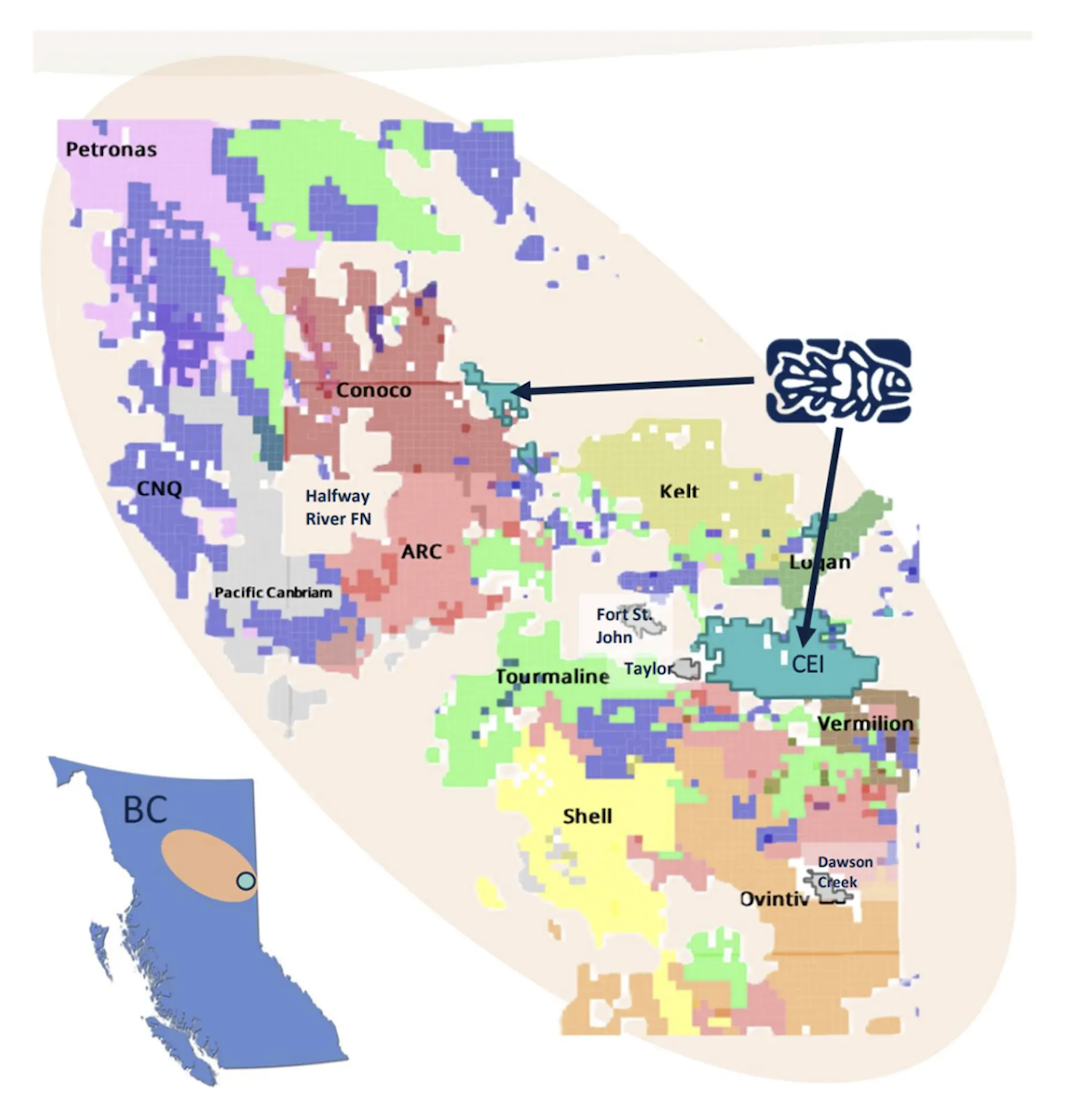
A key differentiator for Coelacanth is its leadership team. Management has successfully built and sold six previous public energy companies and has demonstrated an ability to create value through multiple commodity cycles. Supported by deep operational, geological and financial expertise, the team is focused on disciplined execution of the company’s Montney growth strategy.
Company Highlights
- Premier Montney land position: Controls over 150 contiguous sections in the Two Rivers region of northeastern British Columbia, making Coelacanth the largest landholder in the Montney light oil window.
- Substantial hydrocarbons in place: GLJ estimates 6.9 billion barrels of discovered oil PIIP, 8.3 billion barrels of undiscovered oil PIIP, 5.9 Tcf of discovered gas PIIP, and 7.1 Tcf of undiscovered gas PIIP across the company’s Montney acreage.
- Infrastructure-led growth strategy: Key infrastructure, including facilities, pipelines, processing agreements and gas takeaway capacity, has been secured to support scalable production growth.
- Growing production base: Average production reached 7,632 boe/d in Q2 2026, supported by ongoing development at the Two Rivers project.
- Multiple productive Montney horizons: The asset base includes the Upper, Lower, Basal and Middle Montney intervals, providing extensive development opportunities across multiple zones.
- Strong market access: Secured 100 mmcf/d of gas takeaway capacity and up to 60 mmcf/d of processing capacity, with access to major pipeline networks and potential LNG Canada connectivity through Coastal GasLink.
- Proven value-creation team: Management has built and sold six successful energy companies and brings extensive operational, technical and financial expertise to Coelacanth’s development strategy.
Key Project
Two Rivers Montney Development
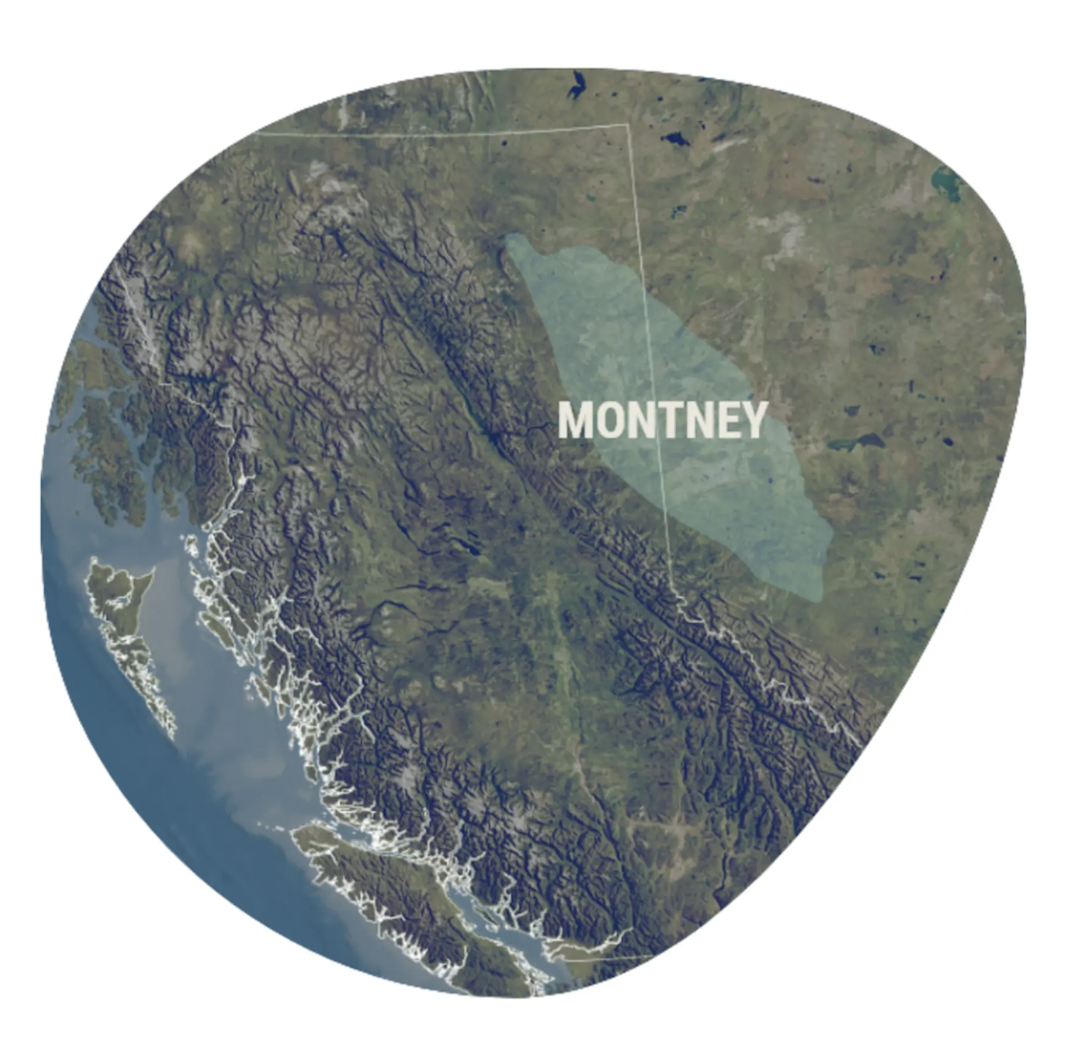
The Two Rivers project forms the cornerstone of Coelacanth’s growth strategy and encompasses the company’s extensive Montney land position in northeastern British Columbia. The project hosts multiple productive horizons, including the Upper, Lower, Basal and Middle Montney intervals, supporting a multi-zone development approach across the acreage. Geological delineation has been completed, providing a strong technical foundation for future drilling and development.
The project has demonstrated commercial productivity through successful drilling and testing programs. Coelacanth established proof of commerciality at both Two Rivers East and Two Rivers West, while development at the 5-19 and 10-08 pads confirmed productivity across multiple Montney benches. All 12 wells on the 5-19 pad were onstream by April 1, 2026, marking a significant milestone in the project’s progression.
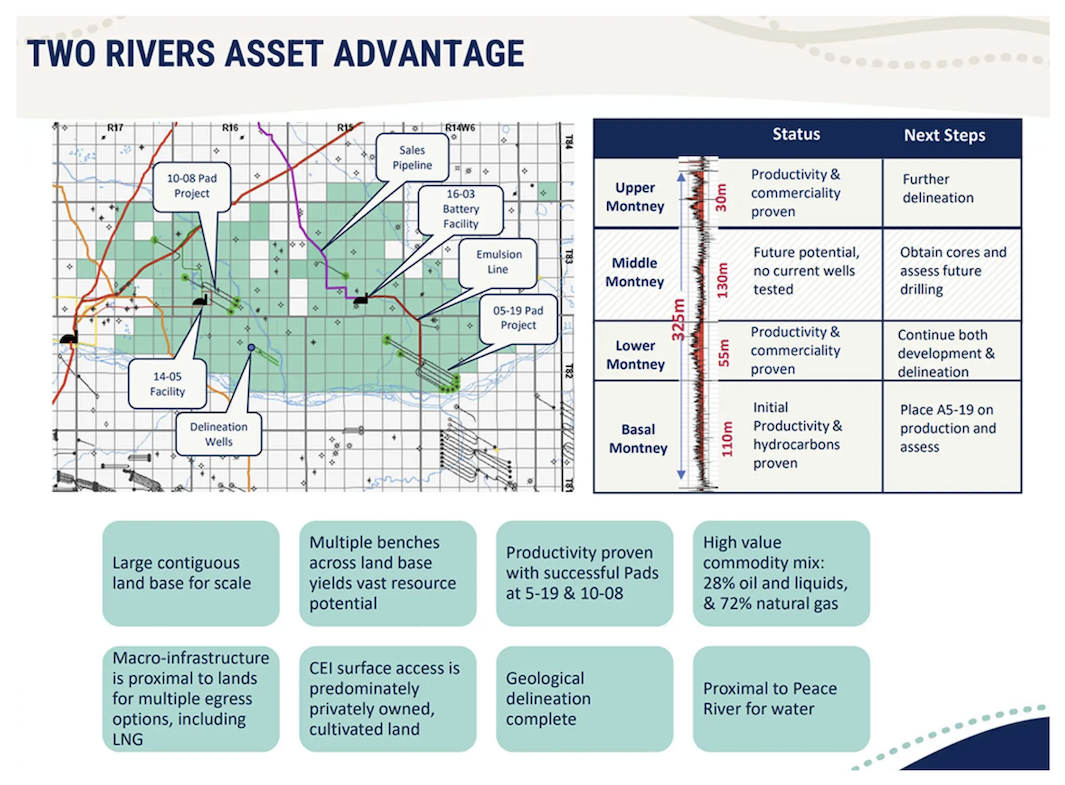
Infrastructure development has been a major focus of the company’s execution strategy. Coelacanth has secured infrastructure financing, completed key facility and pipeline construction, contracted up to 100 mmcf/d of gas takeaway capacity and secured processing capacity of up to 60 mmcf/d. These initiatives establish the infrastructure foundation required to support future production growth.
The Two Rivers asset also benefits from strong market access. The company’s production can access major regional pipeline systems, including NGTL, Westcoast and Alliance, while its acreage is directly connected to LNG Canada through the Coastal GasLink system for potential future delivery. Coelacanth Energy said the long-term view for LNG expansion in British Columbia is very positive for its land, believing that lands with scale and direct access as such will trade at a premium once they are delineated and the resource is proven for development.
Combined with a commodity mix of approximately 31 percent oil and liquids and 72 percent natural gas, the project offers exposure to multiple energy markets.
Management Team
Rob Zakresky – President, CEO and Director
Rob Zakresky is a veteran energy executive who previously served as president and CEO of Leucrotta Exploration, Crocotta Energy, Chamaelo Exploration, Chamaelo Energy, Viracocha Energy and Bellator Exploration. He has a proven track record of building and monetizing public energy companies and leads Coelacanth’s strategic growth and value creation initiatives.
Nolan Chicoine – Vice President of Finance and CFO
Nolan Chicoine previously served as CFO and vice-president finance at Leucrotta Exploration, Crocotta Energy and Chamaelo Exploration, and was controller at Chamaelo Energy and Viracocha Energy. He is responsible for financial strategy, reporting and capital management.
Jody Denis – Vice President of Operations
Jody Denis is a former drilling, engineering and operations engineer at Leucrotta Exploration. His previous experience also includes senior operational and drilling leadership roles with Black Swan Energy, ARC Resources and Birchcliff Energy. He formerly led Coelacanth Energy’s drilling and completions activities.
John Fur – Vice President of Geosciences
John Fur previously served as manager of exploration at Leucrotta Exploration and held senior geophysical positions with Crocotta Energy, Chamaelo Energy, Viracocha Energy, Canadian Natural Resources, Post Energy, Amber Energy and Husky Oil. He oversees geological evaluation and resource delineation across the company’s Montney assets.
Jonathon Hanson — Vice President of Engineering
Jonathon Hanson has 20 years of industry experience. He previously served as manager for exploitation at Spartan Dela Corp, and was a senior exploitation engineer for companies Vermilion Energy, Lynx Energy and Saguaro Resources. He will focus on exploitation and reservoir management for Coelacanth Energy.
Investor Insight
Syntholene Energy is advancing a proprietary synthetic fuel production platform designed to produce high-performance, low-cost synthetic hydrocarbons using renewable electricity, geothermal heat and captured carbon. Following successful prototype-scale validation in 2022, the company is now operating its Iceland demonstration facility as it plans commercial-scale production capable of serving aviation, transportation, industrial energy and other hard-to-abate fuel markets.
Overview
Syntholene Energy ((TSXV:ESAF,FSE:3DD0, OTC:SYNTF) is a synthetic fuel production company company focused on developing high-performance, low-cost synthetic liquid fuels. The company is commercializing its proprietary Hybrid Thermal Production System, which combines renewable electricity, geothermal heat, water and captured carbon to produce synthetic hydrocarbons that can serve as direct replacements for conventional petroleum-derived fuels.
Unlike many alternative energy solutions that require extensive changes to existing infrastructure, synthetic fuels can be transported, stored and utilized through today’s fuel supply chains. The resulting fuels are molecularly pure, free from many contaminants associated with conventional fuels and compatible with existing engines, turbines, storage systems and transportation infrastructure. Produced using renewable electricity, hydrogen and captured carbon, the fuels can deliver over 90 percent lower lifecycle emissions while maintaining the energy density and performance characteristics required across multiple industries.
At the core of the company’s platform is its Hybrid Thermal Production System, which combines high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors. By incorporating low-cost thermal energy into critical production stages, Syntholene seeks to reduce electricity consumption, the largest cost component for most eFuel producers. This approach underpins the company’s targeted 70 percent cost advantage relative to competing technologies and supports its objective of producing cost-competitive synthetic fuels at commercial scale.
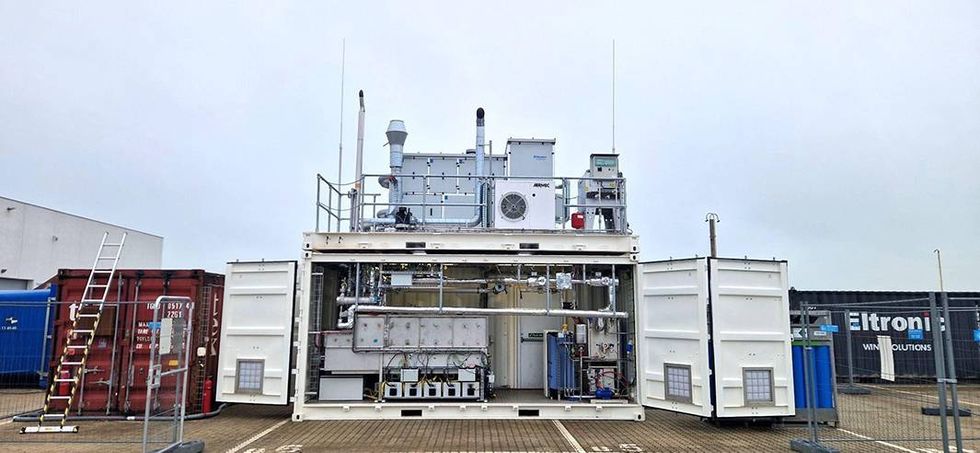
The technology builds upon advancements in high-temperature electrolysis, including work undertaken at Idaho National Laboratory. Following successful prototype-scale validation in 2022, Syntholene is progressing toward field-scale demonstration in Iceland. The company believes a successful demonstration will support future commercial deployment across a range of synthetic fuel applications.
Market demand for low-emission liquid fuels continues to expand across multiple sectors. Sustainable aviation fuel represents Syntholene’s initial commercial focus, supported by increasing airline decarbonization commitments, regulatory mandates, and fuel-blending requirements. Beyond aviation, the broader global eFuel market is projected to grow from US$8.89 billion in 2024 to more than US$215 billion by 2032, creating opportunities across transportation, shipping, industrial energy, and other sectors that depend on liquid hydrocarbon fuels.
Syntholene’s leadership team combines expertise across climate technology, synthetic fuels, industrial engineering, energy infrastructure, project development and resource industries. Recent additions to the advisory board, including former Shell and Suncor executive Marc Mageau and energy industry veteran HY Lee, further strengthen the company’s capabilities as it advances toward commercialization.
Company Highlights
- Addressing a multi-layered growth opportunity: The company is initially targeting sustainable aviation fuel while developing a technology platform capable of serving a substantially larger global liquid fuels market spanning transportation, industrial energy and other hard-to-electrify sectors.
- Proprietary hybrid thermal production system: Syntholene’s technology integrates high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors, utilizing both electricity and thermal energy to improve efficiency and reduce production costs.
- Targeting a 70 percent cost advantage: By introducing low-cost thermal energy into critical stages of production, the company aims to produce synthetic fuels at 70 percent lower cost than competing eFuel technologies.
- Pathway to cost-competitive synthetic fuels: The company believes its technology provides a credible pathway toward producing synthetic fuels that can compete economically with conventional petroleum-derived fuels at scale.
- High-performance fuel characteristics: Synthetic fuels are molecularly pure and free from many contaminants associated with conventional fuels, including sulfur, nitrogen and heavy metals, while remaining compatible with existing infrastructure.
- Over 90 percent lower lifecycle emissions: Synthetic fuels produced from renewable electricity, hydrogen and captured carbon can deliver over 90 percent lower lifecycle emissions than conventional alternatives.
- Prototype validation completed: The company’s production process was successfully demonstrated at prototype scale in 2022 and is now operating a world-first geothermally-integrated demonstration facility in Husavik, Iceland.
- Demonstration facility advancing ahead of schedule: The Húsavík, Iceland facility is now operating, with efficiency and technoeconomic results expected in Q4 2026.
- Strategic geothermal platform: The Iceland project benefits from low-cost geothermal electricity, thermal energy, industrial infrastructure, deep-water port access and an existing 200 MW+ regional grid expansion permitting framework.
- Scalable commercial development strategy: Following demonstration, the company intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts.
Flagship Project
Húsavík Demonstration Facility, Iceland
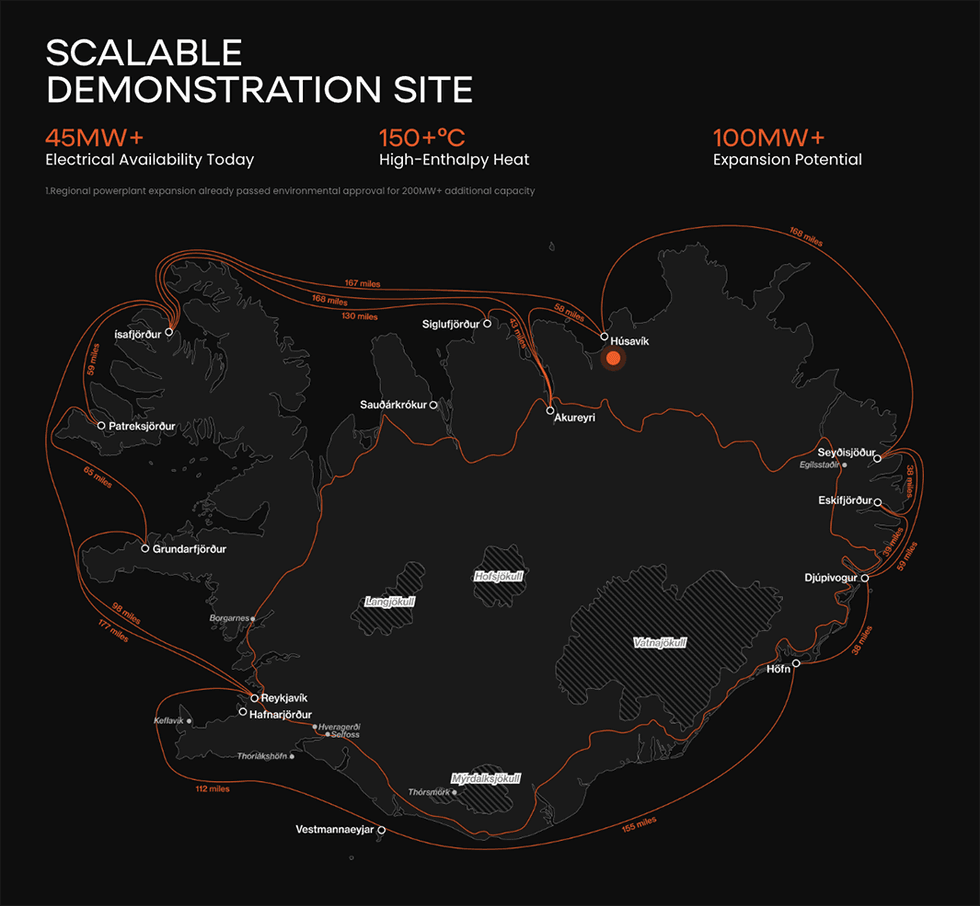
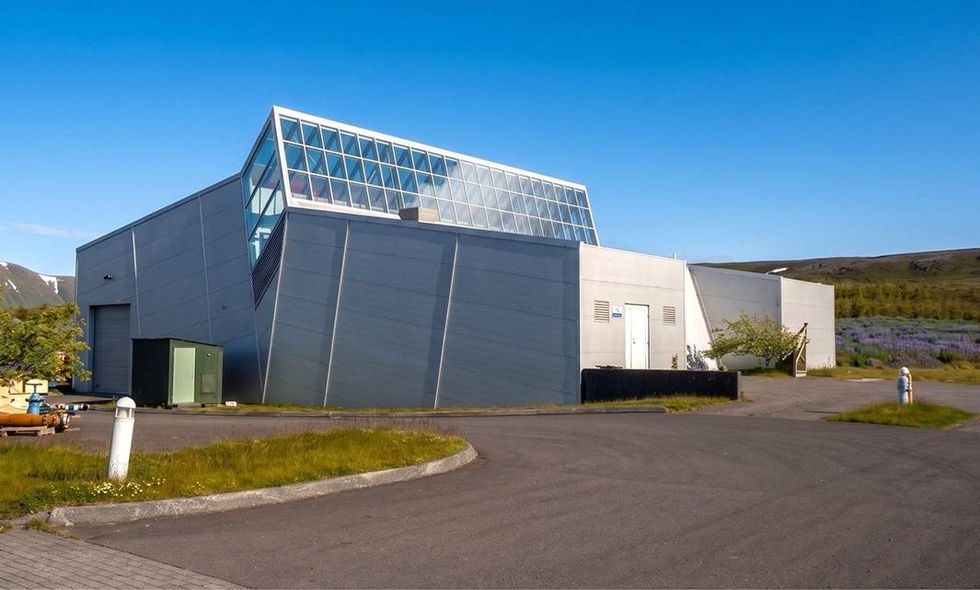
Syntholene’s flagship project is its geothermal-integrated demonstration facility located in Húsavík, northern Iceland. The facility is designed to validate the integration of geothermal heat, high-temperature solid oxide electrolysis and synthetic fuel production technologies under real-world operating conditions. Construction has advanced six months ahead of schedule, with first operations initiated on June 22nd 20266 and efficiency and technoeconomic results expected in Q4 2026.
The project leverages northern Iceland’s abundant geothermal resources, providing access to both low-cost electricity and high-temperature steam. Unlike intermittent renewable energy sources, geothermal energy offers reliable baseload power and thermal energy that can be utilized continuously throughout the fuel production process. The location also benefits from established industrial infrastructure, a skilled workforce, proximity to a deep-water port and a favorable regulatory environment.
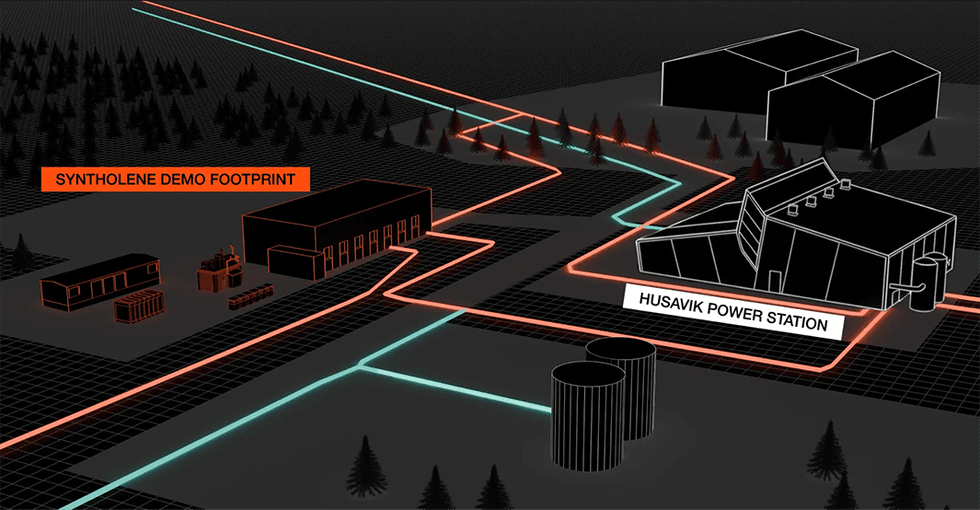
A key objective of the demonstration facility is to validate the company’s thermal integration strategy and confirm that efficiencies achieved during laboratory and prototype testing can be replicated under commercial operating conditions. The facility incorporates Syntholene’s proprietary Thermal Coupling technology, which converts geothermal steam into high-purity industrial steam suitable for use throughout the fuel production process. Management believes this technology is central to achieving the targeted 70 percent cost advantage relative to competing synthetic fuel pathways.
The project also benefits from significant expansion potential. Iceland has completed environmental permitting associated with a 200 MW regional grid expansion, supporting future industrial development in the region. Following a successful demonstration, Syntholene intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts. Management believes the Húsavík location alone has the potential to support development capable of generating approximately US$500 million in annual revenue.
Management Team
Dan Sutton – Chief Executive Officer
Dan Sutton has spent the last 15 years founding and leading sustainable infrastructure businesses. As founder and CEO of Tantalus Labs, he designed, built and operated SUNLAB, scaled the company to 150 employees and grew annual revenue to approximately US$20 million. His expertise spans infrastructure deployment, project development, government relations, public markets and executive leadership.
Steve Oldham – Director
Steve Oldham is a globally recognized leader in carbon management and climate technology commercialization. As former CEO of Carbon Engineering, he helped establish direct air capture as a commercial industry and led the company through its acquisition by Occidental Petroleum at a US$1.6 billion valuation. He currently serves as CEO of Captura.
Canon Bryan – Director
Canon Bryan is a founder and company builder with more than 25 years of experience across advanced energy and resource development. He co-founded Terrestrial Energy, Uranium Energy and NioCorp and brings expertise in finance, corporate development, economic modelling and strategic planning.
John Kutsch – Chief Engineer
John Kutsch leads the integration and optimization of Syntholene’s fuel production platform. He brings more than 30 years of experience across industrial systems design, chemical processing, advanced energy technologies and reactor development, including work supporting high-temperature synthetic fuel systems.
Jack Williams – Head Engineer
Jack Williams specializes in high-temperature and high-pressure reactor systems and synthetic fuel technologies. His research at the University of Cambridge focused on electrolysis systems, catalytic reactor design, CO₂ capture and synthetic fuel production processes.
Grant Tanaka – Chief Financial Officer
Grant Tanaka has more than 15 years of senior financial leadership experience across the global natural resources sector. His background includes senior finance roles at Teck Resources, New Gold and Copper Mountain Mining, combining financial discipline with operational performance management. He was also appointed Corporate Secretary in May 2026.
Anna Pagliaro – Director
Anna Pagliaro is a senior commercial and risk management executive with extensive experience across the energy and mining sectors. Her career includes leadership positions at Vizsla Silver, Ausenco, NexGen Energy and Integra Gold, where she focused on governance, commercial strategy, negotiations and risk management.
Marc Mageau – Advisory Board Member
Marc Mageau joined the Advisory Board in June 2026. He brings more than three decades of operational leadership experience from Shell and Suncor, including expertise in refining, oil sands operations, logistics, infrastructure development and industrial asset management.
HY Lee – Advisory Board Member
HY Lee joined the Advisory Board in May 2026, adding further industrial, operational and strategic expertise as Syntholene advances toward commercial deployment of its synthetic fuel platform.