The Conversation (0)
Aug. 27, 2026 08:30AM PST
As the Treasury prepares to ramp up long-dated bond buybacks amid multi-decade-high yields, the debate over liquidity support versus price management is heating up.
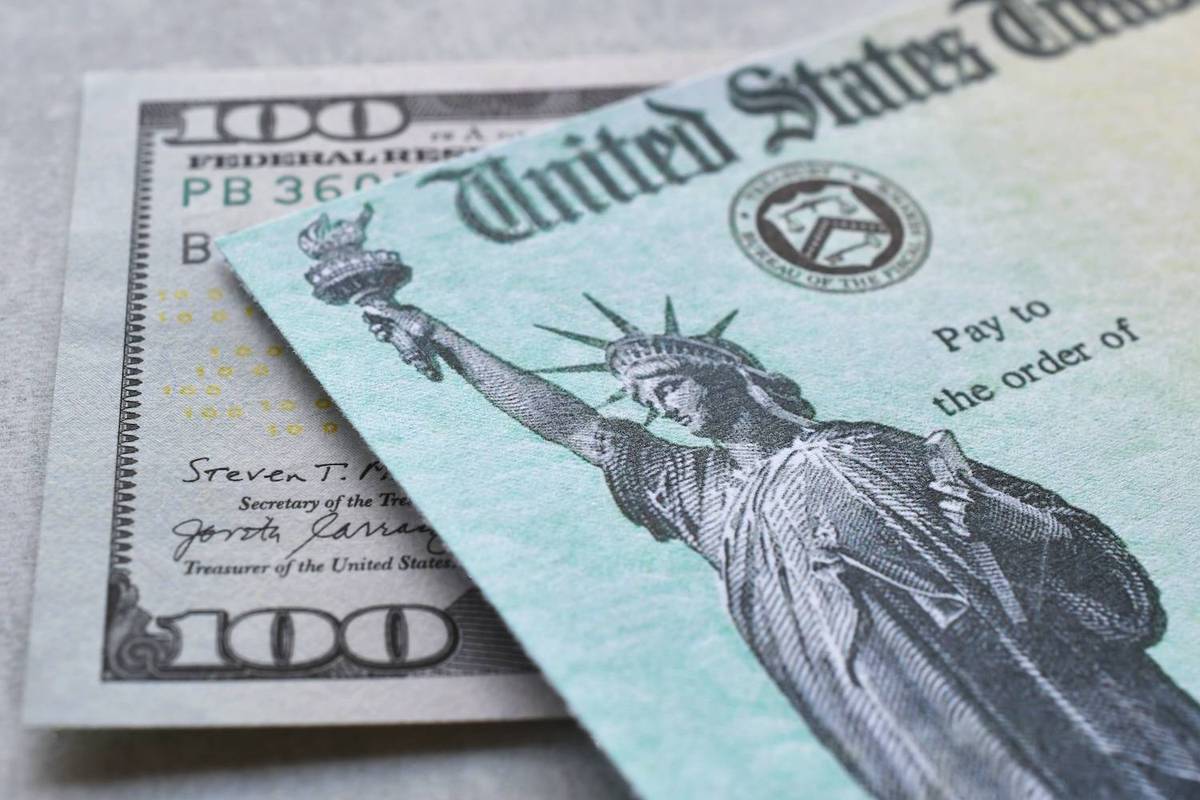
MargJohnsonVA / Adobe Stock
The US Department of the Treasury is roughly doubling the size of its long-dated bond buyback operations, a move that landed just as 30 year yields touched their highest level since 2007.
The move has drawn a public rebuke from billionaire investor Stanley Druckenmiller over whether the American government is managing liquidity or managing prices.
In an August 19 announcement, the Treasury said it would raise the maximum size per operation for buybacks of 10 to 20-year and 20 to 30-year nominal coupon securities from US$2 billion to at least US$4 billion.
The change will be in effect from September 9 to November 4 of this year.
The decision around the increase was framed as routine liquidity support, with the Treasury saying the sectors have shown "consistent strong sponsorship from market participants," evidenced by the "significant volume of high-quality offers Treasury routinely receives in longer-dated buyback operations."
The department said it will give more detail on future buyback sizes at its November 4 quarterly refunding.
The timing put the announcement under scrutiny. As mentioned, it came immediately after 30 year Treasury yields hit a 19 year high, driven in part by war and oil-market worries, according to Reuters.
Yields dropped initially on the buyback news, then erased those gains within 24 hours, climbing back above where they started before easing again later in the week alongside falling oil prices.
That round trip undercut Treasury's framing of the move as routine, and is central to the pushback from Druckenmiller, a hedge fund manager and former George Soros lieutenant, who argues in a Wall Street Journal opinion piece that markets correctly read the buyback expansion as "price management" rather than genuine liquidity management.
He states that trading had remained orderly, with no dealer balance-sheet seizures, no failed auctions and no forced unwinds, noting that nothing in market conditions justified official intervention.
Druckenmiller tied rising yields to deteriorating fundamentals: inflation running between 3 and 4 percent, unemployment at 4.1 percent, a federal deficit near 6 percent of GDP and national debt above US$40 trillion.
"Every basis point of artificial yield suppression is a subsidy to procrastination," he wrote in the Monday (August 24) piece. "Governments defending prices against fundamentals always lose."
Druckenmiller warned that yield management operations tend to escalate — a technical intervention today becomes a larger policy commitment tomorrow — and pointed to hints from Treasury officials that operations could expand further or draw on the Treasury General Account as evidence the pattern was already starting.
Secretary of the Treasury Scott Bessent pushed back directly against those ideas, saying in a video statement, "We haven't bought a single bond yet," as markets digested the policy shift.
The debate over the substance of the buyback program was then overtaken, briefly, by a dispute over how Druckenmiller's critique was written. Social media users ran the op-ed through artificial intelligence (AI) detection tools and flagged it as AI generated; Druckenmiller subsequently confirmed he had used multiple AI tools to draft the piece while on vacation.
"I was a B student in English, but an A+ in economics," he explained. "These are my ideas and I've been speaking about them for over 15 years, as anyone who knows me knows."
He compared using AI to using a calculator or a speechwriter, adding, "At 73 I'm kind of proud of using it. The only embarrassing thing is how many people reached out and told me how much better written this was than normal."
Wall Street Journal editorial page editor Paul Gigot defended the paper's decision to run the piece.
"AI is a fact of modern life," Gigot said in a statement. "The question for us is whether what we publish from contributors reflects an author's original argument, and if the author has the standing and credibility to make it. In Stan Druckenmiller's case, we have had a relationship with him for many years, and nobody can doubt that his op-ed is his genuine opinion."
Whether the Treasury's buyback expansion is intended as liquidity management or amounts to yield suppression remains an open question heading into the September 9 start date, with markets likely to test that distinction each time the department steps in to buy.
Don't forget to follow us @INN_Resource for real-time updates!
Securities Disclosure: I, Giann Liguid, hold no direct investment interest in any company mentioned in this article.
https://x.com/giannliguid
https://www.linkedin.com/in/giannliguid/
Giann Liguid is a graduate of Ateneo De Manila University with an AB in Interdisciplinary Studies. With a diverse writing background, Giann has written content for the security, food and business industries. He also has expertise in both the public and private sectors, having worked in the government specializing in local government units and administrative dynamics.
When he is not chasing the next market headline, Giann can most likely be found thrift shopping for his dogs.
When he is not chasing the next market headline, Giann can most likely be found thrift shopping for his dogs.
INN Article Notification
Latest News
Outlook Reports world
Featured Resource Investing Stocks


Browse Companies
MARKETS
COMMODITIES
CURRENCIES
Giann Liguid is a graduate of Ateneo De Manila University with an AB in Interdisciplinary Studies. With a diverse writing background, Giann has written content for the security, food and business industries. He also has expertise in both the public and private sectors, having worked in the government specializing in local government units and administrative dynamics.
When he is not chasing the next market headline, Giann can most likely be found thrift shopping for his dogs.
Learn about our editorial policies.