• Connect with us
    • Information
      • About Us
      • Contact Us
      • Careers
      • Partnerships
      • Advertise With Us
      • Authors
      • Browse Topics
      • Events
      • Disclaimer
      • Privacy Policy
    • Australia
      North America
      World
    Login
    Investing News NetworkYour trusted source for investing success
    • North America
      Australia
      World
    • My INN
    Videos
    Companies
    Press Releases
    Private Placements
    SUBSCRIBE
    • Reports & Guides
      • Market Outlook Reports
      • Investing Guides
    • Button
    Resource
    • Precious Metals
    • Battery Metals
    • Base Metals
    • Energy
    • Critical Minerals
    Tech
    Life Science
    Precious Metals Market
    Precious Metals News
    Precious Metals Stocks
    • Precious Metals Market
    • Precious Metals News
    • Precious Metals Stocks
    gold investing

    Ryan Walker: Tweet Retreat Hasn’t Changed Gold’s Story

    Written by Investing News Network
    |
    May. 06, 2013 03:15AM PST

    Investors were shaken by the market’s death-defying drop and recovery in a matter of minutes recently. But the “tweet retreat” hasn’t changed the reasons why investors need gold companies in their portfolio. Ryan Walker, a mining analyst with Casimir Capital in Toronto, tells investors to look past the headlines to what underpins the market. In this interview with The Gold Report, Walker says that all that cash pumped into the economy at some point has to start driving inflation.

    Source: Brian Sylvester of The Gold Report (5/3/13)

    Investors were shaken by the market’s death-defying drop and recovery in a matter of minutes recently. But the “tweet retreat” hasn’t changed the reasons why investors need gold companies in their portfolio. Ryan Walker, a mining analyst with Casimir Capital in Toronto, tells investors to look past the headlines to what underpins the market. In this interview with The Gold Report, Walker says that all that cash pumped into the economy at some point has to start driving inflation.

    The Gold Report: Casimir Capital adjusted its metal price forecasts after the recent drop in metals prices. What are your near-term numbers for gold and silver?

    Ryan Walker: For the remainder of this year, we’re forecasting $1,600/ounce ($1,600/oz) gold, then $1,700/oz next year and $1,800/oz for the subsequent two years. Long term, our price assumption is $1,400/oz.

    For silver, we forecast $28/oz for this year, $30/oz next year and $33/oz for the subsequent two years. Our long-term price is $26/oz. Unfortunately, we put these out before the big crash in gold and silver. We missed that event in our forecast.

    TGR: What’s underpinning that bullishness?

    RW: According to some reports, there’s been some $6 trillion in quantitative easing over the past few years. At some point, inflation is in a real way going to kick in. It’s been kept at bay so far, but inflation has got to send gold higher. While mechanisms exist to fight that, it is hard to see inflation not happening at some point. The big question is when, not if. We’re bullish on gold, but we’ve tempered our expectations to reflect the current market.

    TGR: Many precious metals investors are still reeling after that dramatic drop in the price of gold in mid-April. What happened there?

    RW: It was a confluence of events. There were reports Cyprus would be required to sell gold as part of its bailout package. Some members of the Federal Reserve were hinting that it might be time to end or slow down the pace of quantitative easing. A couple of the major banks in the U.S. recommended going short gold. It all came together to spook an already jittery market. Exchange-traded funds are so easily traded that things start to trade through stop losses and cascade and feed on themselves and become a self-fulfilling prophecy.

    As an example of how quickly things can move nowadays, the Dow Jones Industrial Average recently dropped 130 points in the span of about a minute on a false Twitter headline from the Associated Press that there were explosions at the White House. Then it popped right back up to where it was—all in less than five minutes. That’s the kind of world we’re in.

    TGR: Should investors expect similar price shocks in the near and medium term?

    RW: The potential is out there for it. Can you call the kind of thing that happened to the Dow recently? I don’t think so. Have the fundamentals for gold changed? I don’t think so.

    TGR: Did what happened make you more of a conspiracy theorist about gold price manipulation?

    RW: No, but you can definitely see where conspiracy theorists are coming from. Maybe it does make you wonder a little bit longer about some of those theories. But I think it was just the confluence of a number of factors that got things rolling, and then electronic trading just created a cascade effect.

    TGR: Your coverage involves small-cap precious metals, mostly in the developer space. What’s the essential investment thesis for those types of names?

    RW: For the most part, I’m dealing with the explorers, emerging producers and developers. I look for something that’s got potential to get big, an asset that would be attractive as a merger and acquisition (M&A) target. But if that doesn’t happen, I look for something that could feasibly be put into production by a smaller company. With producers you look for the low-cost companies with solid balance sheets, but also companies that have some real legs to them, preferably somewhere in a safe jurisdiction.

    TGR: What’s your preferred valuation metric for junior explorers?

    RW: A lot of people use Enterprise Value per ounce as an initial filter, which is fine for that purpose. Not all ounces are created equal, however. Generally, an ounce of sulphide gold requires more work to recover compared with oxide ounces, where recoveries can be easier and sometimes you don’t need to go and build a big mill. Do you really value both those types of ounces the same way? You have to look at the whole picture—jurisdiction, management deposit type, metallurgy, etc.—there is no one magic bullet.

    TGR: Has the recent dive in precious metals prices put further financing pressures on the explorers?

    RW: Sure, but it is always an issue for them. I like to look for big deposits that can help self-finance, that might have by-product credits that could be sold forward. If a gold deposit has some silver, a company can sell forward the silver to fund the gold part of the deposit.

    TGR: What are three strong narratives in the developer space?

    RW: I like to look for projects that can get big and that have legs, scalability, development options and by-product credits, if possible. A good example and the one I am most excited about right now is Probe Mines Limited (PRB:TSX.V). The company’s Borden Gold deposit in Ontario has had success pretty quickly. It was discovered in late 2010 and it is already up to 4–6 million ounces (4–6 Moz) gold, depending on the cutoff grade you apply.

    Some say these big, low-grade deposits are out of favor right now—that’s quite true—but Probe has a couple of characteristics that help it stand out. The deposit has a higher-grade core that runs right down the middle. The bulk of the deposit is running at around 1 gram per tonne gold (1 g/t). The higher-grade core is up around 1.6 g/t. That gives Probe a bit of flexibility to go after the higher-grade core first and then stockpile the lower-grade material for processing toward the end of the mine life.

    The really exciting thing is that late last year, drilling to extend the deposit toward the southeast returned the type of hole I can’t say I’ve seen in some time—51 meters (51m) of 10.3 g/t. And, that was NOT influenced by, say, a 1m section of 800 g/t—it wasn’t a case of grade smearing. Probe more recently did some follow-up drilling and the first two holes—and mind you this is a 500m stepout from that initial hole—boom! Drill results came back just shy of 13m at 7.4 g/t and another at 10.2m of 12.5 g/t. Those are fantastic results!

    The market shrugged it off on the back of the declining gold price and some warrant overhang holding the stock back. It was ignored wholeheartedly.

    TGR: Explain grade smearing and how investors can identify it.

    RW: I would encourage investors to not just read the headline numbers, but go down and read through press releases and the actual table of drill results. That headline might say 150m at some flashy high-grade number, but more often than not there are smaller subintervals included containing much higher grades, disproportionately influencing the overall average. When they’re averaged, it makes the whole story sound good.

    When I first saw that Probe hole I mentioned earlier, I thought, “That’s crazy! That can’t be.” But the drill result table showed it WASN’T being influenced by a single narrow, very high-grade interval.

    TGR: Those stepout drill results would seem to indicate further exploration potential. How important is that to a potential suitor?

    RW: The deposit has 4–6 Moz, so you know it’s a big plumbing system to be able to pile up that much gold. The bulk-tonnage target and high-grade core have shown good continuity. We’re waiting on results from additional ice-based holes sunk this winter further southeast and they could be the game changers. It looks as if Probe has tapped into a high-grade feeder system toward the southeast. That changes the complexion of the story from bulk-tonnage and low-grade to high-grade, and, importantly, so far over some nice wide intervals. All that, and the company still has a large little-explored land package.

    Probe is worth a look. With $30 million ($30M) on the balance sheet, the company should at least be funded through the end of this year. No jeopardy of running dry on funds.

    TGR: What’s another story you are following?

    RW: Atacama Pacific Gold Corp. (ATM:TSX.V) has a nice large oxide gold deposit in Chile. The processing is much easier. It is an open-pit, heap-leach opportunity with 3.5 Moz in pit. It is low grade at about 0.5 g/t, but the key is its oxide gold.

    Atacama came out with a preliminary economic assessment earlier this year with robust numbers. In the first five years, the company will produce about 300,000 oz gold/year. Its after-tax net asset value is $531M at a 5% discount rate. It has a 26% internal rate of return, which is above the benchmark of around 20% that most companies are looking for in a M&A scenario.

    The key issue for this one is water, because it’s situated in Chile’s Atacama desert. Atacama has drilled some aquifers and hit some water. The initial flow rates look good. Once that gets settled, it should help the story.

    TGR: There are a few majors in the area. Kinross Gold Corp. (K:TSX; KGC:NYSE) has projects nearby, but things aren’t going so well for it right now. Do you see Atacama as a takeover target?

    RW: It’s certainly on the radar screen, but the big hitch is the water. I don’t think it will be touched until that is sorted out.

    TGR: Are the locals on board at its Cerro Maricunga project in Chile?

    RW: There really aren’t any locals to speak of. It’s a pretty remote region that is not agricultural by any means.

    TGR: How much cash does Atacama have?

    RW: At the beginning of the year, the company had $20M. It’s nicely situated to keep going for quite a while. It’s doing in-fill drilling, some engineering studies and metallurgical work.

    TGR: Are any other companies interesting right now?

    RW: Treasury Metals Inc. (TML:TSX) outside of Dryden, Ontario, is one I initiated coverage on recently. I’ve been to a lot of sites over the last 15 years and the infrastructure here couldn’t be better. It’s literally a stone’s throw off the Trans-Canada Highway, a former government tree nursery left several useable buildings on site, and there’s high-capacity hydro-wires crossing near the planned pit area. Also, a natural gas pipeline cuts across the property. You couldn’t ask for a better set-up.

    A lot of people up there looking for jobs would love to see this mine up and running.

    This project doesn’t yet have the size that some deposits have—it is about 1.7 Moz gold equivalent—but it does have some silver. Treasury can’t totally fund the project on the back of the silver, but it could sell the silver stream and reduce the equity portion of the capital expenditure (capex). It is a nice story with very good exploration potential.

    Treasury recently enlarged the land package. It’s done some regional drilling that generated some whiffs of smoke, but no real barn burner of a hole yet.

    The pushback on this one would be the strip ratio, the ratio of waste to ore taken during open-pit mining, which is pretty high. Drilling has been hitting a second, parallel zone. The more it hits that and can flesh that out, it will help reduce the overall strip ratio.

    The deposit has a manageable capex for the open pit at just more than $92M.

    TGR: Is that realistic? I mean $92M sounds really low.

    RW: It’s not a huge operation and it’s got a head start with the infrastructure, so I think it’s a reasonable number. The plan is to get the open pit running and cash flow going, and then fund the underground development out of cash flow. You can make good money off of this and use it as a springboard.

    TGR: We’ve seen some of the bigger players make strategic investments in a number of these smaller companies: Agnico-Eagle Mines Ltd. (AEM:TSX; AEM:NYSE) and Sulliden Gold Corp. (SUE:TSX; SDDDF:OTCQX; SUE:BVL). Does Treasury have any major investors with a significant slice?

    RW: No, it doesn’t. It’s really interesting how Agnico is taking these toe holds at bargain basement prices. It is locking in a 10% stake now—maybe it will miss a little bit on the downside if the gold price goes any lower, but it is locking in these interests and can either consolidate ownership later on or make a nice little profit down the road.

    One that I don’t officially cover but have been keeping an eye on is WCB Resources Ltd. (WCB:TSX.V). This one goes back to looking for something that can get really big. The company has the old Placer Dome Misima mine in Papua New Guinea, which produced about 4 Moz. It is working on putting out a resource estimate by the end of next month. I think we’ll see the 1 Moz mark to start with, but it looks as if that could just be the tip of the iceberg. The deposit has leftover gold that wasn’t produced because gold was at $300/oz back then, so the company just shut it down.

    The real blue-sky here is what’s the underlying heat engine for the gold deposit? The project has some nice large-scale coincident geochemical and geophysical anomalies. It looks as if there’s a big gold-copper porphyry below and some magnetite is associated with it. The magnetite is important because gold-rich porphyry copper deposits can be linked to elevated magnetite content.

    I’m definitely keeping an eye out for the resource estimate—it may catch some people by surprise.

    TGR: Not a bad place to do a site visit either.

    RW: You are in the land of the giants there. Not to sound cliché, but that is elephant country. You’ve got Grasberg, Porgera, Ok Tedi, Lihir and several others—and WBC is right in the trend with those.

    TGR: How does a little company get an asset like this?

    RW: The chief executive officer, Cameron Switzer, has been involved in the project for quite some time, brought it to Pan Pacific Copper Co. Ltd. and they partnered up after Placer Dome left it in the early 2000s.

    TGR: How are the locals with regard to development? The Grasberg district certainly had some problems in the last few years.

    RW: There are no immediate local villages, but the company is still trying to do the right thing by employing locals.

    TGR: The precious metals space is generally quieter in the summer. What should investors expect this year?

    RW: I wish I knew. The plunge heading into summer is an interesting set-up. I don’t expect a massive rebound over the summer; the plunge happened in the blink of an eye, but I don’t expect the recovery to do the same thing. It will be a slow and steady rise back up. Ultimately, I have to believe this massive money printing campaign that’s been going on has got to come home to roost in the form of inflation. That’s got to send gold higher.

    Ryan Walker joined Casimir Capital as a mining equity analyst in October 2012; he previously served in a similar position at Jennings Capital and as a research associate at Wellington West Capital Markets. Prior to that, Walker has seven years of experience reporting on the mining industry for a well-respected trade publication. He holds a masters degree in geology from the University of Windsor.

    For additional comments on Probe Mines Limited, Atacama Pacific Gold Corp., Treasury Metals Inc., Sulliden Gold Corp., and WCB Resources Ltd. from newsletter writers, money managers and analysts, click on their respective links or visit The Gold Report.

    Want to read more Gold Report interviews like this? Sign up for our free e-newsletter, and you’ll learn when new articles have been published. To see a list of recent interviews with industry analysts and commentators, visit our Streetwise Interviews page.

    DISCLOSURE:

    1) Brian Sylvester conducted this interview for The Gold Report and provides services to The Gold Report as an independent contractor. He or his family own shares of the following companies mentioned in this interview: None.

    2) The following companies mentioned in the interview are sponsors of The Gold Report: Probe Mines Ltd. and Sulliden Gold Corp. Streetwise Reports does not accept stock in exchange for its services or as sponsorship payment.

    3) Ryan Walker: I or my family own shares of the following companies mentioned in this interview: None. I personally am or my family is paid by the following companies mentioned in this interview: None. My company has a financial relationship with the following companies mentioned in this interview: None. I was not paid by Streetwise Reports for participating in this interview. Comments and opinions expressed are my own comments and opinions. I had the opportunity to review the interview for accuracy as of the date of the interview and am responsible for the content of the interview.

    4) Interviews are edited for clarity. Streetwise Reports does not make editorial comments or change experts’ statements without their consent.

    5) The interview does not constitute investment advice. Each reader is encouraged to consult with his or her individual financial professional and any action a reader takes as a result of information presented here is his or her own responsibility. By opening this page, each reader accepts and agrees to Streetwise Reports’ terms of use and full legal disclaimer.

    6) From time to time, Streetwise Reports LLC and its directors, officers, employees or members of their families, as well as persons interviewed for articles and interviews on the site, may have a long or short position in securities mentioned and may make purchases and/or sales of those securities in the open market or otherwise.

    Streetwise – The Gold Report is Copyright © 2013 by Streetwise Reports LLC. All rights are reserved. Streetwise Reports LLC hereby grants an unrestricted license to use or disseminate this copyrighted material (i) only in whole (and always including this disclaimer), but (ii) never in part.

    Streetwise Reports LLC does not guarantee the accuracy or thoroughness of the information reported.

    Streetwise Reports LLC receives a fee from companies that are listed on the home page in the In This Issue section. Their sponsor pages may be considered advertising for the purposes of 18 U.S.C. 1734.

    Participating companies provide the logos used in The Gold Report. These logos are trademarks and are the property of the individual companies.

    dow jonescopper depositschiledrill resultscopper porphyrycanadagold investingcasimir capital
    The Conversation (0)

    Go Deeper

    AI Powered
    Canadian Maple Leaf gold coin floating over stacked gold bars with glowing red lights.

    Top 5 Junior Gold Mining Stocks on the TSXV in 2026

    Pile of gold bars over black background.

    5 Best-performing Gold Stocks on the TSX in 2026

    Latest News

    Bold Ventures and Gold X2 Sign Definitive Agreement for Sale of 42 Claim Units at Burchell

    Brixton Metals Announces Closing of First Tranche of Non-Brokered Private Placement

    Mayfair Gold's Fenn-Gib Gold Project Designated Under Ontario's "One Project, One Process" Streamlined Permitting Framework

    New Break Announces $550,000 Non-Brokered Private Placement Offering of Flow-Through Shares

    Sirios Resources Inc. Announces Results of Shareholder Meeting

    More News

    Outlook Reports world

    Resource
    • Precious Metals
      • Gold
      • Silver
    • Battery Metals
      • Lithium
      • Cobalt
      • Graphite
    • Energy
      • Uranium
      • Oil and Gas
    • Base Metals
      • Copper
      • Nickel
      • Zinc
    • Critical Metals
      • Rare Earths
    • Industrial Metals
    • Agriculture
    Tech
      • Artificial Intelligence
      • Cybersecurity
      • Gaming
      • Cleantech
      • Emerging Tech
    Life Science
      • Biotech
      • Cannabis
      • Psychedelics
      • Pharmaceuticals

    Featured Precious Metals Investing Stocks
    OneGold

    OneGold (/GCSPUSD)
    /GCSPUSD

    Heliostar Metals

    Heliostar Metals (HSTR:CC)
    HSTR:CC

    Investor Insight

    Heliostar combines production of ~50,000–55,000 oz in 2026 with a pipeline of high-margin development assets in Mexico led by Ana Paula. Supported by operating cash flow from La Colorada and San Agustin, a debt-free balance sheet and strategic expansion into the US with the Goldstrike project in Utah, the company is positioned to scale into a 500,000 oz per year gold producer.

    Overview

    Heliostar Metals (TSX:HSTR,OTCQX:HSTXF,FRA:RGG1) is an emerging gold producer focused on building a mid-tier, multi-asset production platform, anchored in Mexico and complemented by strategic expansion into the United States.

    Heliostar Metals - open-pit mine

    The company has rapidly transformed from an explorer into a producer through disciplined, value-accretive acquisitions, assembling a 100 percent-owned portfolio of producing mines, advanced development projects and exploration assets. This platform provides both immediate cash flow and long-term scalability.

    In 2025, Heliostar produced 34,098 gold equivalent ounces, generated US$47.4 million in mine operating earnings, and ended the year with US$40.6 million in cash and no debt, demonstrating strong execution and financial discipline.

    Production is expected to increase to 50,000–55,000 oz in 2026, driven by La Colorada and San Agustin. Development of Ana Paula and Cerro del Gallo supports a clear pathway to 500,000 oz annual production by 2030.

    Heliostar Metals portfolio

    In 2026, Heliostar formed part of the OTCQX’s Best 50 top-performing companies. The company ranked 8th overall, joining 7 other mining companies in the top 10.

    Beyond its core Mexican portfolio, the addition of the Goldstrike project in Utah introduces further growth optionality, reinforcing Heliostar’s strategy of acquiring and advancing underexplored assets with strong development potential. With a staged growth strategy, strong margins and an expanding resource base, Heliostar is positioned to evolve into a 500,000 oz per year gold producer by 2030.

    Company Highlights

    • Growing Production Base: Two producing mines targeting 50,000–55,000 oz of gold in 2026, generating cash flow to fund development.
    • Clear Path to Mid-Tier Scale: Staged growth targeting annual production of 500,000 oz by 2030.
    • High-Margin Flagship Asset: The Ana Paula PEA outlines 101,000 oz/year production (post ramp-up) with strong economics, including US$1,012M NPV5% and 51.3% IRR at higher gold price assumptions, supporting a 2028 production target.
    • Self-Funded Growth Model: Generated US$47.4 million in mine operating earnings (2025) with US$40.6 million in cash and zero debt, reducing reliance on equity dilution.
    • Robust Resource Base: Approximately 7.3 Moz measured and indicated gold resources plus ~1.4 Moz inferred, supporting long-term scalability.
    • High-Quality Development Pipeline: Cerro del Gallo targeting 86,000 GEO/year at US$1,390 AISC, alongside San Antonio’s production potential.
    • Strategic Expansion in the US: Acquisition of the Goldstrike project in Utah adds near-surface oxide potential and long-term growth optionality.
    • Strong Institutional Backing: Approximately 53 percent institutional ownership, complemented by high-net-worth investors and management alignment.

    Key Projects

    Ana Paula (Flagship Development Project)

    Heliostar Metals \u200bAna Paula Project

    Ana Paula is a high-grade underground gold project in Guerrero and the cornerstone of Heliostar’s long-term growth strategy.

    The November 2025 PEA outlines a 9 year mine life with 101,000 oz/year production, 874,700 oz total output, and strong economics, including a US$1,012M NPV5% and a 51.3 percent IRR, supported by a low AISC of US$1,011/oz.

    The project hosts approximately 742,000 oz measured and indicated at 5.4 g/t and 514,000 oz inferred, highlighting its high-grade profile and expansion potential.

    Heliostar Metals Guerrero Gold Belt

    With a feasibility study targeted for H1 2027 and construction expected in H2 of the same year, Ana Paula is expected to become the primary driver of Heliostar’s transition to mid-tier production.

    The company is targeting production at Ana Paula in 2028.

    La Colorada Mine

    Heliostar Metals \u200bLa Colorada Mine

    La Colorada in Sonora is a key cash-flowing asset that underwent a successful turnaround in 2025. The mine hosts reserves of 376,000 ounces of gold grading 0.68 g/t in 17.1 million tonnes of ore.

    The mine is expected to produce 20,000–22,300 oz in 2026 at AISC of US$1,775–1,875/oz, supported by a six-year mine life and approximately 286,000 oz total production profile.

    Mining at the project’s Veta Madre pit commenced in August 2026, a milestone that the company ties to its plan to secure cash flow through 2027 and 2028 to support construction at Ana Paula.

    Ongoing drilling, pit expansions and underground potential provide meaningful upside, reinforcing its role as a core funding engine for development.

    Heliostar Metals 2026 Guidance

    San Agustin Mine

    San Agustin in Durango is a restarted oxide heap-leach operation providing near-term production growth and cash flow.

    2026 guidance targets 30,000–32,700 oz of gold at AISC of US$2,150–2,250/oz, following a low-capital restart funded from the company’s balance sheet.

    The asset offers additional upside through oxide expansion and sulphide exploration, supporting potential mine life extension.

    Cerro del Gallo Project

    Cerro del Gallo is a large-scale gold-silver development project in Guanajuato and a key driver of future production growth.

    The 2025 PFS outlines ~86,000 GEO/year over a 15-year mine life at US$1,390 AISC, with strong economics, including US$972 million NPV5% and 59.3 percent IRR at higher gold price assumptions.

    The project is expected to play a central role in advancing Heliostar towards the goal of 500,000 oz annual production by 2030.

    San Antonio Project

    San Antonio is a 100%-owned heap-leach development project offering strong optionality and long-life production potential.

    The project hosts approximately 1.74 million ounces of measured and indicated gold and demonstrates attractive optionality, including potential 80,000 oz/year production and low AISC of US$1,063/oz.

    As permitting advances, San Antonio represents a key medium-term growth opportunity within the portfolio.

    Goldstrike Project (Utah, USA)

    Goldstrike is a newly acquired gold project that expands Heliostar’s footprint in the United States and adds exploration and development optionality. The property currently hosts an Indicated resource of 975 kilo ounces at 0.46 g/t of gold.

    The project hosts a near-surface oxide gold system with historical production of approximately 209,000 ounces of gold and defined mineralization, offering potential for low-cost, open-pit heap-leach development. Its geological setting and existing dataset provide a strong foundation for resource growth and technical advancement.

    Goldstrike complements Heliostar’s acquisition strategy by adding a scalable, underexplored asset outside its core Mexican portfolio, enhancing long-term growth potential.

    Drilling is underway at Goldstrike to test the antimony and gold potential of both Antimony Ridge and Antimony Knoll, with results expected towards the end of 2026.

    Management Team

    Charles Funk – President & CEO

    Charles Funk has over 20 years of experience in exploration and business development, including senior roles at Newcrest Mining and OZ Minerals. He led the Panuco discovery for Vizsla Silver, demonstrating strong capability in identifying high-value deposits. At Heliostar, he has driven the company’s transformation into a multi-asset gold producer through disciplined acquisitions. His leadership is focused on building a scalable, mid-tier gold platform.

    Gregg Bush – Chief Operating Officer (COO)

    Gregg Bush is a proven mine builder with extensive experience in mine development, integration and operations. He previously served as COO of Capstone Mining and held senior leadership roles at Equinox Gold. Bush brings deep expertise in optimizing operating assets and advancing projects into production. He plays a key role in executing Heliostar’s production growth strategy.

    Sam Anderson – VP Projects

    Sam Anderson has approximately 25 years of experience in mine geology and project development, including 17 years at Newmont. He played a key role in advancing the Merian Mine from resource stage through construction to steady-state production. His expertise spans exploration, resource expansion and project execution. At Heliostar, he leads the advancement of key development assets.

    Mike Gingles – VP Corporate Development

    Mike Gingles brings more than 35 years of experience in the mining industry, specializing in corporate development and M&A. He played a leadership role in major transactions including Pueblo Viejo and Turquoise Ridge. His expertise includes project evaluation, deal structuring and strategic partnerships. He supports Heliostar’s acquisition-driven growth strategy.

    Hernan Dorado – VP Sustainability & Special Projects

    Hernan Dorado is a fifth-generation miner with over 20 years of experience in mining operations, particularly in Mexico. He was a founding member of Guanajuato Silver, where he served as COO. His expertise includes permitting, community engagement and sustainability practices. He ensures responsible development across Heliostar’s operations.

    Vitalina Lyssoun – Chief Financial Officer (CFO)

    Vitalina Lyssoun is a Chartered Professional Accountant (CPA, CA) with more than 16 years of experience in financial management within the resource sector. She has extensive expertise in public company reporting, compliance and internal controls. Prior to joining Heliostar, she led the corporate accounting function at Gatos Silver. Her experience spans multiple international jurisdictions.

    Stephen Soock – VP Investor Relations & Development

    Stephen Soock has nearly 20 years of experience across mining operations and capital markets. He began his career in technical roles at mine sites before transitioning to equity research, where he spent eight years covering growth-stage mining companies. He is a mining engineer and CFA Charterholder. At Heliostar, he leads investor relations and supports capital markets strategy.
    Silver Hammer Mining

    Silver Hammer Mining (HAMR:CC)
    HAMR:CC

    Renforth Resources

    Renforth Resources (RFR:CC)
    RFR:CC

    Orosur Mining

    OMI:CC

    GoldInxs Mining

    GoldInxs Mining (INXS:CC)
    INXS:CC

    Investor Insight

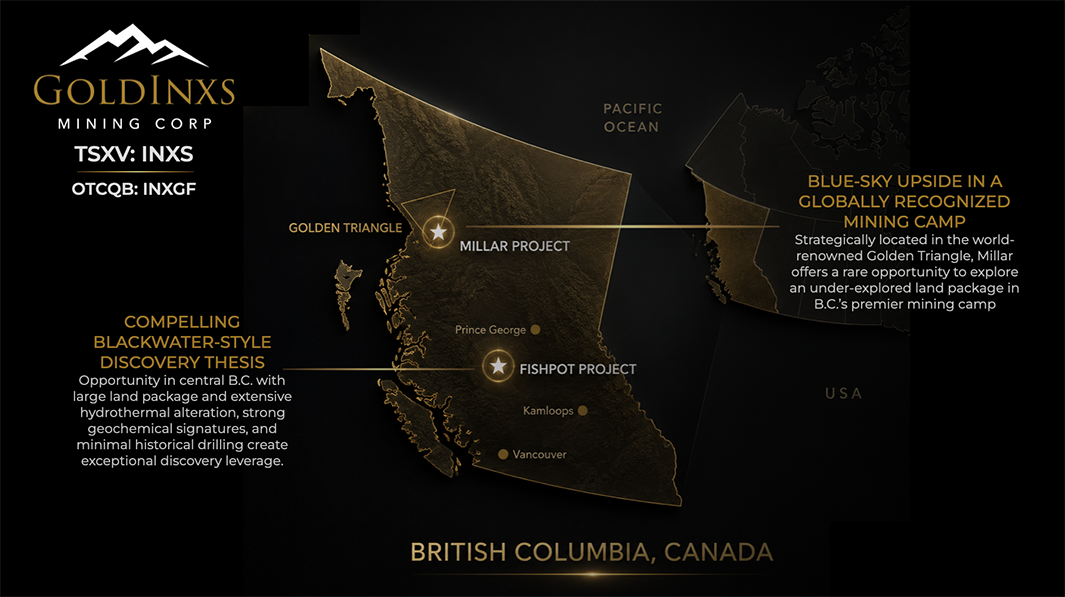
    GoldInxs Mining Corp. (TSXV:INXS, OTCQB: INXGF) provides investors with exposure to early-stage gold-copper exploration in British Columbia, leveraging a portfolio of high-potential projects in Tier 1 jurisdictions, within established gold districts, surrounded by strong regional infrastructure and led by an experienced management team committed to accelerating discovery and delivering shareholder value.
    GoldInxs Mining Corp

    Enjoy the videos and music you love, upload original content, and share it all with friends, family, and the world on YouTube.

    Overview

    GoldInxs Mining Corp. is a discovery-focused mineral exploration company dedicated to identifying and advancing high-potential copper-gold assets in proven geological belts. The Company's strategy centers on acquiring overlooked and underexplored projects with large-scale potential, applying modern exploration techniques to rapidly evaluate targets and unlock shareholder value through discovery.

    The Company’s. common shares started trading on the TSX Venture Exchange in July 2026 under the symbol INXS, positioning itself to capitalize on favorable copper and gold market fundamentals.
    GoldInxs Mining sample rocks

    Copper demand is forecasted to grow steadily through 2030, with the global copper market expected to expand to over US$340 billion by 2030, driven by electric vehicles, renewable energy and infrastructure growth.

    On the other hand, gold continues to provide a safe-haven hedge against policy risks and market volatility, making GoldInxs’ dual focus on copper and gold particularly compelling for investors.

    The Company’s portfolio is anchored by two priority projects: the Fishpot Project in central British Columbia, interpreted as an emerging, large epithermal system with strong infrastructure access and jurisdiction quality as well as early indications of blackwater-style mineralization, and the non-core Millar Project in the prolific B.C Golden Triangle, a district renowned for world-class discoveries. While surrounding deposits attracted billions of dollars in investment, Fishpot received only sporadic historical exploration despite widespread hydrothermal alteration and numerous anomalous gold, silver and copper results. Artemis Gold’s Blackwater Mine has announced tripling production with an intended $1.56B investment, which sits only 65 km from the Fishpot property.

    Backed by a management team with expertise in exploration, project development and capital markets, GoldInxs is positioned to rapidly advance its assets, deliver near-term exploration catalysts and create shareholder value through discovery and strategic growth.

    Company Highlights

    • Mining-friendly jurisdiction: Projects are in British Columbia, which ranked second in Canada and 20th globally in the 2025 Fraser Institute investment attractiveness rankings.
    • Flagship and district-scale assets: Portfolio is anchored by the flagship Fishpot Project (“Fishpot”) in central B.C., showing strong geological indicators of mineralization, blackwater-style mineralization potential and immense exploration upside potential with only 378 meters of historical drilling. Fishpot is strategically located in the same region as Artemis Gold’s Blackwater Mine and Evolution Mining’s optioned Clisbako property.
    • Clear path to 2026 catalysts: GoldInxs secured a drill permit for an upcoming maiden 2,000-metre drill program at Fishpot, near-term exploration programs are designed to define mineralized systems, outline blackwater-style potential and create shareholder value following the completion of a 3D IP survey and drill targeting.

    Key Projects

    Fishpot Project

    GoldInxs Mining Fishpot Project


    Fistpot property

    The Fishpot Project represents the cornerstone asset within the GoldInxs portfolio. Covering up to 5,500 hectares in Central British Columbia, and located ~95 km north of Quesnel, Fishpot hosts a large hydrothermal alteration system that exhibits many of the geological characteristics observed in major epithermal and intrusion-related gold systems throughout the region. Fishpot encompasses five claim blocks, held under an option to acquire 100 percent subject to a 2 percent NSR, representing a significant exploration opportunity in a highly prospective region.

    Fishpot represents a largely untested hydrothermal mineral system where multiple independent exploration datasets, including gold-silver-copper surface geochemistry, alteration and geology, airborne magnetics, 3D IP chargeability/resistivity and identified epithermal-to-potential-porphyry target environments, are converging to define drill targets, despite only 378 metres of historical drilling across two holes.

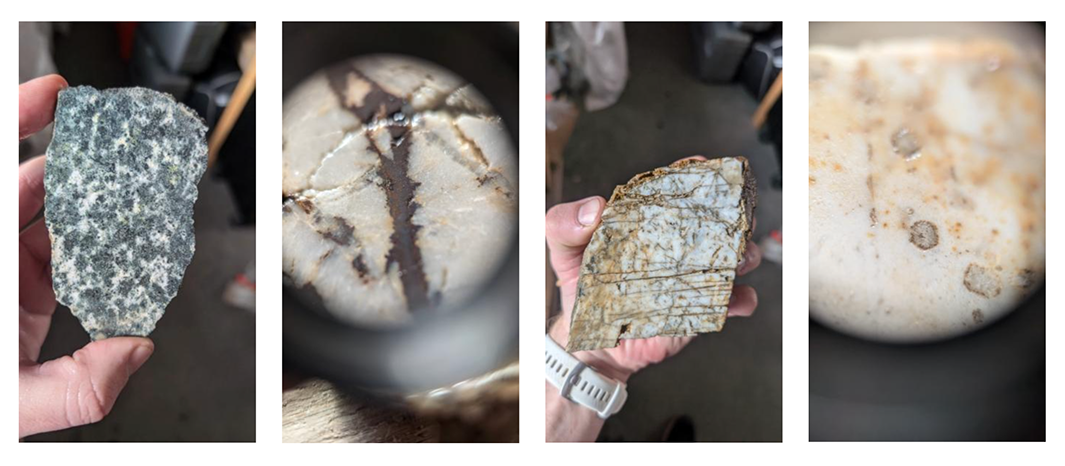
    Fishpot is situated within the highly prospective Stikine Terrane and is underlain by Hazelton Group volcanic rocks and intrusive units comparable to those associated with several significant deposits in British Columbia. Extensive quartz-sericite alteration, hydrothermal brecciation, pyrite mineralization and multi-element geochemical anomalies support the interpretation of a robust mineralizing system. Fishpot is strategically positioned near active and historical mining operations, including Artemis Gold’s Blackwater Deposit, Newton Gold Project, Capoose and 3Ts Project, underscoring its large-scale discovery potential. Importantly, based on early-exploration results, Fishpot shares several regional geological characteristics commonly associated with Blackwater-style gold systems, including felsic volcanics, strong alteration, pyrite-rich mineralization and gold-silver geochemical associations. Despite the similarities the Company cannot yet make any formal connections to the surrounding properties, nor can they guarantee that such deposits exist on their ground.

    Fishpot Exploration Technology: GoldInxs advanced its Fishpot targeting program by combining a conventional 3D IP survey with emerging Virtual DRILL™ remote-sensing technology as an additional targeting layer, using multiple geological, geochemical and geophysical datasets to refine and prioritize targets ahead of a planned ~2,000-metre drill program.

    Fishpot Drill Permit & Expansion: GoldInxs has received the required drilling permits and expanded Fishpot to 5,509 hectares, positioning the Company to proceed with its inaugural ~2,000-metre modern drill program on a property that has seen very limited historical drilling, while refining targets through integrated geological, geochemical and geophysical data.

    Despite multiple encouraging exploration indicators, Fishpot has been subjected to only two historic drill holes totaling 378 metres, leaving the broader mineral system largely untested and providing significant leverage to future exploration success.

    Recent exploration completed by GoldInxs generated the highest reported gold value on Fishpot to date, returning up to 5.65 g/t Au from surface sampling, while airborne geophysical surveys identified multiple coincident magnetic and geochemical anomalies that have strengthened the Company's exploration model and target pipeline.

    The 2025 program returned rock samples of up to 5.65 g/t Au, 11.35 g/t Ag and 0.42% Cu, while historical work reportedly returned up to 4.36 g/t Au and 3.2% Cu.

    The property exhibits the potential low-sulphidation epithermal targets at Fishpot North, intermediate-sulphidation signatures at Fishpot East, and a large central magnetic high being evaluated for potential porphyry mineralization at depth. The Company is focused on finalizing drill targeting and preparing for the inaugural diamond drill campaign at Fishpot in the coming months following completion of the IP survey. GoldInxs is preparing to drill-test a 5,509-hectare, largely undrilled hydrothermal system in central British Columbia where high-grade surface gold-silver-copper results, Blackwater-style geological characteristics and multiple coincident geophysical targets have converged to define a portfolio of high-priority exploration targets.

    Management Team

    Nick Michael – President and CEO

    Mr. Michael is a veteran mining executive and technical director with over 37 years of global experience spanning mine development, engineering and operational leadership. His expertise covers the full project lifecycle, including design, construction, technical due diligence and Independent Engineer assignments for institutional investors and project financiers. He also leads CJK Milling, a company focused on reprocessing historical mine waste to recover discarded gold decades ago, when it was less valuable.

    Carlo Rigillo, CPA, Chief Financial Officer

    Mr. Rigillo is an experienced Chartered Professional Accountant with over two decades of experience. He holds a Bachelor of Commerce from the University of Toronto.

    Barry Miller – Executive Chairman and Director

    Mr. Miller brings over 30 years of experience in public markets, including roles as a broker, consultant and financier. He is the founder of GoldInxs and has been actively involved in the resource sector through leadership positions, including as director of Tinova Resources Corp., an exploration company focused on tin and rare earth elements in British Columbia and Alaska.

    Tara Asfour - Vice President, Corporate Development and Communications

    An executive consultant with over 13 years of experience, Tara Asfour holds expertise in corporate development, capital markets, investor relations and strategic communications. She has led strategic financings, partnerships and offtake initiatives within the resource sector through previous corporate development and investor relations roles with multiple publicly listed companies.

    Al Fabbro – Director

    With over three decades of experience spanning both the mining and finance sectors, Mr. Fabbro previously led Yorkton Securities’ retail trading department and was part of its Natural Resources Group. He later served as Lead Director of Roxgold Inc. and currently holds executive leadership roles in the mining industry.

    Darcy Vis, P.Geo. – VP Exploration and Director

    Mr. Vis is an economic geologist with over 17 years of experience in mineral exploration. He has held senior technical roles across multiple exploration companies and is the President of Tripoint Geological Services Ltd. His expertise includes target generation, project evaluation and exploration program execution.

    Stephen Soock, P.Eng., CFA – Director

    Mr. Soock is a mining professional with nearly 20 years of experience spanning both technical operations and capital markets. He currently serves as Vice President, Investor Relations and Development at Heliostar Metals.

    Christopher Kelly, PQS, FCIArb – Director

    Mr. Kelly has over 15 years of experience in construction and natural resources. He holds a BSc in Construction Economics and Management and an MSc in Construction Law and Dispute Resolution, and runs Trachtala Consulting Ltd.

    More featured stocks

    Browse Companies

    Resource
    • Precious Metals
    • Battery Metals
    • Energy
    • Base Metals
    • Critical Metals
    Tech
    Life Science
    MARKETS
    COMMODITIES
    CURRENCIES