• Connect with us
    • Information
      • About Us
      • Contact Us
      • Careers
      • Partnerships
      • Advertise With Us
      • Authors
      • Browse Topics
      • Events
      • Disclaimer
      • Privacy Policy
    • Australia
      North America
      World
    Login
    Investing News NetworkYour trusted source for investing success
    • North America
      Australia
      World
    • My INN
    Videos
    Companies
    Press Releases
    Private Placements
    SUBSCRIBE
    • Reports & Guides
      • Market Outlook Reports
      • Investing Guides
    • Button
    Resource
    • Precious Metals
    • Battery Metals
    • Base Metals
    • Energy
    • Critical Minerals
    Tech
    Life Science
    Energy Market
    Energy News
    Energy Stocks
    • Energy Market
    • Energy News
    • Energy Stocks
    oil and gas investing

    Potential Oil Glut! Raymond James Analyst’s Contrarian Forecast

    Written by Investing News Network
    |
    Jun. 04, 2013 02:30PM PST

    Stepping away from the pack, Andrew Coleman of Raymond James Equity Research is making a contrarian forecast for an oil glut in 2014. Shale oil production is on the ascent, with the United States joining Saudi Arabia on the supply side, while China’s hunger for oil may be sliding and demand in developed countries remains in decline. In this interview with The Energy Report, Coleman explains his thinking and names the producers best positioned to capitalize on the turbulence ahead.

    Source: Tom Armistead of The Energy Report (6/4/13)

    Stepping away from the pack, Andrew Coleman of Raymond James Equity Research is making a contrarian forecast for an oil glut in 2014. Shale oil production is on the ascent, with the United States joining Saudi Arabia on the supply side, while China’s hunger for oil may be sliding and demand in developed countries remains in decline. In this interview with The Energy Report, Coleman explains his thinking and names the producers best positioned to capitalize on the turbulence ahead.

    The Energy Report: Why are you expecting an oil glut in 2014?

    Andrew Coleman: Because of the evolution of North American shale oil plays, we are on track to add about 3 million barrels (3 MMbbl) of new supply over the next five years. Yet we know oil demand has been falling across the developed nations and is still weak coming out of the global financial crisis. Those developments point toward a glut.

    TER: Saudi Arabia surprised you last year by cutting production when oil was more than $110 per barrel ($110/bbl). Why would Saudi or other suppliers not do that again?

    AC: What hurt production outside the U.S. last year—and helped keep the demand side a little more in balance—was that Saudi cut 800,000 barrels a day (800 Mbbl/d) in Q4/12, sanctions in Iran reduced exports by about 800 Mbbl/d as well, conflict in Sudan took 300 Mbbl/d offline and the North Sea average was lower by about 130 Mbbl/d. These reductions kept last year’s supply more balanced than we thought it would be. Going forward, Saudi’s ability or willingness to cut is certainly going to be tested, because by our model the country may need to cut 1.5 million barrels a day (1.5 MMbbl/d), about double what it cut last year. It would have to do that for a longer period of time, given the amount of excess storage that could show up on the global markets.

    TER: But, as you just pointed out, Saudi Arabia’s cut came in the context of actions by other players. The other players are going to be as unpredictable as they were last year, aren’t they?

    AC: Certainly. That’s a big risk to our call. The other players are very unpredictable as well. I think Saudi has two years of foreign currency reserves at its current spending level. The country doesn’t have a deficit right now, so the question is, would it be willing to tolerate a deficit? Most other countries have deficits, but that doesn’t mean Saudi will. It is hard to predict because we’re dealing with personalities and governments, as opposed to hard numbers. We’re going to keep watching, and we’ll adjust our forecast if some of those scenarios play out.

    TER: Was Saudi Arabia’s production cut driven by a policy change?

    AC: Saudi Arabia cited internal demand issues in its production cut. The cut may also reflect an adjustment to offset the start-up of Manifa, which occurred last month.

    TER: If the glut does occur, which benchmark crudes will be most affected, whether by going up or going down?

    AC: In the U.S., production of light oil will dramatically increase due to the shales. Without the ability to export, we are already seeing prices of West Texas Intermediate (WTI) reflecting that “stranded” lighter barrel. We see light imports being backed out of the U.S. as early as this summer as well. Finally, as infrastructure bottlenecks are removed onshore, we see risk to Gulf Coast prices (e.g., Light Louisiana Sweet). With much of the U.S. refinery infrastructure having been geared to process heavier barrels, the large growth in light barrels has already driven WTI prices to a discount with Brent. Risks to Brent could come down the road if European and Chinese demand remains tepid.

    TER: Will Venezuela’s production decline continue?

    AC: With Nicolas Maduro running things down there now, we see Venezuelan production remaining flat for the next couple of years. Volumes declined each of the past four years.

    TER: What role will other players in the oil space have in either creating or preventing the glut?

    AC: Prior to about 2009, we were in a world where there was one marginal producer of oil (Saudi), and one marginal buyer of oil (China). Now we’re in a world that has two marginal suppliers of oil, those being the U.S. and Saudi. We have not added any new marginal buyers of oil. The question remains, is that marginal buyer of oil—China—as hungry for oil as it has been in the past? We also know that as economies develop, they become less energy-intensive. And, factoring in the potential growth of natural gas consumption, that drives our caution.

    TER: Denbury Resources Inc. (DNR:NYSE) depends heavily on CO2 flood for its production. Will that be economically feasible if a glut occurs?

    AC: Yes. Denbury is profitable in the $50 per barrel ($50/bbl) range. Most of its current production comes from older oilfields that it owns on the Gulf Coast. The company’s CO2 is also on the Gulf Coast—in fact, the company has the only naturally occurring CO2 source outside the Rocky Mountains. And it has the advantage of a pipeline that ties those CO2 assets to its producing fields on the coast. Because the oil is produced next to the infrastructure used to refine it, Denbury doesn’t have to spend a lot of money on transportation, which helps the economics.

    I’m not worried about Denbury being able to economically produce oil because it is cycling CO2, an injection process by which the company puts CO2 in the ground, displacing (and producing) oil as it goes. The company doesn’t have to drill hundreds of wells every year to increase production. All it has to do is get the facilities working and then maintain them, versus continually deploying a lot of new capital in the ground each year.

    TER: CO2 flooding is not necessarily more expensive than drilling brand new wells, is that correct?

    AC: Correct. The two processes present different sets of challenges. If you are going to drill new wells, you need to come up with the drilling rig, well tubulars, hydraulic fracturing fluids and frack sand, and you must build roads and pipelines to connect those wells. If you are going to do a CO2 project, you’ve got to get the CO2, which costs a little bit of money, and you need injection pumps. Much of the initial infrastructure (roads, wells, etc.) is already in place.

    It is a slightly different business model but is still based on extracting additional barrels from historically large accumulations. Finding risk is very low, leaving the bulk of the costs as development in nature only. It’s a business model that you don’t see a lot in the exploration and production (E&P) space. Most players with CO2 assets — the ExxonMobils (XOM:NYSE), the Chevrons (CVX:NYSE), the ConocoPhillips (COP:NYSE) of the world—have those assets embedded in much larger organizations, as part of their core businesses. Most of the E&Ps that we focus on, because of their growth nature, are drilling wells on a continual basis to replenish and add to production.

    TER: With rare exceptions, Denbury has been stalled below $20/share for more than four years. You bumped your target price from $23 to $24 based on your pricing model. If the model says Denbury can reach that level, why hasn’t it done so before?

    AC: A few years ago, the company was bringing on one of its biggest fields, Tinsley. It was the largest project the company had undertaken up to that point and some operational hiccups caused it to miss some production targets. As a result, management initiated a stock buyback program, and added to the technical team by bringing in Craig McPherson from ConocoPhillips.

    Over the last couple of years the company has put more process in place and structured its operations and technical teams to manage its multiple large-scale CO2 floods (aptly titled “Operations Excellence”). Over the last 18 months, management has slowly inched up its tertiary production outlook and now is saying it’s going to come in at the high end of guidance. The guidance has slowly trended up as the company has been able to get more control on the operational side. That is why the stock has risen from where it was a couple of years ago, from $11–12/share to where it is now ($18). To get into the twenties, it would be helpful to have a little bit of oil price support. It would also be helpful to see production growth expectations pick up as the company brings on more of its large-scale fields.

    Management has also been discussing ways of accelerating cash flows from the build-out of its tertiary oil business. The creation of a master limited partnership (MLP) is one way, though management hasn’t decided yet. If you look at how some E&P MLPs are structured, you could make a case in which Denbury would trade from the mid-twenties to the low thirties. My price target reflects continued execution as well as the potential of a little more color on how an MLP might work for the company.

    TER: Do you think converting to an MLP would increase the value of the stock?

    AC: Potentially. Assets with low maintenance capital do well in an MLP. Maintenance capital is the money needed to keep production flat. If you think about the CO2 floods, they might fit nicely because drilling capex is low. Once you get those facilities up and running, then incremental costs involve getting more CO2, as opposed to getting rigs and steel and frack sand, etc.

    While Denbury may not, at this point, grow 40–50% like some of the premier shale players, growing in the 10–15% or maybe 15–20% range could be attractive for an E&P MLP. Investors would have long-term visibility on production growth and the company would be relatively stable, so it could then project the cash flow stream that could be dividended out to investors.

    TER: Energy XXI (EXXI:NASDAQ) has posted disappointing results recently and management has announced a $250 million ($250M) buyback program. What does management hope to accomplish?

    AC: Management is trying to draw attention to the fact that it expects to have free cash from the asset that it produces from, which is not something we’ve seen a lot of companies focus on historically in the E&P business. Most E&P companies are growth companies, with historically high levels of reinvestment of cash flows to fund future growth.

    With Energy XXI recently taking production guidance down to 10% for the next 12 months, it’s going to have a little more capital available to buy back shares. By my model, assuming the oil price is around $95/bbl net, the value of the company’s proved reserves alone is somewhere in the $30/share range. If the company buys back shares for $25/share, that is 15–20% cheaper than what the assets are worth. That gives the company no credit for any future drilling potential, too. Gulf Coast players tend to trade at some of the most conservative multiples in the E&P peer group, but that doesn’t reflect the fact that they generate a lot of cash flow.

    TER: What’s behind the disappointing results?

    AC: The company had some exploration wells that didn’t pan out. That happens when you drill wells with chances of success that are 30% or lower. The offset is when a high-potential well of that magnitude works; it covers the cost of the past unsuccessful tries and then some! If you look at Energy XXI’s capital budget, it has roughly $500–600M of base capital for its base assets. It is going to spend $100–200M on higher-risk, higher-potential exploration stuff. So 15% of its annual program is directed at these high-risk/high-potential wells.

    Over the last two or three years, management spent a lot of money on the Ultra-Deep Shelf (UDS),and it has recently started to balance that by adding exploration drilling around its existing fields. It signed joint ventures with Apache Corp. (APA:NYSE) and ExxonMobil and will test some play concepts that were generated in-house, as well as working with its partners, McMoRan (MMR:NYSE) and Plains Exploration & Production (PXP:NYSE) on the UDS. Freeport McMoRan Copper and Gold Inc. (FCX:NYSE) recently completed its acquisitions of McMoRan Exploration and Plains Exploration.

    The reason Energy XXI missed production numbers was also partly due to lingering weather impacts from last fall’s storm season.

    TER: Energy XXI’s initial strategy was to grow through acquisition, and it did have five large acquisitions, the last one completed in 2010. How well has it performed with the acquired assets?

    AC: The acquired assets are probably 60–70% of the inventory the company can drill now. Getting assets from Exxon, and a couple of years before that from Mit Energy Upstream, Energy XXI was able to high-grade and increase its inventory. Hopefully the company is done integrating the assets, but it’s a continuous process to high-grade a portfolio, drill your best projects and optimize those projects as you go. I look to see that continue. In fact, Energy XXI recently brought its reserve engineering in-house.

    Over the last few years, partly because the company was smaller, it let third party engineers handle 100% of its reserves for year-end reporting. Most larger companies do that in-house, and then use reserve engineers to audit the process for consistency. By bringing the engineering in-house, Energy XXI is trying to show the market that it has a bigger organization—that it has the bigger skill set—and it wants to be more in tune with taking prospect sizes and prospect targets that match its capital program with expectations.

    TER: What is the company’s strategy now? Is it still planning acquisitions or it is going in new directions?

    AC: The strategy continues essentially unchanged. First, it wants to invest in as many high IRR capital projects as it can. The CEO has said that for every dollar invested in the current year, he expects to get $1.50–2.00 in cash flow out of the ground. From that standpoint, the company can continue to spend money to get more returns, but it must balance that with trying to find the next company makers—those bigger projects that support multiple well developments and new platforms.

    For the organic portfolio, the company also has to manage whether it can buy assets that would consolidate parts of its fields in the Gulf of Mexico—and do that at an attractive price. Energy XXI is always looking at acquisitions. It’s always looking at optimizing the drilling program. With the share buyback, the company has tried to put a little more emphasis on the fact that it recognizes the value of cash flow to investors beyond the growth side of the E&P business.

    TER: Bonanza Creek Energy Inc. (BCEI:NYSE) has been a strong performer for you, but its recent earnings report was a miss right across the board. You’ve cut its target price from $41 to $40. What caused that miss?

    AC: Coming out of last year and into Q1/13, Bonanza Creek had a slowdown in activity due to its rig schedule and winter weather. The company is in the right play in the Niobrara oil shale formation, where it is a small-cap player surrounded by Noble Energy Inc. (NBL:NYSE) and Anadarko Petroleum Corp. (APC:NYSE). It was getting its program ramped up in earnest, but the slowdown caused it to come in below expectations for the quarter. In all fairness, at Bonanza’s analyst meeting in April, management discussed the slower start to the year.

    Fundamentally, Bonanza stock still is underleveraged. Its debt is less than current cash flow; it’s going to grow north of 60% this year; it continues to have access to inventory; and it is testing multiple zones to increase its inventory potential. From that standpoint, the stock still looks compelling and still has lots of growth in front of it. That is why I only took the target down by a dollar.

    TER: You make it sound like growth is simply built into the company’s current direction. Does Bonanza not need to improve something in operations to get results?

    AC: Not really. Bonanza Creek’s going to drill 70+ wells this year in the Niobrara. It is testing 5-acre downspacing in the Cotton Valley, it is testing long laterals in the Niobrara B bench and it is testing the Codell zone for the Niobrara as well as the C bench in the Niobrara.

    It doesn’t need to do anything more than continue drilling and hit its targets in terms of ramping the rig count. With four operated rigs presently, the company is doing everything that management said it would do and that allows Bonanza, based on my bottom-up activity model, to hit my $40/share target.

    Additionally, across the play you’ve got the LaSalle Plant, which DCP Midstream Partners, L.P. (DPM:NYSE) is building. The plant should come on line at the end of the summer. That provides additional capacity to enhance volume growth for players in the basin. The Niobrara is a play that works. You’ve got sufficiently large companies in the play to keep capital and facilities growing. Bonanza Creek is falling right in line there, and keeping up with its peers.

    TER: What other companies are you excited about right now?

    AC: My favorite stock is Anadarko. The biggest story for Anadarko will be the resolution of the Tronox Inc. bankruptcy case. After that, the company has numerous operational catalysts on the horizon, including 1) an ongoing process to partially monetize some of its Mozambique gas assets; 2) its Yucatan exploration well (operated by Royal Dutch Shell Plc (RDS.A:NYSE; RDS.B:NYSE) in the deepwater Gulf of Mexico; 3) the sale of its Brazilian assets; and 4) ongoing drilling/testing of its extensive onshore shale inventory (e.g. Niobrara, Eagle Ford, Marcellus and Utica).

    The company has established itself as a premier explorer, and with the Tronox case resolved, Anadarko is also an attractive takeout candidate. In our net asset value (NAV) model, I see its shares as worth up to $130 each, but have assigned a $105 price target given visibility on near-term cash flows.

    TER: Do you have any parting thoughts on the oil and/or gas markets that you’d like to share?

    AC: Yes. From our macro view, we’re cautious about the oil outlook. We’ve got a lot of production, and we’re unclear about the strength of demand on the oil side in the next 6–18 months, going through 2014. On the gas side, after bottoming last year, gas looks like it is poised to be higher down the road, which makes us more constructive there. We have to see more evolution on the demand side, be it in the short term with power plant construction or in the longer term with the quest for use of compressed natural gas as a transportation fuel.

    If the price spread between oil and natural gas remains wide, we’ll see continued evolution toward natural gas use across our economy. That will be good for everybody. It should help unlock value for the manufacturing space. It should also unlock value for consumers, who won’t have to spend quite so much to heat their homes and fuel their cars. It would ultimately kick-start the next big wave of economic expansion on the back of affordable natural gas in the U.S.

    TER: Andrew, thank you for your time.

    AC: My pleasure.

    Andrew Coleman joined Raymond James Equity Research in July 2011 and co-heads the exploration and production team. Since 2004, he has covered the E&P sector for Madison Williams, UBS and FBR Capital Markets. Coleman has also worked for BP Exploration and Unocal in a variety of global roles in petroleum and reservoir engineering, operations, business development and strategy. Coleman holds a bachelor’s degree in petroleum engineering from Texas A&M University and a master’s degree in business administration (finance and accounting) with a specialization in energy finance from the University of Texas at Austin. He is a director for the National Association of Petroleum Investment Analysts and a member of the Texas A&M Petroleum Engineering Industry Board, the Independent Petroleum Association of America’s (IPAA) Capital Markets committee and the Society of Petroleum Engineers (SPE).

    Want to read more Energy Report interviews like this? Sign up for our free e-newsletter, and you’ll learn when new articles have been published. To see a list of recent interviews with industry analysts and commentators, visit our Streetwise Interviews page.

    DISCLOSURE:

    1) Tom Armistead conducted this interview for The Energy Report and provides services to The Energy Report as an independent contractor. He or his family own shares of the following companies mentioned in this interview: None.

    2) The following companies mentioned in the interview are sponsors of The Energy Report: Energy XXI and Royal Dutch Shell Plc. Streetwise Reports does not accept stock in exchange for its services or as sponsorship payment.

    3) Andrew Coleman: I or my family own shares of the following companies mentioned in this interview: None. I personally am or my family is paid by the following companies mentioned in this interview: None. My company has a financial relationship with the following companies mentioned in this interview: Raymond James & Associates lead-managed a follow-on offering of Bonanza Creek Energy Inc. shares within the past 12 months. Raymond James & Associates makes a market in shares of Energy XXI. I was not paid by Streetwise Reports for participating in this interview. Comments and opinions expressed are my own comments and opinions. I had the opportunity to review the interview for accuracy as of the date of the interview and am responsible for the content of the interview.

    4) Interviews are edited for clarity. Streetwise Reports does not make editorial comments or change experts’ statements without their consent.

    5) The interview does not constitute investment advice. Each reader is encouraged to consult with his or her individual financial professional and any action a reader takes as a result of information presented here is his or her own responsibility. By opening this page, each reader accepts and agrees to Streetwise Reports’ terms of use and full legal disclaimer.

    6) From time to time, Streetwise Reports LLC and its directors, officers, employees or members of their families, as well as persons interviewed for articles and interviews on the site, may have a long or short position in securities mentioned and may make purchases and/or sales of those securities in the open market or otherwise.

    Streetwise – The Energy Report is Copyright © 2013 by Streetwise Reports LLC. All rights are reserved. Streetwise Reports LLC hereby grants an unrestricted license to use or disseminate this copyrighted material (i) only in whole (and always including this disclaimer), but (ii) never in part.

    Streetwise Reports LLC does not guarantee the accuracy or thoroughness of the information reported.

    Streetwise Reports LLC receives a fee from companies that are listed on the home page in the In This Issue section. Their sponsor pages may be considered advertising for the purposes of 18 U.S.C. 1734.

    Participating companies provide the logos used in The Energy Report. These logos are trademarks and are the property of the individual companies.

    oil and gas investingjoint ventureschinabusiness developmentfbr capital markets
    The Conversation (0)

    Go Deeper

    AI Powered
    Blue oil barrels and pumpjacks over a digital world map with financial graph lines in the background.

    Oil and Gas Price Trends: Q3 2026 Review and Forecast

    Silhouette of drilling rigs and oil derricks with Canadian flag in background.

    5 Best-performing Canadian Oil and Gas Stocks in 2026

    Latest News

    Aetherion to Issue Q3 2026 Financial Results on November 12, 2026

    Alvopetro Announces Timing of Q3 2026 Results and Earnings Call

    Metals.io Launches Copper, Unlocking Access to the Critical Metal at the Heart of Electrification

    SAGA Metals Positions Wolverine Heavy REE Project Alongside Strange Lake and Tanbreez in Geological Peer Comparison

    Standard Uranium Confirms Strong Radioactivity up to 48,000 cps at Surface and Discovers New Showings at the Corvo Uranium Project

    More News

    Outlook Reports world

    Resource
    • Precious Metals
      • Gold
      • Silver
    • Battery Metals
      • Lithium
      • Cobalt
      • Graphite
    • Energy
      • Uranium
      • Oil and Gas
    • Base Metals
      • Copper
      • Nickel
      • Zinc
    • Critical Metals
      • Rare Earths
    • Industrial Metals
    • Agriculture
    Tech
      • Artificial Intelligence
      • Cybersecurity
      • Gaming
      • Cleantech
      • Emerging Tech
    Life Science
      • Biotech
      • Cannabis
      • Psychedelics
      • Pharmaceuticals

    Featured Energy Investing Stocks

    Coelacanth Energy

    Coelacanth Energy (CEI:CC)
    CEI:CC

    Investor Insight

    Coelacanth Energy is a pure-play Montney oil and natural gas company advancing one of the largest contiguous land positions in the Montney light oil window of northeastern British Columbia. Supported by a substantial discovered and undiscovered hydrocarbon resource base, growing production, established infrastructure and a management team that has built and sold six successful energy companies, Coelacanth is executing a strategy focused on increasing both near-term cash flow and long-term resource value.

    Coelacanth currently producing approximately 8,000 boe/d in Canada

    Overview

    Coelacanth Energy (TSXV:CEI) is a Canadian oil and natural gas exploration and development company focused on the Montney Formation in northeastern British Columbia. The company controls over 150 contiguous sections in the Two Rivers region, a strategically positioned acreage block within the Montney light oil window. As one of the largest landholders in this highly prospective area, Coelacanth has assembled a large-scale resource platform with significant development potential.
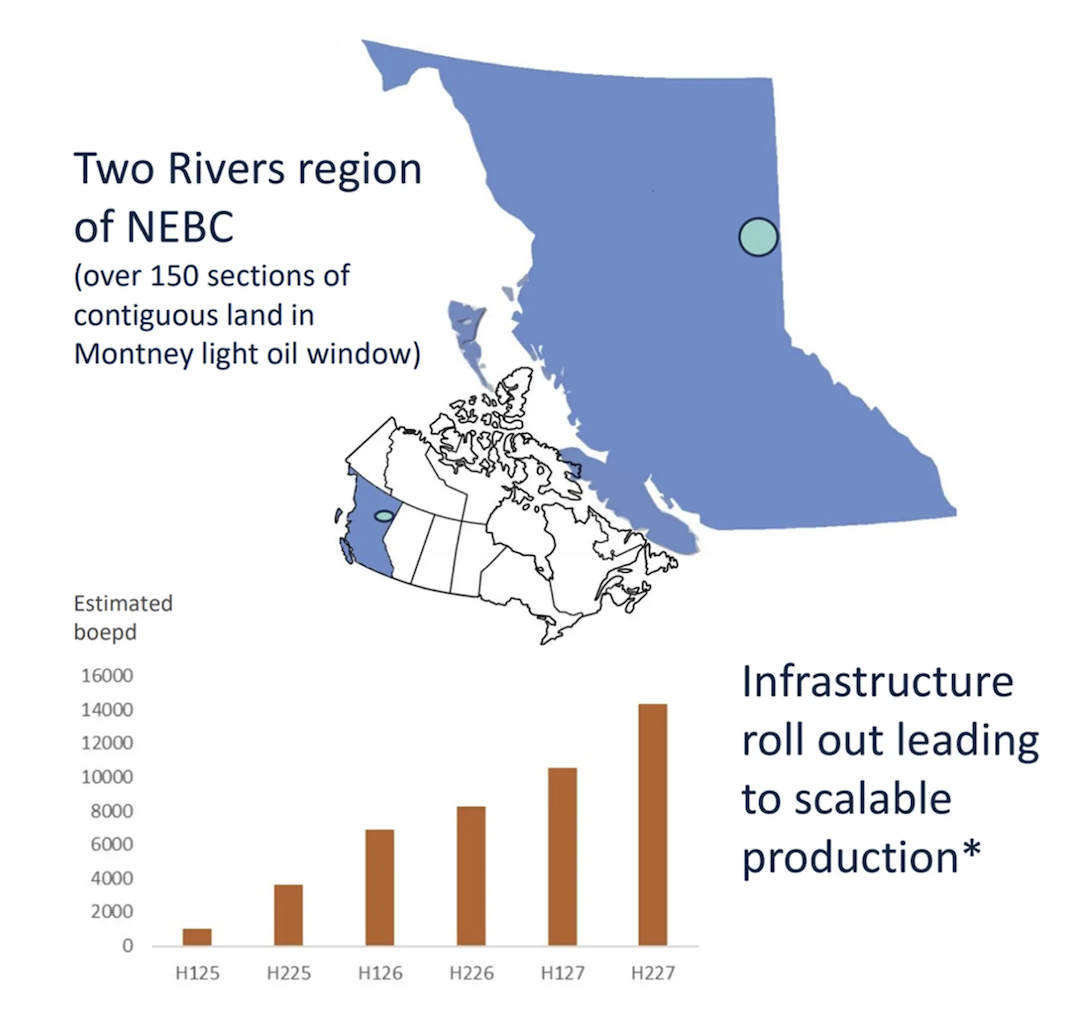
    Map of NEBC with two graphs and text detailing Coelacanth Energy's oil production projections and infrastructure.

    The company’s asset base is supported by substantial petroleum initially-in-place estimates prepared by GLJ. These include 6.9 billion barrels of discovered oil PIIP and 8.3 billion barrels of undiscovered oil PIIP, alongside 5.9 Tcf of discovered gas PIIP and 7.1 Tcf of undiscovered gas PIIP. The resource spans multiple Montney intervals, including the Upper, Lower, Basal and Middle Montney, providing extensive opportunities for future development and delineation.

    Coelacanth’s strategy combines near-term production growth with long-term resource value creation. The company has secured critical infrastructure, contracted gas takeaway and processing capacity, and advanced development activities across its Two Rivers assets. Average production reached 7,632 boe/d in Q2 2026, reflecting continued progress in transitioning from delineation and infrastructure buildout toward scalable production growth.
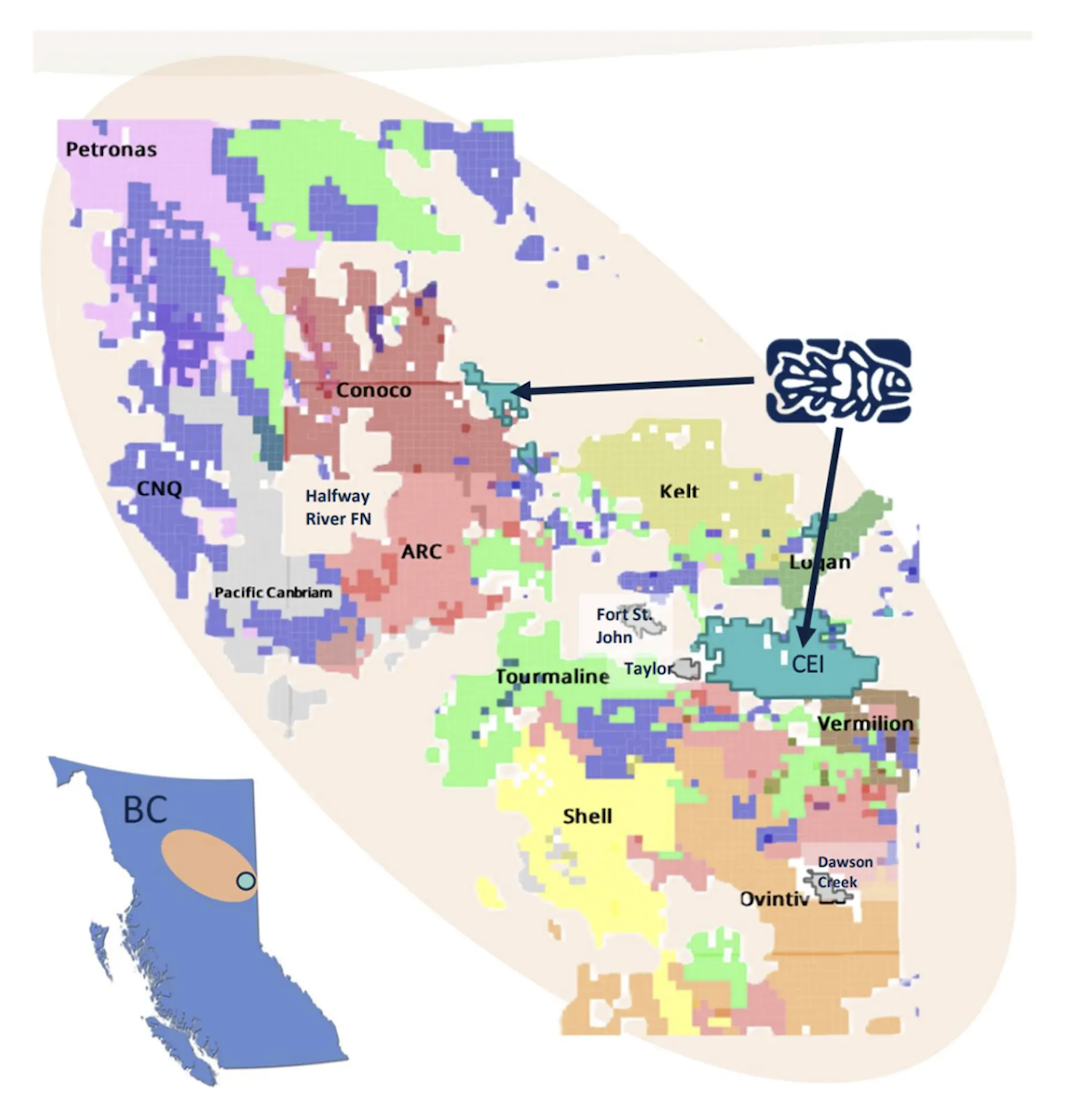
    Colorful regional map of British Columbia with Coelacanth Energy's projects

    A key differentiator for Coelacanth is its leadership team. Management has successfully built and sold six previous public energy companies and has demonstrated an ability to create value through multiple commodity cycles. Supported by deep operational, geological and financial expertise, the team is focused on disciplined execution of the company’s Montney growth strategy.

    Company Highlights

    • Premier Montney land position: Controls over 150 contiguous sections in the Two Rivers region of northeastern British Columbia, making Coelacanth the largest landholder in the Montney light oil window.
    • Substantial hydrocarbons in place: GLJ estimates 6.9 billion barrels of discovered oil PIIP, 8.3 billion barrels of undiscovered oil PIIP, 5.9 Tcf of discovered gas PIIP, and 7.1 Tcf of undiscovered gas PIIP across the company’s Montney acreage.
    • Infrastructure-led growth strategy: Key infrastructure, including facilities, pipelines, processing agreements and gas takeaway capacity, has been secured to support scalable production growth.
    • Growing production base: Average production reached 7,632 boe/d in Q2 2026, supported by ongoing development at the Two Rivers project.
    • Multiple productive Montney horizons: The asset base includes the Upper, Lower, Basal and Middle Montney intervals, providing extensive development opportunities across multiple zones.
    • Strong market access: Secured 100 mmcf/d of gas takeaway capacity and up to 60 mmcf/d of processing capacity, with access to major pipeline networks and potential LNG Canada connectivity through Coastal GasLink.
    • Proven value-creation team: Management has built and sold six successful energy companies and brings extensive operational, technical and financial expertise to Coelacanth’s development strategy.

    Key Project

    Two Rivers Montney Development
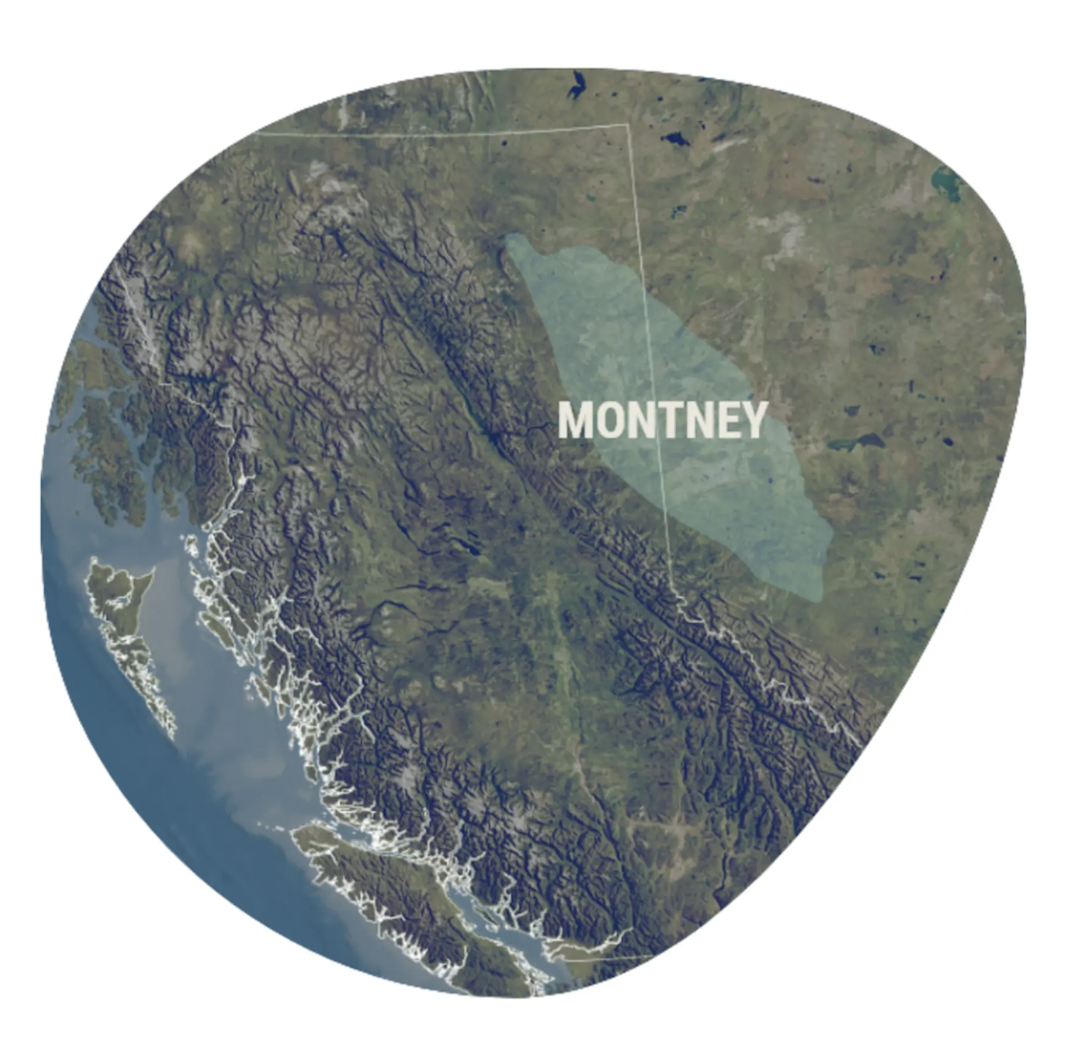
    Aerial view of North America's landscape highlighting Coelacanth Energy's Two Rivers Montney development

    The Two Rivers project forms the cornerstone of Coelacanth’s growth strategy and encompasses the company’s extensive Montney land position in northeastern British Columbia. The project hosts multiple productive horizons, including the Upper, Lower, Basal and Middle Montney intervals, supporting a multi-zone development approach across the acreage. Geological delineation has been completed, providing a strong technical foundation for future drilling and development.

    The project has demonstrated commercial productivity through successful drilling and testing programs. Coelacanth established proof of commerciality at both Two Rivers East and Two Rivers West, while development at the 5-19 and 10-08 pads confirmed productivity across multiple Montney benches. All 12 wells on the 5-19 pad were onstream by April 1, 2026, marking a significant milestone in the project’s progression.
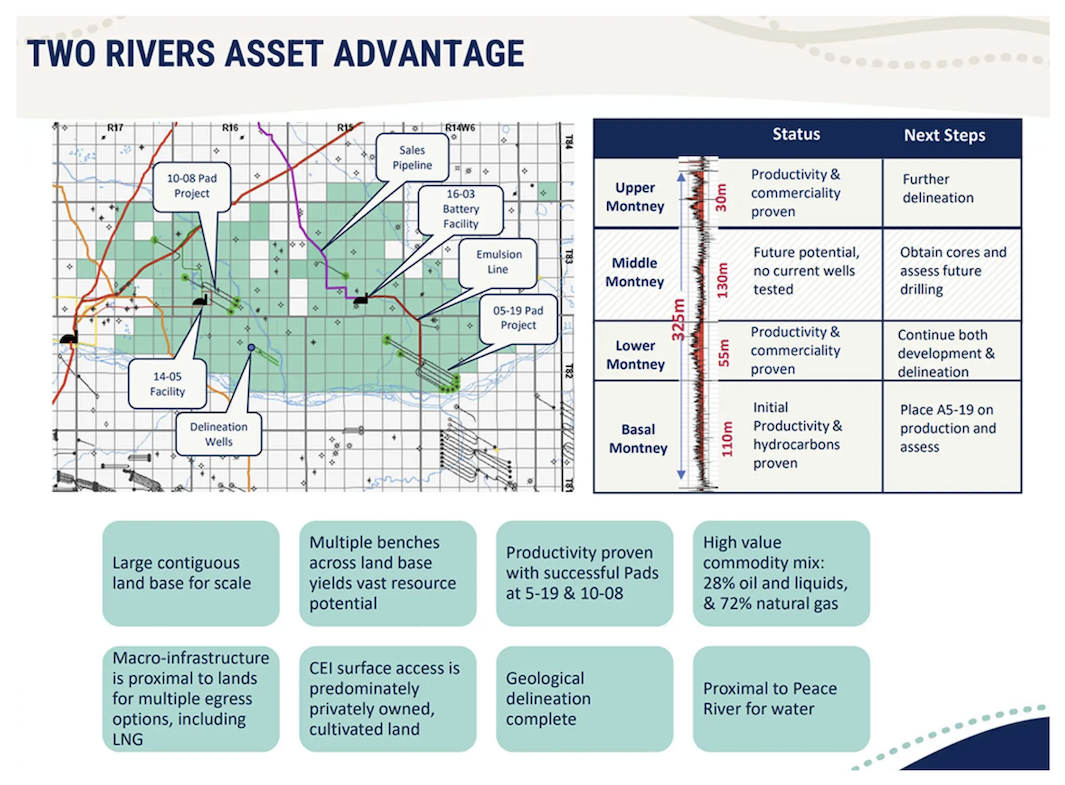
    Map with labeled facilities showing Coelacanth Energy Two Rivers asset advantage

    Infrastructure development has been a major focus of the company’s execution strategy. Coelacanth has secured infrastructure financing, completed key facility and pipeline construction, contracted up to 100 mmcf/d of gas takeaway capacity and secured processing capacity of up to 60 mmcf/d. These initiatives establish the infrastructure foundation required to support future production growth.

    The Two Rivers asset also benefits from strong market access. The company’s production can access major regional pipeline systems, including NGTL, Westcoast and Alliance, while its acreage is directly connected to LNG Canada through the Coastal GasLink system for potential future delivery. Coelacanth Energy said the long-term view for LNG expansion in British Columbia is very positive for its land, believing that lands with scale and direct access as such will trade at a premium once they are delineated and the resource is proven for development.

    Combined with a commodity mix of approximately 31 percent oil and liquids and 72 percent natural gas, the project offers exposure to multiple energy markets.

    Management Team

    Rob Zakresky – President, CEO and Director

    Rob Zakresky is a veteran energy executive who previously served as president and CEO of Leucrotta Exploration, Crocotta Energy, Chamaelo Exploration, Chamaelo Energy, Viracocha Energy and Bellator Exploration. He has a proven track record of building and monetizing public energy companies and leads Coelacanth’s strategic growth and value creation initiatives.

    Nolan Chicoine – Vice President of Finance and CFO

    Nolan Chicoine previously served as CFO and vice-president finance at Leucrotta Exploration, Crocotta Energy and Chamaelo Exploration, and was controller at Chamaelo Energy and Viracocha Energy. He is responsible for financial strategy, reporting and capital management.

    Jody Denis – Vice President of Operations

    Jody Denis is a former drilling, engineering and operations engineer at Leucrotta Exploration. His previous experience also includes senior operational and drilling leadership roles with Black Swan Energy, ARC Resources and Birchcliff Energy. He formerly led Coelacanth Energy’s drilling and completions activities.

    John Fur – Vice President of Geosciences

    John Fur previously served as manager of exploration at Leucrotta Exploration and held senior geophysical positions with Crocotta Energy, Chamaelo Energy, Viracocha Energy, Canadian Natural Resources, Post Energy, Amber Energy and Husky Oil. He oversees geological evaluation and resource delineation across the company’s Montney assets.

    Jonathon Hanson — Vice President of Engineering

    Jonathon Hanson has 20 years of industry experience. He previously served as manager for exploitation at Spartan Dela Corp, and was a senior exploitation engineer for companies Vermilion Energy, Lynx Energy and Saguaro Resources. He will focus on exploitation and reservoir management for Coelacanth Energy.
    Kinetiko Energy

    Kinetiko Energy (KKO:AU)
    KKO:AU

    Syntholene Energy

    Syntholene Energy (ESAF:CC)
    ESAF:CC

    Investor Insight

    Syntholene Energy is advancing a proprietary synthetic fuel production platform designed to produce high-performance, low-cost synthetic hydrocarbons using renewable electricity, geothermal heat and captured carbon. Following successful prototype-scale validation in 2022, the company is now operating its Iceland demonstration facility as it plans commercial-scale production capable of serving aviation, transportation, industrial energy and other hard-to-abate fuel markets.

    Overview

    Syntholene Energy ((TSXV:ESAF,FSE:3DD0, OTC:SYNTF) is a synthetic fuel production company company focused on developing high-performance, low-cost synthetic liquid fuels. The company is commercializing its proprietary Hybrid Thermal Production System, which combines renewable electricity, geothermal heat, water and captured carbon to produce synthetic hydrocarbons that can serve as direct replacements for conventional petroleum-derived fuels.
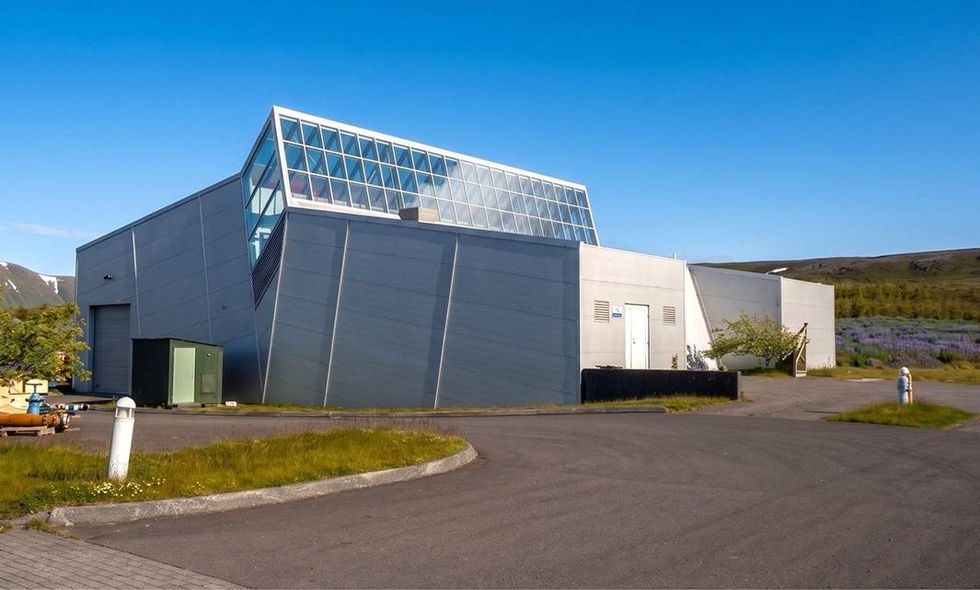
    Syntholene's \u200bH\u00fasav\u00edk Power Station

    Unlike many alternative energy solutions that require extensive changes to existing infrastructure, synthetic fuels can be transported, stored and utilized through today’s fuel supply chains. The resulting fuels are molecularly pure, free from many contaminants associated with conventional fuels and compatible with existing engines, turbines, storage systems and transportation infrastructure. Produced using renewable electricity, hydrogen and captured carbon, the fuels can deliver over 90 percent lower lifecycle emissions while maintaining the energy density and performance characteristics required across multiple industries.

    At the core of the company’s platform is its Hybrid Thermal Production System, which combines high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors. By incorporating low-cost thermal energy into critical production stages, Syntholene seeks to reduce electricity consumption, the largest cost component for most eFuel producers. This approach underpins the company’s targeted 70 percent cost advantage relative to competing technologies and supports its objective of producing cost-competitive synthetic fuels at commercial scale.
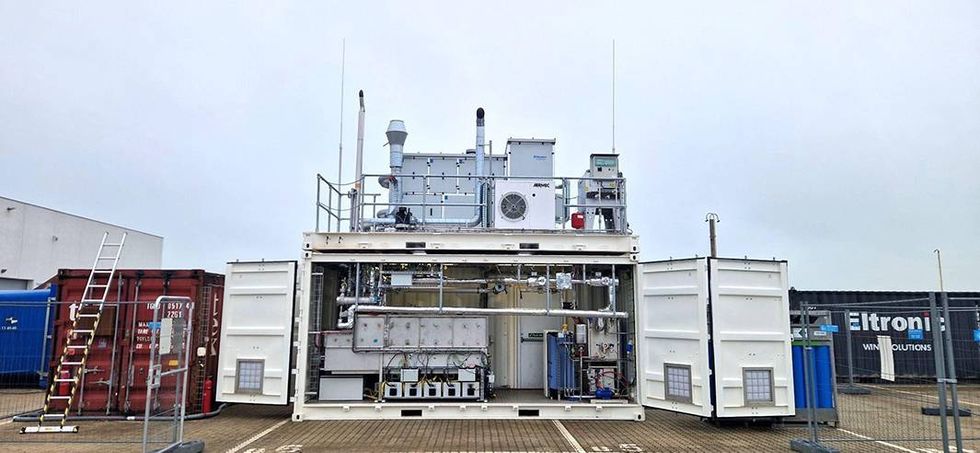
    Syntholene Hybrid Thermal Production System

    The technology builds upon advancements in high-temperature electrolysis, including work undertaken at Idaho National Laboratory. Following successful prototype-scale validation in 2022, Syntholene is progressing toward field-scale demonstration in Iceland. The company believes a successful demonstration will support future commercial deployment across a range of synthetic fuel applications.

    Market demand for low-emission liquid fuels continues to expand across multiple sectors. Sustainable aviation fuel represents Syntholene’s initial commercial focus, supported by increasing airline decarbonization commitments, regulatory mandates, and fuel-blending requirements. Beyond aviation, the broader global eFuel market is projected to grow from US$8.89 billion in 2024 to more than US$215 billion by 2032, creating opportunities across transportation, shipping, industrial energy, and other sectors that depend on liquid hydrocarbon fuels.

    Syntholene’s leadership team combines expertise across climate technology, synthetic fuels, industrial engineering, energy infrastructure, project development and resource industries. Recent additions to the advisory board, including former Shell and Suncor executive Marc Mageau and energy industry veteran HY Lee, further strengthen the company’s capabilities as it advances toward commercialization.

    Company Highlights

    • Addressing a multi-layered growth opportunity: The company is initially targeting sustainable aviation fuel while developing a technology platform capable of serving a substantially larger global liquid fuels market spanning transportation, industrial energy and other hard-to-electrify sectors.
    • Proprietary hybrid thermal production system: Syntholene’s technology integrates high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors, utilizing both electricity and thermal energy to improve efficiency and reduce production costs.
    • Targeting a 70 percent cost advantage: By introducing low-cost thermal energy into critical stages of production, the company aims to produce synthetic fuels at 70 percent lower cost than competing eFuel technologies.
    • Pathway to cost-competitive synthetic fuels: The company believes its technology provides a credible pathway toward producing synthetic fuels that can compete economically with conventional petroleum-derived fuels at scale.
    • High-performance fuel characteristics: Synthetic fuels are molecularly pure and free from many contaminants associated with conventional fuels, including sulfur, nitrogen and heavy metals, while remaining compatible with existing infrastructure.
    • Over 90 percent lower lifecycle emissions: Synthetic fuels produced from renewable electricity, hydrogen and captured carbon can deliver over 90 percent lower lifecycle emissions than conventional alternatives.
    • Prototype validation completed: The company’s production process was successfully demonstrated at prototype scale in 2022 and is now operating a world-first geothermally-integrated demonstration facility in Husavik, Iceland.
    • Demonstration facility advancing ahead of schedule: The Húsavík, Iceland facility is now operating, with efficiency and technoeconomic results expected in Q4 2026.
    • Strategic geothermal platform: The Iceland project benefits from low-cost geothermal electricity, thermal energy, industrial infrastructure, deep-water port access and an existing 200 MW+ regional grid expansion permitting framework.
    • Scalable commercial development strategy: Following demonstration, the company intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts.

    Flagship Project

    Húsavík Demonstration Facility, Iceland
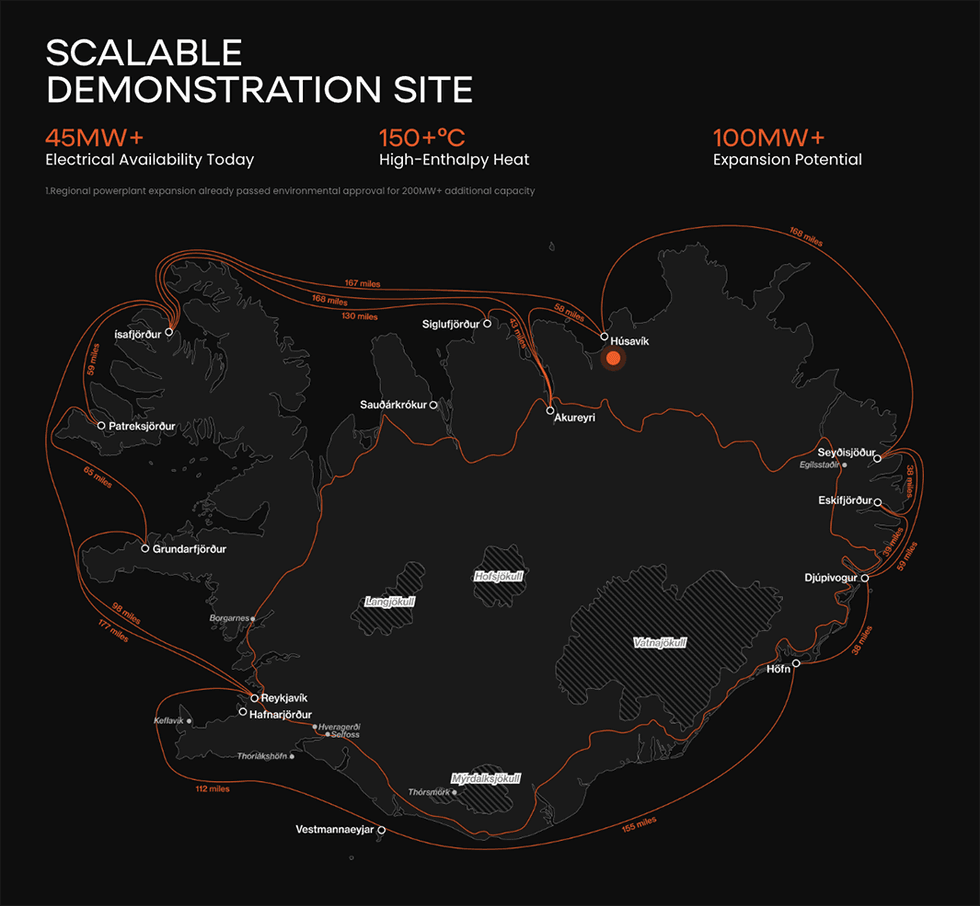
    Syntholene \u200bH\u00fasav\u00edk Demonstration Facility, Iceland

    Syntholene’s flagship project is its geothermal-integrated demonstration facility located in Húsavík, northern Iceland. The facility is designed to validate the integration of geothermal heat, high-temperature solid oxide electrolysis and synthetic fuel production technologies under real-world operating conditions. Construction has advanced six months ahead of schedule, with first operations initiated on June 22nd 20266 and efficiency and technoeconomic results expected in Q4 2026.

    The project leverages northern Iceland’s abundant geothermal resources, providing access to both low-cost electricity and high-temperature steam. Unlike intermittent renewable energy sources, geothermal energy offers reliable baseload power and thermal energy that can be utilized continuously throughout the fuel production process. The location also benefits from established industrial infrastructure, a skilled workforce, proximity to a deep-water port and a favorable regulatory environment.
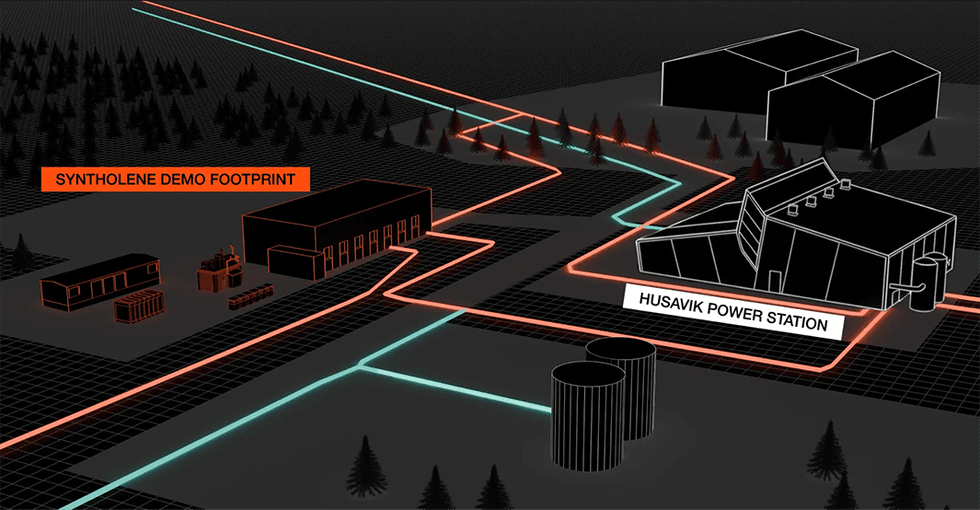
    Syntholene Demo Footprint

    A key objective of the demonstration facility is to validate the company’s thermal integration strategy and confirm that efficiencies achieved during laboratory and prototype testing can be replicated under commercial operating conditions. The facility incorporates Syntholene’s proprietary Thermal Coupling technology, which converts geothermal steam into high-purity industrial steam suitable for use throughout the fuel production process. Management believes this technology is central to achieving the targeted 70 percent cost advantage relative to competing synthetic fuel pathways.

    The project also benefits from significant expansion potential. Iceland has completed environmental permitting associated with a 200 MW regional grid expansion, supporting future industrial development in the region. Following a successful demonstration, Syntholene intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts. Management believes the Húsavík location alone has the potential to support development capable of generating approximately US$500 million in annual revenue.

    Management Team

    Dan Sutton – Chief Executive Officer

    Dan Sutton has spent the last 15 years founding and leading sustainable infrastructure businesses. As founder and CEO of Tantalus Labs, he designed, built and operated SUNLAB, scaled the company to 150 employees and grew annual revenue to approximately US$20 million. His expertise spans infrastructure deployment, project development, government relations, public markets and executive leadership.

    Steve Oldham – Director

    Steve Oldham is a globally recognized leader in carbon management and climate technology commercialization. As former CEO of Carbon Engineering, he helped establish direct air capture as a commercial industry and led the company through its acquisition by Occidental Petroleum at a US$1.6 billion valuation. He currently serves as CEO of Captura.

    Canon Bryan – Director

    Canon Bryan is a founder and company builder with more than 25 years of experience across advanced energy and resource development. He co-founded Terrestrial Energy, Uranium Energy and NioCorp and brings expertise in finance, corporate development, economic modelling and strategic planning.

    John Kutsch – Chief Engineer

    John Kutsch leads the integration and optimization of Syntholene’s fuel production platform. He brings more than 30 years of experience across industrial systems design, chemical processing, advanced energy technologies and reactor development, including work supporting high-temperature synthetic fuel systems.

    Jack Williams – Head Engineer

    Jack Williams specializes in high-temperature and high-pressure reactor systems and synthetic fuel technologies. His research at the University of Cambridge focused on electrolysis systems, catalytic reactor design, CO₂ capture and synthetic fuel production processes.

    Grant Tanaka – Chief Financial Officer

    Grant Tanaka has more than 15 years of senior financial leadership experience across the global natural resources sector. His background includes senior finance roles at Teck Resources, New Gold and Copper Mountain Mining, combining financial discipline with operational performance management. He was also appointed Corporate Secretary in May 2026.

    Anna Pagliaro – Director

    Anna Pagliaro is a senior commercial and risk management executive with extensive experience across the energy and mining sectors. Her career includes leadership positions at Vizsla Silver, Ausenco, NexGen Energy and Integra Gold, where she focused on governance, commercial strategy, negotiations and risk management.

    Marc Mageau – Advisory Board Member

    Marc Mageau joined the Advisory Board in June 2026. He brings more than three decades of operational leadership experience from Shell and Suncor, including expertise in refining, oil sands operations, logistics, infrastructure development and industrial asset management.

    HY Lee – Advisory Board Member

    HY Lee joined the Advisory Board in May 2026, adding further industrial, operational and strategic expertise as Syntholene advances toward commercial deployment of its synthetic fuel platform.
    Quebec Innovative Materials

    QIMC:CC

    Alvopetro Energy

    Alvopetro Energy (ALV:CC)
    ALV:CC

    Valeura Energy

    Valeura Energy (VLE:CC)
    VLE:CC
    More featured stocks

    Browse Companies

    Resource
    • Precious Metals
    • Battery Metals
    • Energy
    • Base Metals
    • Critical Metals
    Tech
    Life Science
    MARKETS
    COMMODITIES
    CURRENCIES