Understanding asset values is the name of the game for early-stage resource plays—that’s how investors in the Bakken made huge returns. But with the first round of shale plays largely maturing, where are the next big opportunities for junior explorers? In many cases, abroad, says James West, publisher of The Midas Letter. In this interview with The Energy Report, West rolls out the map and shows us where juniors are headed. He also names some companies who are thriving on North American soil. If boots-on-the-ground prospecting puts a glint in your eye, read on.
Source: Peter Byrne of The Energy Report (7/2/13)
Understanding asset values is the name of the game for early-stage resource plays—that’s how investors in the Bakken made huge returns. But with the first round of shale plays largely maturing, where are the next big opportunities for junior explorers? In many cases, abroad, says James West, publisher of The Midas Letter. In this interview with The Energy Report, West rolls out the map and shows us where juniors are headed. He also names some companies who are thriving on North American soil. If boots-on-the-ground prospecting puts a glint in your eye, read on.
The Energy Report: What are the key considerations investors should make in evaluating geographical location and political risk in junior exploration and development plays?
James West: Outside of North America, there are a few obvious no-go zones—Russia, China and parts of war-torn Africa. Then again, we did see a great junior success in Kenya with Africa Oil Corp. (AOI:TSX.V), so certain regions in Africa are less risky. Presently in Kenya, I’m watching the progress of Africa Hydrocarbons Inc. (NFK:TSX.V) with interest as the company seeks to emulate Africa Oil’s success. Africa Hydrocarbons commenced drilling on its 47.5%-owned Bouhajla Block, located onshore in Tunisia within the productive Pelagian Basin.
Australia carries little or no political risk of expropriation. Terra Nova Energy Ltd. (TGC:TSX.V; TNVMF:OTCPK; GLTN:FSE) is drilling in the Cooper Basin in Australia. Initial production wells that BeacChevron Corp. (CVX:NYSE) drilled in that basin are pumping 2,000 barrels per day (Mbbl/d). And investors will do well to concentrate on Canada and the United States—there is just so much profitable activity going on in the shale space and in legacy wells and oil field redevelopment.
It’s actually Beach Energy Ltd. (BPT:ASX) that made the initial discoveries in the Cooper Basin, and is now flowing in excess of 10,000 barrels oil equivalent per day (boe/d). Chevron has farmed into two exploration permits owned by Beach Energy, but is a minority holder and non-operator.
TER: Are there any places where the political risk outweighs any potential payoffs?
JW: If a government is already inclined toward resource nationalization, then potential success does not really matter. A nationalized firm is going to lose it all, or see its assets tied up in international courts for years.
TER: Which countries in South America are safe?
JW: I am not too keen to invest in Argentina, even though there are Canada-listed TSX juniors producing oil there and at this point it is safe. I am nervous about the long-term political security of Argentina. But in Colombia, on the other hand, the trend is toward stability. Several companies doing business in Colombia are producing and exporting oil without incident. PetroAmerica Oil Corp. (PTA:TSX) is having great success. And Peru, Chile and, to a lesser extent, Brazil are very safe. Ecuador and Venezuela are at the opposite end of that spectrum. Those two countries are no-go zones.
TER: What type of challenge does a junior explorer need to overcome in a politically safe but geographically extreme region like the Yukon?
JW: Typically, the challenge for juniors in the far north is freezing temperatures, especially north of the Arctic Circle. But in the southwestern Yukon where, for example, companies like EFLO Energy Inc. (EFLO:OTCQB) operate, the weather is not so frigid. The challenge there is the snow pack. There are places where you cannot go with heavy equipment until the land is frozen over. That is the case in other Canadian regions, too. But those types of challenges to oil and gas exploration are not insurmountable. The oil sands in northwestern Alberta and northeastern British Columbia are a testament to that. Regardless of the challenges posed by extreme weather, the oils sands support one of the largest oil and gas production infrastructures to be found anywhere.
TER: Do drillers in difficult geographical locations tend to rely on service companies more heavily?
JW: Generally, the service companies are deployed at the same ratio. Local service companies have expertise relevant to the local weather patterns and the associated terrestrial challenges. So companies gravitate toward local firms for early-stage geophysics, but then when it comes to drilling deep, expensive wells, they gravitate toward the multinationals—companies like Baker Hughes Inc. (BHI:NYSE), Schlumberger Ltd. (SLB:NYSE), etc.
TER: You mentioned EFLO Energy. Could you give us a profile on that name?
JW: EFLO Energy has an interest in the Kotaneelee gas field in the Yukon, which is where Apache Corp. (APA:NYSE) recently announced a discovery hole with astounding flow rates. The potential size of the reservoir is over 30 billion cubic feet. It is proximal to where Apache is working on a very large land position with gas processing infrastructure. EFLO is well situated to take advantage of working one of the largest, but as yet undeveloped, gas fields in the world: the Kotaneelee.
TER: What is the situation with the share price of EFLO Energy?
JW: EFLO has held up well—between $1.40 and $2.60 during the last year. It’s at $1.50 right now, but that is a reflection of the fact that it has not been drilling much of late. The company is currently focused on building its executive team. Once it starts to drill and develop the oil and gas field, its share price will most likely improve. If it makes a decent-size discovery, it will be a very attractive takeout candidate for a foreign national oil company. China’s national oil companies are showing great interest in Canadian companies with large gas reserves.
TER: What about the Peace River Arch region? How does that differ from the Yukon in terms of geographical challenges?
JW: The Peace River Arch is a very mature, sedimentary basin. The geographical challenge is to find any available land left to prospect. The Alberta government has done such a good job of maintaining a database of all of the different pay zones that anybody can go online and effectively prospect for property. Where there is some success, the prices are driven up very quickly because the market instantly reflects demand. So it’s very tough to get positions in the Peace River Arch region. There are great barriers to entry for new companies that want to get in, but there are a handful of juniors that are developing production nicely.
TER: Such as?
JW: Aroway Energy Inc. (ARW:TSX.V; ARWJF:OTCQX) is a very successful company that I have followed since 2011. Unfortunately, it is currently suffering from the deflationary effect, which afflicts the entire TSX Venture Exchange (TSX.V). Due to the generally poor performance of mining stocks, its share price halved during the last year. That trend does not look as if it is going to change soon. On the other hand, the TSX.V has been beaten up so badly that there are fantastic bargains available. Aroway is an excellent case in point. The company is producing over 1 Mbbl/d, and it has a great land position. Its share price does not reflect the actual value of the company, and Aroway has substantial cash flow and is growing production on an almost daily basis.
TER: What services companies operate in that region?
JW: There is Enterprise Group Inc. (E:TSX.V), which I started following in 2006. The company recently announced several acquisitions. It has acquired a specialized engineering firm, an underground infrastructure construction company that is generating $12 million ($12M) per year in revenue. The acquisition will give Enterprise 40% of its earnings before income tax, depreciation and amortization (EBITDA) in 2013. Enterprise’s business model is to consolidate the oil field services industry in Western Canada. The plan is starting to pay off.
TER: From the investor point of view, what is the best type of corporate structure for a service firm—vertical or horizontal?
JW: Enterprise is integrating horizontally. It is in a position to capitalize on new trends in geophysics. It is able to offer everything to everyone. Companies that are more specialized tend to be boom-and-bust. When things are particularly good in their particular sector, then let the good times roll. But when the public appetite goes in a different direction, then those companies can flounder for years. Enterprise Group is acquiring companies across various subsectors in the oil field services and, thereby, insulating itself against future soft spots in the market.
TER: How is the Enterprise stock price doing?
JW: It is in the $0.70 range. The company has touched a 52-week high about 10 times this year. It has delivered a multiple of 7x. In July a year ago, it was trading at less than $0.20. Now, it’s trading up near $0.70, and it is poised to go higher.
TER: You mentioned that Alberta has an online prospecting database. Do other jurisdictions in North America maintain similar databases?
JW: Alberta has always led the oil and gas jurisdictions in preserving data and allowing access to it. That is really smart because it creates maximum demand for a potential hydrocarbon asset. The province’s tax base benefits every single Albertan. In contrast, look at Texas, which was ground zero for the development of the oil industry. The rights to oil and gas assets in Texas are controlled by a politicized railroad commission, which is more focused on real estate issues than developing energy assets. In Texas, it is almost impossible to figure out who owns what! If you are looking to acquire legacy data from previous hydrocarbon explorations on certain properties, it is like detective work. You have to chase information backward through courts and property deeds. That makes it almost impossible for a newcomer in Texas to buy properties without acquiring very specialized local expertise. At the end of the day, Texas is just not efficiently maximizing its hydrocarbon wealth on behalf of its tax base. That is not by design, it’s just the way the system evolved there.
TER: What about other high-profile drilling jurisdictions, like North Dakota, Wyoming and Nevada?
JW: Each of those jurisdictions is regulated by the by the Bureau of Land Management (BLM). But the Bakken in North Dakota is now rather mature. With the declining price of natural gas and the increasing costs of exploration, there are fewer and fewer entrants knocking on the door. Geographically, there are few incumbents, and they are able to operate and finance continued exploration from production cash flows. The grassroots junior boom in land purchases that was characteristic of 2007-2008 is largely over now because the basins are better defined.
TER: So what is a junior company without land to do? Go abroad?
JW: For a junior company on the TSX.V, that’s a good question. I know of a couple of companies that are electing to go abroad. One of them that we hold in The Midas Letter Opportunity Fund is Rift Basin Resources Corp. (RIF:TSX.V). Its projects in Tunisia are advancing in partnership with another British oil and gas company. It is exploring further in Tunisia and also planning exploration in Gabon. It is assessing an opportunity in Indonesia that could be huge. And, remember, I do not categorically dismiss Argentina—Americas Petrogas Inc. (BOE:TSX.V) is successfully drilling unconventional shale oil and gas wells there. The stock is down to $0.85 from a high in the last year of almost $3. But, again, that’s largely a reflection of the ailing TSX.V.
TER: Are there junior opportunities in Brazil?
JW: It is very hard for explorers to compete with the national oil company, Petrobras (PBR:NYSE; PETR3:BOVESPA), which is majority owned by the government of Brazil. The country is really biased toward its own. Brazil is famous for that. Only rarely do outside companies acquire major Brazilian corporations. It is a type of covert resource nationalism, practiced not as a matter of public policy, but as a tacit demonstration of nationalistic attitude.
That said, my biggest winner of 2012 operates in Brazil. Abakan Inc. (ABKI:OTCQB) is building a four-line pipe cladding facility there. It will sell pipe to Petrobras. In fact, it has a joint development agreement with Petrobras, which holds a large percentage of its offshore wells at extremely high pressures. Petrobras pumps high-end hydrogen sulfide, which is extremely corrosive. Therefore, to produce the hydrocarbons economically, Petrobras needs to keep improving its gathering and transmission infrastructure. Abakan is really integral to Petrobras’ future going forward, and that is why Petrobras and the government of Brazil are assisting Abakan in acquiring the land and financing to build the pipe manufacturing plant. Abakan’s stock price has tripled in the last two years. It is waiting for a full NASDAQ listing. After Brazil, it plans to build an eight-line plant in Indonesia. Currently, its one plant throws off $60M annually in gross revenue, of which 40% is gross margin. It is a great cash maker, and there are a lot of projects in Indonesia and Brazil that will not move forward until the Abakan technologies can be deployed in the field.
TER: Are there any other geographical regions or undervalued exploration or service-oriented companies flying under the radar?
JW: Given the state of equity markets in general in the resource sector, a lot of investors are looking for yield. Our fund is no different. We are planning to invest in Argent Energy Trust (AET.UN:TSX), which is a Toronto-listed company that acquires producing oil and gas assets and distributes their revenue, minus the cost of administration, to the yield holders. Basically, it is averaging 10% annually in yield, and the unit holders are also exposed to a rising share price as the value of the portfolio increases and the company deploys capital to acquire more producers. For an energy-focused yield play, I cannot think of a better one than Argent Energy Trust.
TER: How does Argent manage to do that? Does it pick companies that are doing particularly well, or is it distributing risk over a bell curve?
JW: The key to Argent Energy Trust’s strategy is that it exploits foreign asset regulations. It is classified as a foreign asset investment trust. It distributes the income from foreign-producing hydrocarbon assets on a tax-optimized basis to unit holders. Brian Prokop, who is the co-CEO and president, was formerly with Daylight Energy Ltd. He has experience in building and producing oil and gas assets. He’s the perfect man in the perfect job! In terms of the tax benefits, approximately 60% return on capital is realized. The U.S. corporate tax on it is under 2%. It is a great way to play for yield in the energy sector.
TER: Any other comers?
JW: Surge Energy Inc. (SGY:TSX) bears watching. It was recently the subject of a bought-deal financing for $300M. It is moving more toward becoming a dividend-paying oil and gas company. That suggests great potential for the share price, as well as for the yield that the company will pay out. If it uses its treasury to acquire producing assets and distributes the proceeds to shareholders, that is far more attractive to me in the near term than a company that is raising capital to look for oil and gas assets when the return on that capital will be much lower.
TER: Thank for your time today, James.
JW: My pleasure, Peter.
James West is publisher and editor of The Midas Letter, an independent capital markets entrepreneur and investor. He has spent more than 20 years working as a corporate finance advisor, corporate development officer, investor relations officer, media relations and business development officer for companies involved in mining, oil and gas, alternative fuels, healthcare, Internet technology, transportation, manufacturing and housing construction.
Want to read more Energy Report interviews like this? Sign up for our free e-newsletter, and you’ll learn when new articles have been published. To see a list of recent interviews with industry analysts and commentators, visit our Streetwise Interviews page.
DISCLOSURE:
1) Peter Byrne conducted this interview for The Energy Report and provides services to The Energy Report as an independent contractor. He or his family own shares of the following companies mentioned in this interview: none.
2) The following companies mentioned in the interview are sponsors of The Energy Report: Aroway Energy Inc and EFLO Energy Inc. Streetwise Reports does not accept stock in exchange for its services or as sponsorship payment.
3) James West: I or my family own shares of the following companies mentioned in this interview: All. I personally am or my family is paid by the following companies mentioned in this interview: None. My company has a financial relationship with the following companies mentioned in this interview: None. I was not paid by Streetwise Reports for participating in this interview. Comments and opinions expressed are my own comments and opinions. I had the opportunity to review the interview for accuracy as of the date of the interview and am responsible for the content of the interview.
4) Interviews are edited for clarity. Streetwise Reports does not make editorial comments or change experts’ statements without their consent.
5) The interview does not constitute investment advice. Each reader is encouraged to consult with his or her individual financial professional and any action a reader takes as a result of information presented here is his or her own responsibility. By opening this page, each reader accepts and agrees to Streetwise Reports’ terms of use and full legal disclaimer.
6) From time to time, Streetwise Reports LLC and its directors, officers, employees or members of their families, as well as persons interviewed for articles and interviews on the site, may have a long or short position in securities mentioned and may make purchases and/or sales of those securities in the open market or otherwise.
Streetwise – The Energy Report is Copyright © 2013 by Streetwise Reports LLC. All rights are reserved. Streetwise Reports LLC hereby grants an unrestricted license to use or disseminate this copyrighted material (i) only in whole (and always including this disclaimer), but (ii) never in part.
Streetwise Reports LLC does not guarantee the accuracy or thoroughness of the information reported.
Streetwise Reports LLC receives a fee from companies that are listed on the home page in the In This Issue section. Their sponsor pages may be considered advertising for the purposes of 18 U.S.C. 1734.
Participating companies provide the logos used in The Energy Report. These logos are trademarks and are the property of the individual companies.
101 Second St., Suite 110
Petaluma, CA 94952
The Conversation (0)
Latest News
Outlook Reports world
Featured Energy Investing Stocks

Investor Insight
Coelacanth Energy is a pure-play Montney oil and natural gas company advancing one of the largest contiguous land positions in the Montney light oil window of northeastern British Columbia. Supported by a substantial discovered and undiscovered hydrocarbon resource base, growing production, established infrastructure and a management team that has built and sold six successful energy companies, Coelacanth is executing a strategy focused on increasing both near-term cash flow and long-term resource value.
Overview
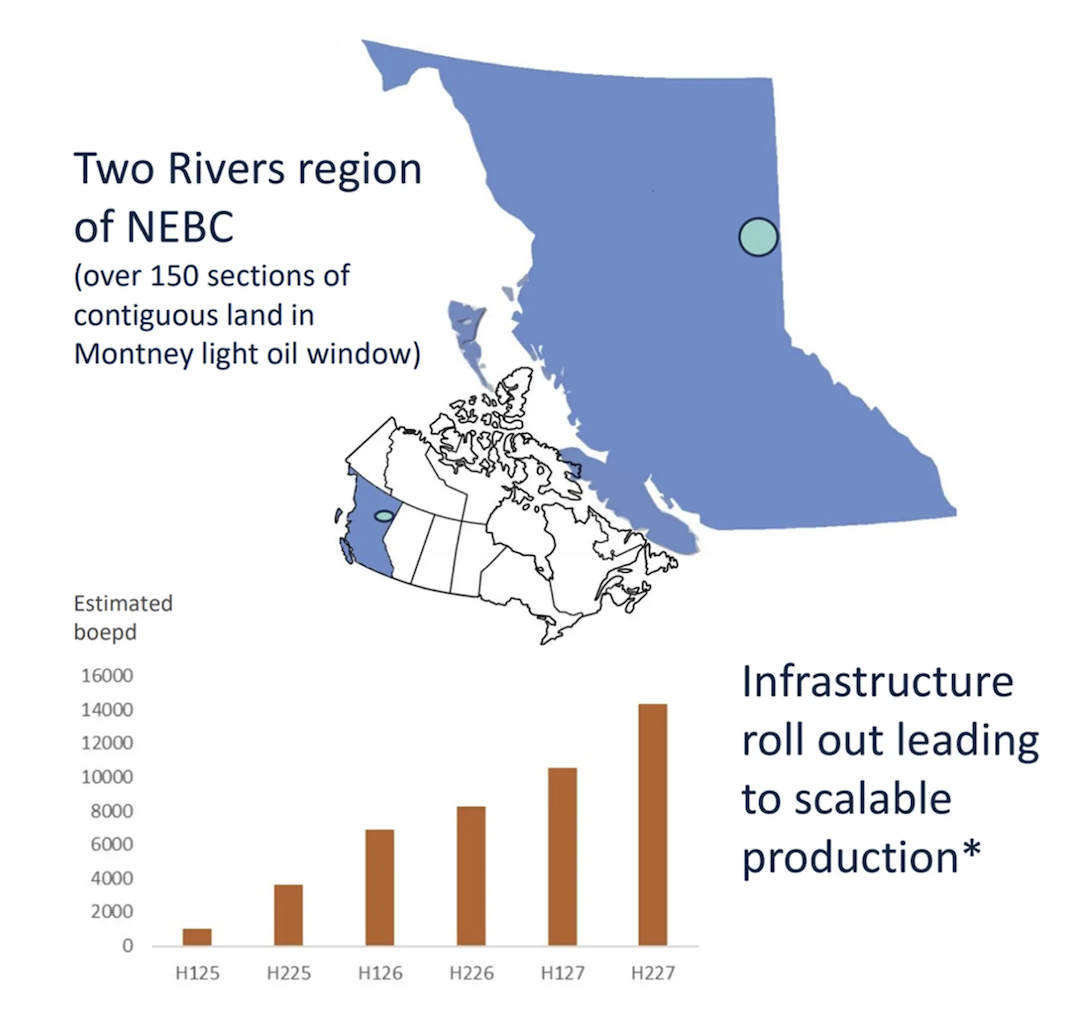
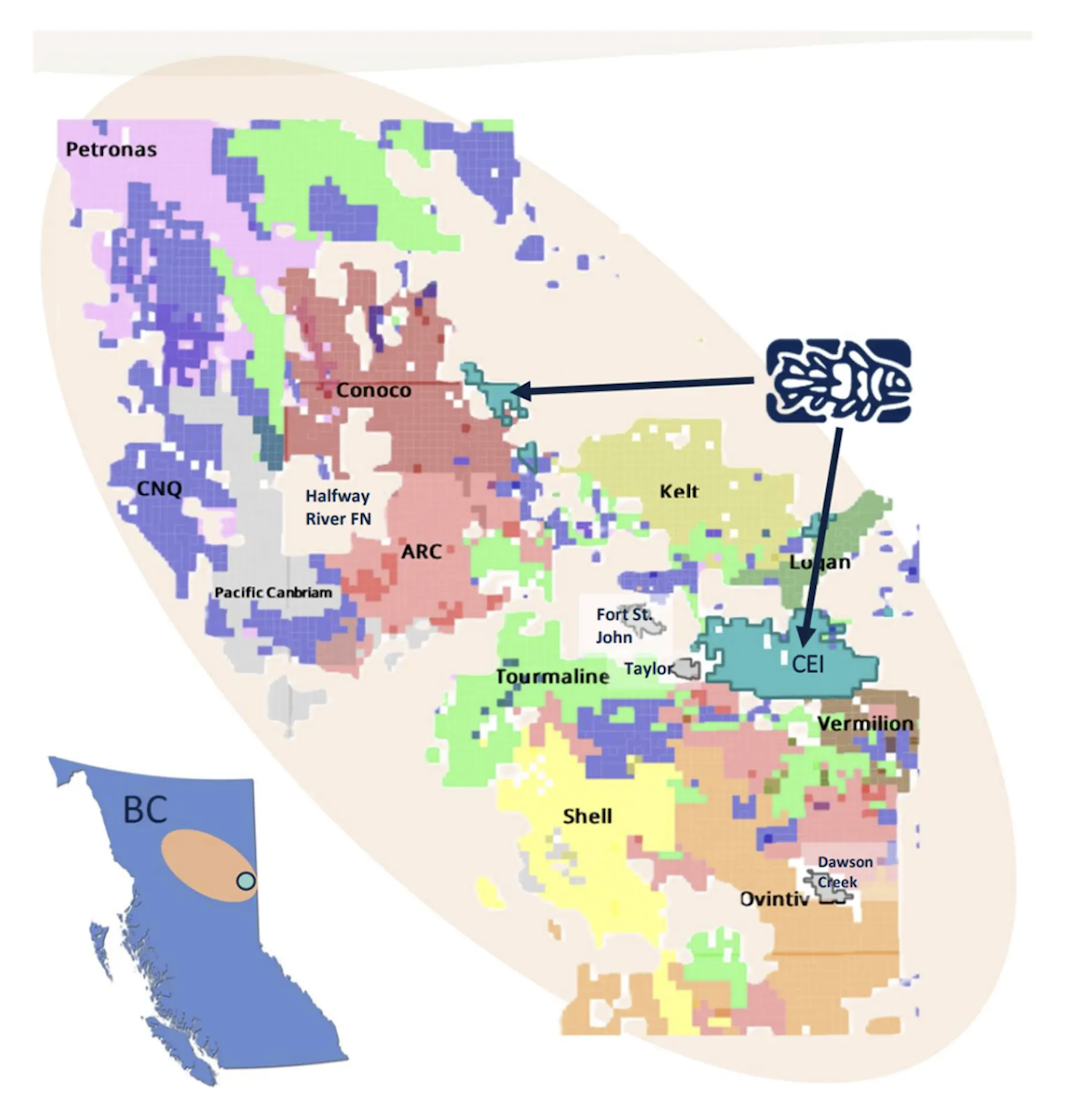
Coelacanth Energy (TSXV:CEI) is a Canadian oil and natural gas exploration and development company focused on the Montney Formation in northeastern British Columbia. The company controls over 150 contiguous sections in the Two Rivers region, a strategically positioned acreage block within the Montney light oil window. As one of the largest landholders in this highly prospective area, Coelacanth has assembled a large-scale resource platform with significant development potential.
The company’s asset base is supported by substantial petroleum initially-in-place estimates prepared by GLJ. These include 6.9 billion barrels of discovered oil PIIP and 8.3 billion barrels of undiscovered oil PIIP, alongside 5.9 Tcf of discovered gas PIIP and 7.1 Tcf of undiscovered gas PIIP. The resource spans multiple Montney intervals, including the Upper, Lower, Basal and Middle Montney, providing extensive opportunities for future development and delineation.
Coelacanth’s strategy combines near-term production growth with long-term resource value creation. The company has secured critical infrastructure, contracted gas takeaway and processing capacity, and advanced development activities across its Two Rivers assets. Average production reached 7,632 boe/d in Q2 2026, reflecting continued progress in transitioning from delineation and infrastructure buildout toward scalable production growth.
A key differentiator for Coelacanth is its leadership team. Management has successfully built and sold six previous public energy companies and has demonstrated an ability to create value through multiple commodity cycles. Supported by deep operational, geological and financial expertise, the team is focused on disciplined execution of the company’s Montney growth strategy.
Company Highlights
- Premier Montney land position: Controls over 150 contiguous sections in the Two Rivers region of northeastern British Columbia, making Coelacanth the largest landholder in the Montney light oil window.
- Substantial hydrocarbons in place: GLJ estimates 6.9 billion barrels of discovered oil PIIP, 8.3 billion barrels of undiscovered oil PIIP, 5.9 Tcf of discovered gas PIIP, and 7.1 Tcf of undiscovered gas PIIP across the company’s Montney acreage.
- Infrastructure-led growth strategy: Key infrastructure, including facilities, pipelines, processing agreements and gas takeaway capacity, has been secured to support scalable production growth.
- Growing production base: Average production reached 7,632 boe/d in Q2 2026, supported by ongoing development at the Two Rivers project.
- Multiple productive Montney horizons: The asset base includes the Upper, Lower, Basal and Middle Montney intervals, providing extensive development opportunities across multiple zones.
- Strong market access: Secured 100 mmcf/d of gas takeaway capacity and up to 60 mmcf/d of processing capacity, with access to major pipeline networks and potential LNG Canada connectivity through Coastal GasLink.
- Proven value-creation team: Management has built and sold six successful energy companies and brings extensive operational, technical and financial expertise to Coelacanth’s development strategy.
Key Project
Two Rivers Montney Development
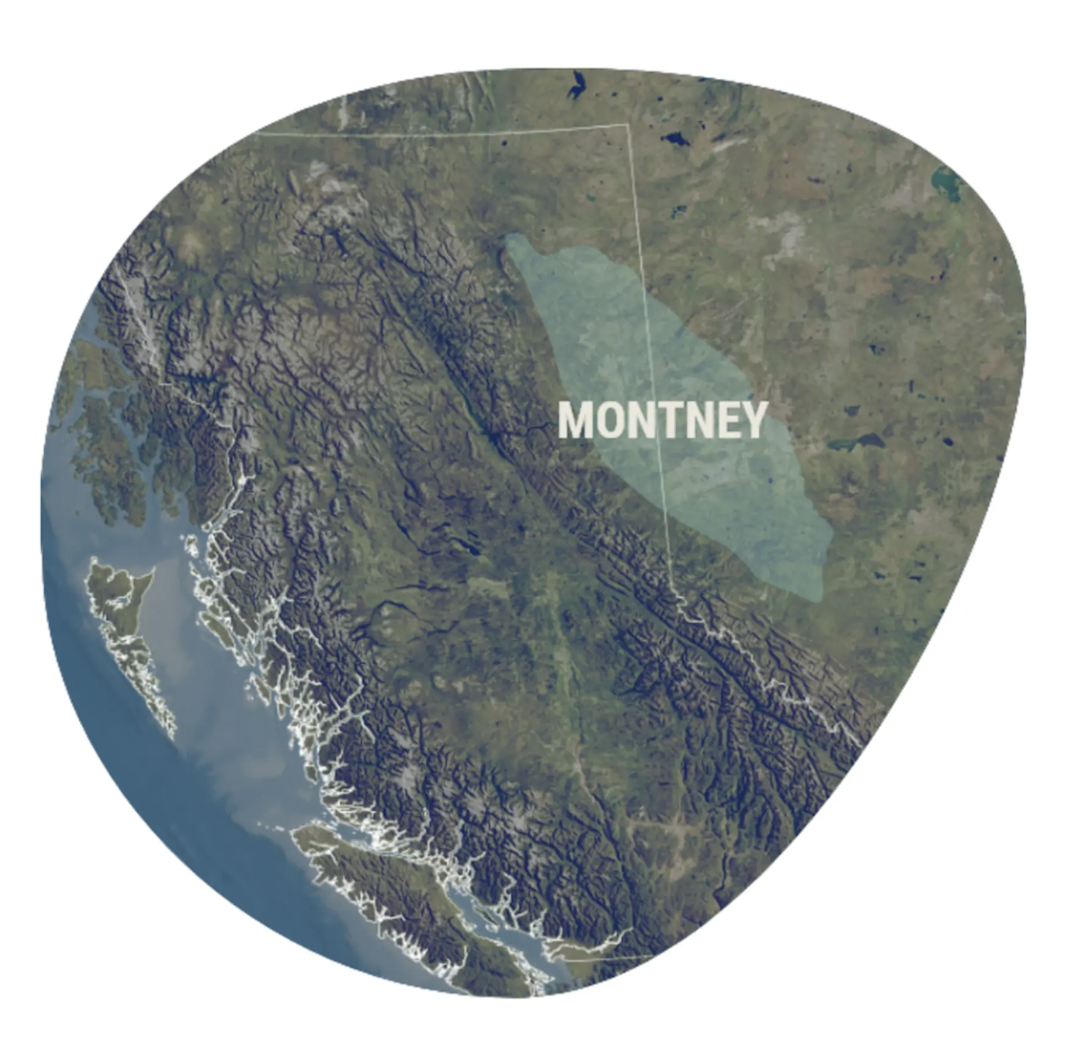
The Two Rivers project forms the cornerstone of Coelacanth’s growth strategy and encompasses the company’s extensive Montney land position in northeastern British Columbia. The project hosts multiple productive horizons, including the Upper, Lower, Basal and Middle Montney intervals, supporting a multi-zone development approach across the acreage. Geological delineation has been completed, providing a strong technical foundation for future drilling and development.
The project has demonstrated commercial productivity through successful drilling and testing programs. Coelacanth established proof of commerciality at both Two Rivers East and Two Rivers West, while development at the 5-19 and 10-08 pads confirmed productivity across multiple Montney benches. All 12 wells on the 5-19 pad were onstream by April 1, 2026, marking a significant milestone in the project’s progression.
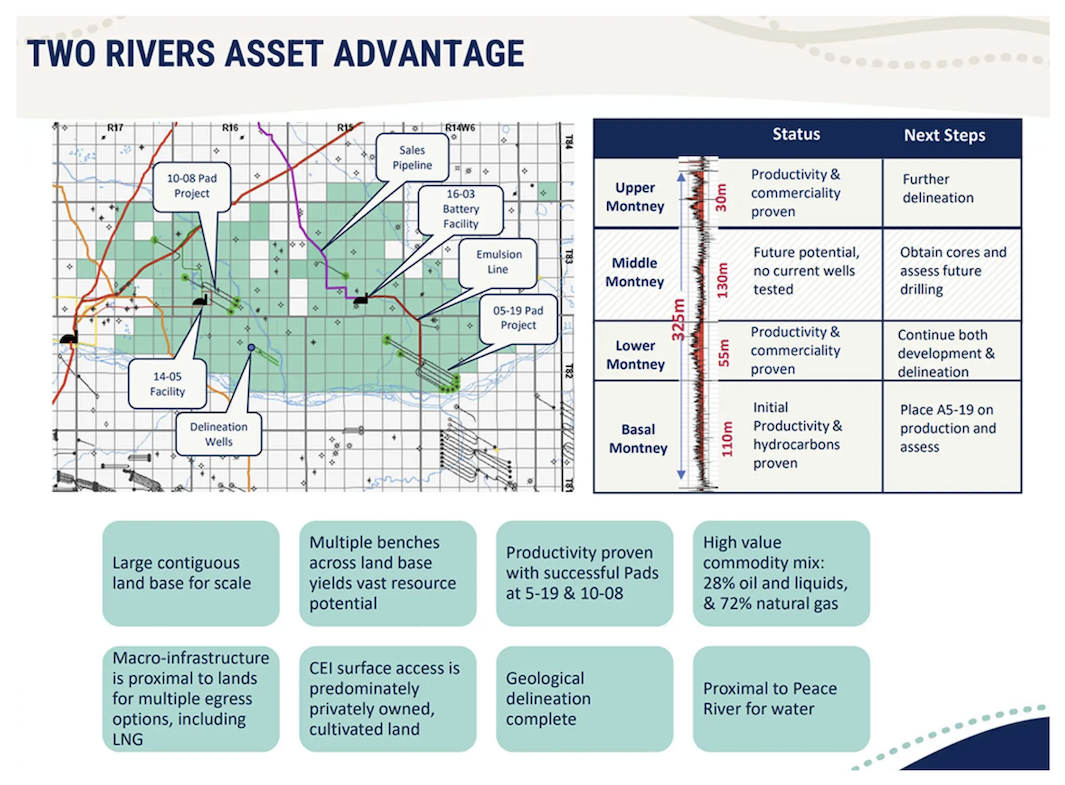
Infrastructure development has been a major focus of the company’s execution strategy. Coelacanth has secured infrastructure financing, completed key facility and pipeline construction, contracted up to 100 mmcf/d of gas takeaway capacity and secured processing capacity of up to 60 mmcf/d. These initiatives establish the infrastructure foundation required to support future production growth.
The Two Rivers asset also benefits from strong market access. The company’s production can access major regional pipeline systems, including NGTL, Westcoast and Alliance, while its acreage is directly connected to LNG Canada through the Coastal GasLink system for potential future delivery. Coelacanth Energy said the long-term view for LNG expansion in British Columbia is very positive for its land, believing that lands with scale and direct access as such will trade at a premium once they are delineated and the resource is proven for development.
Combined with a commodity mix of approximately 31 percent oil and liquids and 72 percent natural gas, the project offers exposure to multiple energy markets.
Management Team
Rob Zakresky – President, CEO and Director
Rob Zakresky is a veteran energy executive who previously served as president and CEO of Leucrotta Exploration, Crocotta Energy, Chamaelo Exploration, Chamaelo Energy, Viracocha Energy and Bellator Exploration. He has a proven track record of building and monetizing public energy companies and leads Coelacanth’s strategic growth and value creation initiatives.
Nolan Chicoine – Vice President of Finance and CFO
Nolan Chicoine previously served as CFO and vice-president finance at Leucrotta Exploration, Crocotta Energy and Chamaelo Exploration, and was controller at Chamaelo Energy and Viracocha Energy. He is responsible for financial strategy, reporting and capital management.
Jody Denis – Vice President of Operations
Jody Denis is a former drilling, engineering and operations engineer at Leucrotta Exploration. His previous experience also includes senior operational and drilling leadership roles with Black Swan Energy, ARC Resources and Birchcliff Energy. He formerly led Coelacanth Energy’s drilling and completions activities.
John Fur – Vice President of Geosciences
John Fur previously served as manager of exploration at Leucrotta Exploration and held senior geophysical positions with Crocotta Energy, Chamaelo Energy, Viracocha Energy, Canadian Natural Resources, Post Energy, Amber Energy and Husky Oil. He oversees geological evaluation and resource delineation across the company’s Montney assets.
Jonathon Hanson — Vice President of Engineering
Jonathon Hanson has 20 years of industry experience. He previously served as manager for exploitation at Spartan Dela Corp, and was a senior exploitation engineer for companies Vermilion Energy, Lynx Energy and Saguaro Resources. He will focus on exploitation and reservoir management for Coelacanth Energy.
Investor Insight
Syntholene Energy is advancing a proprietary synthetic fuel production platform designed to produce high-performance, low-cost synthetic hydrocarbons using renewable electricity, geothermal heat and captured carbon. Following successful prototype-scale validation in 2022, the company is now operating its Iceland demonstration facility as it plans commercial-scale production capable of serving aviation, transportation, industrial energy and other hard-to-abate fuel markets.
Overview
Syntholene Energy ((TSXV:ESAF,FSE:3DD0, OTC:SYNTF) is a synthetic fuel production company company focused on developing high-performance, low-cost synthetic liquid fuels. The company is commercializing its proprietary Hybrid Thermal Production System, which combines renewable electricity, geothermal heat, water and captured carbon to produce synthetic hydrocarbons that can serve as direct replacements for conventional petroleum-derived fuels.
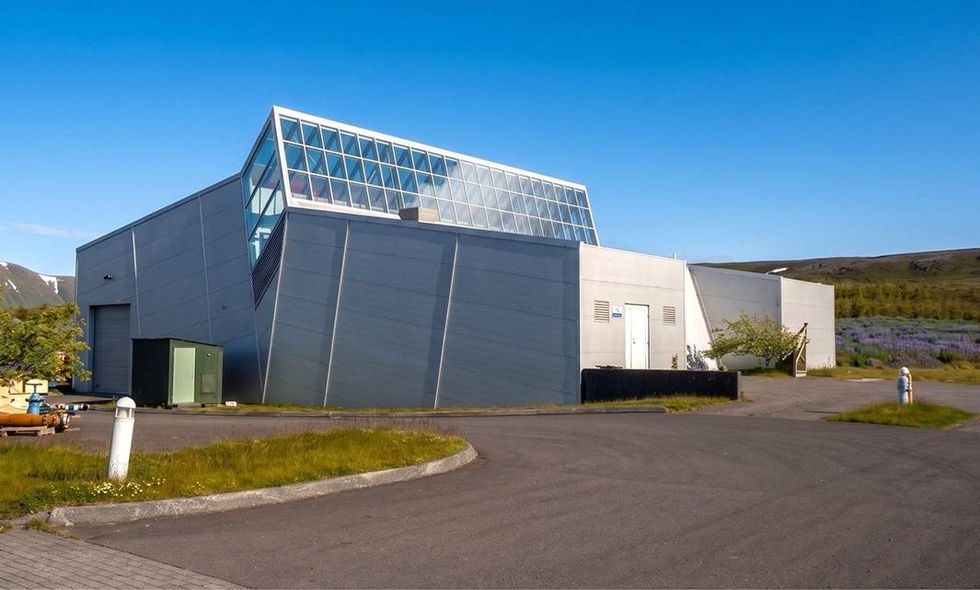
Unlike many alternative energy solutions that require extensive changes to existing infrastructure, synthetic fuels can be transported, stored and utilized through today’s fuel supply chains. The resulting fuels are molecularly pure, free from many contaminants associated with conventional fuels and compatible with existing engines, turbines, storage systems and transportation infrastructure. Produced using renewable electricity, hydrogen and captured carbon, the fuels can deliver over 90 percent lower lifecycle emissions while maintaining the energy density and performance characteristics required across multiple industries.
At the core of the company’s platform is its Hybrid Thermal Production System, which combines high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors. By incorporating low-cost thermal energy into critical production stages, Syntholene seeks to reduce electricity consumption, the largest cost component for most eFuel producers. This approach underpins the company’s targeted 70 percent cost advantage relative to competing technologies and supports its objective of producing cost-competitive synthetic fuels at commercial scale.
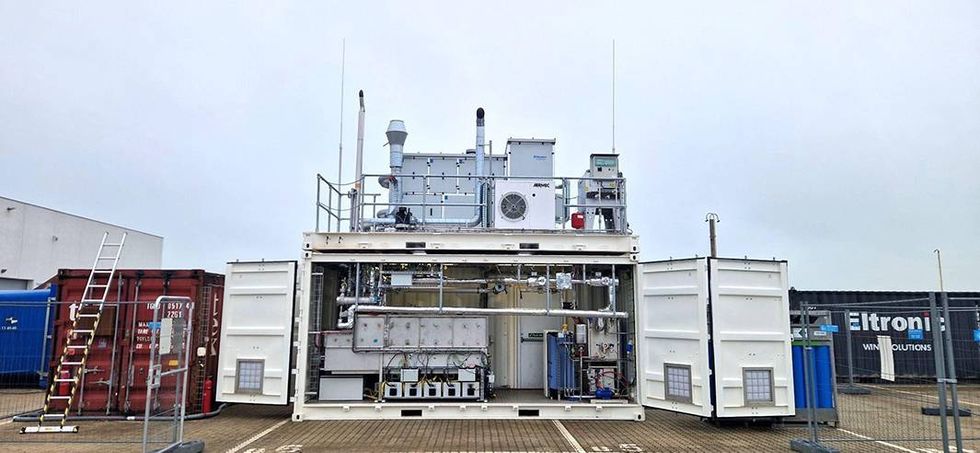
The technology builds upon advancements in high-temperature electrolysis, including work undertaken at Idaho National Laboratory. Following successful prototype-scale validation in 2022, Syntholene is progressing toward field-scale demonstration in Iceland. The company believes a successful demonstration will support future commercial deployment across a range of synthetic fuel applications.
Market demand for low-emission liquid fuels continues to expand across multiple sectors. Sustainable aviation fuel represents Syntholene’s initial commercial focus, supported by increasing airline decarbonization commitments, regulatory mandates, and fuel-blending requirements. Beyond aviation, the broader global eFuel market is projected to grow from US$8.89 billion in 2024 to more than US$215 billion by 2032, creating opportunities across transportation, shipping, industrial energy, and other sectors that depend on liquid hydrocarbon fuels.
Syntholene’s leadership team combines expertise across climate technology, synthetic fuels, industrial engineering, energy infrastructure, project development and resource industries. Recent additions to the advisory board, including former Shell and Suncor executive Marc Mageau and energy industry veteran HY Lee, further strengthen the company’s capabilities as it advances toward commercialization.
Company Highlights
- Addressing a multi-layered growth opportunity: The company is initially targeting sustainable aviation fuel while developing a technology platform capable of serving a substantially larger global liquid fuels market spanning transportation, industrial energy and other hard-to-electrify sectors.
- Proprietary hybrid thermal production system: Syntholene’s technology integrates high-temperature solid oxide electrolysis with industrially proven fuel synthesis reactors, utilizing both electricity and thermal energy to improve efficiency and reduce production costs.
- Targeting a 70 percent cost advantage: By introducing low-cost thermal energy into critical stages of production, the company aims to produce synthetic fuels at 70 percent lower cost than competing eFuel technologies.
- Pathway to cost-competitive synthetic fuels: The company believes its technology provides a credible pathway toward producing synthetic fuels that can compete economically with conventional petroleum-derived fuels at scale.
- High-performance fuel characteristics: Synthetic fuels are molecularly pure and free from many contaminants associated with conventional fuels, including sulfur, nitrogen and heavy metals, while remaining compatible with existing infrastructure.
- Over 90 percent lower lifecycle emissions: Synthetic fuels produced from renewable electricity, hydrogen and captured carbon can deliver over 90 percent lower lifecycle emissions than conventional alternatives.
- Prototype validation completed: The company’s production process was successfully demonstrated at prototype scale in 2022 and is now operating a world-first geothermally-integrated demonstration facility in Husavik, Iceland.
- Demonstration facility advancing ahead of schedule: The Húsavík, Iceland facility is now operating, with efficiency and technoeconomic results expected in Q4 2026.
- Strategic geothermal platform: The Iceland project benefits from low-cost geothermal electricity, thermal energy, industrial infrastructure, deep-water port access and an existing 200 MW+ regional grid expansion permitting framework.
- Scalable commercial development strategy: Following demonstration, the company intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts.
Flagship Project
Húsavík Demonstration Facility, Iceland
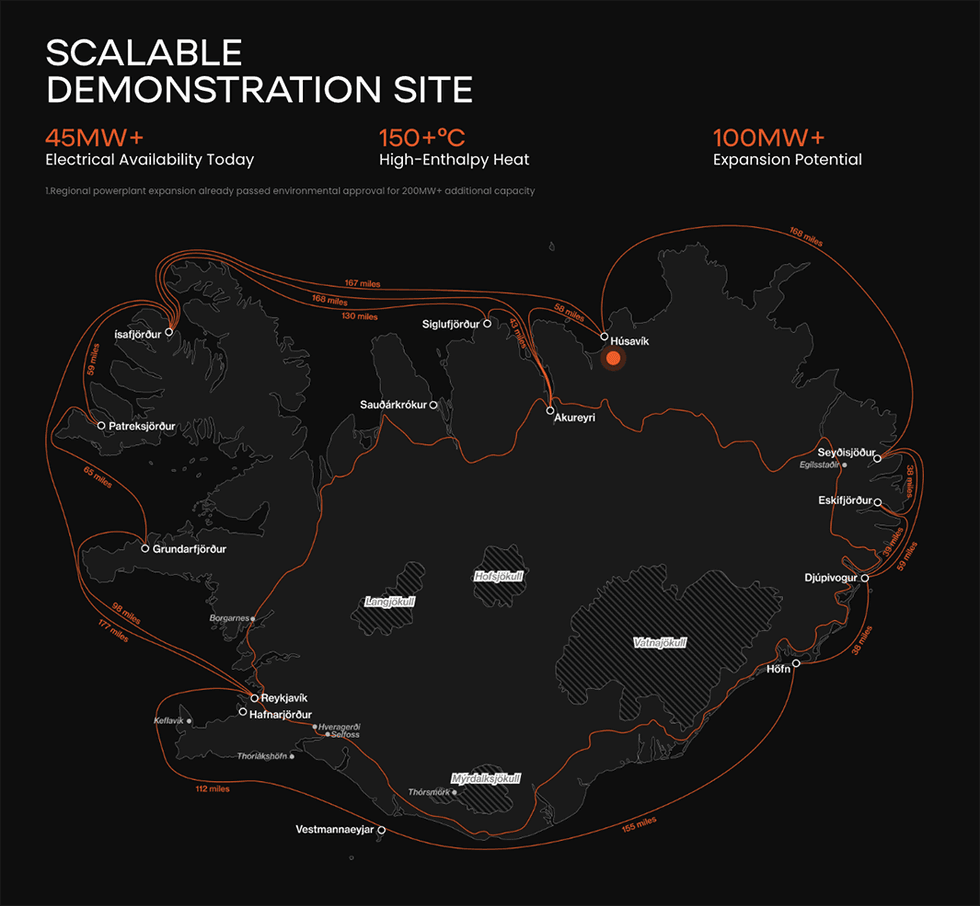
Syntholene’s flagship project is its geothermal-integrated demonstration facility located in Húsavík, northern Iceland. The facility is designed to validate the integration of geothermal heat, high-temperature solid oxide electrolysis and synthetic fuel production technologies under real-world operating conditions. Construction has advanced six months ahead of schedule, with first operations initiated on June 22nd 20266 and efficiency and technoeconomic results expected in Q4 2026.
The project leverages northern Iceland’s abundant geothermal resources, providing access to both low-cost electricity and high-temperature steam. Unlike intermittent renewable energy sources, geothermal energy offers reliable baseload power and thermal energy that can be utilized continuously throughout the fuel production process. The location also benefits from established industrial infrastructure, a skilled workforce, proximity to a deep-water port and a favorable regulatory environment.
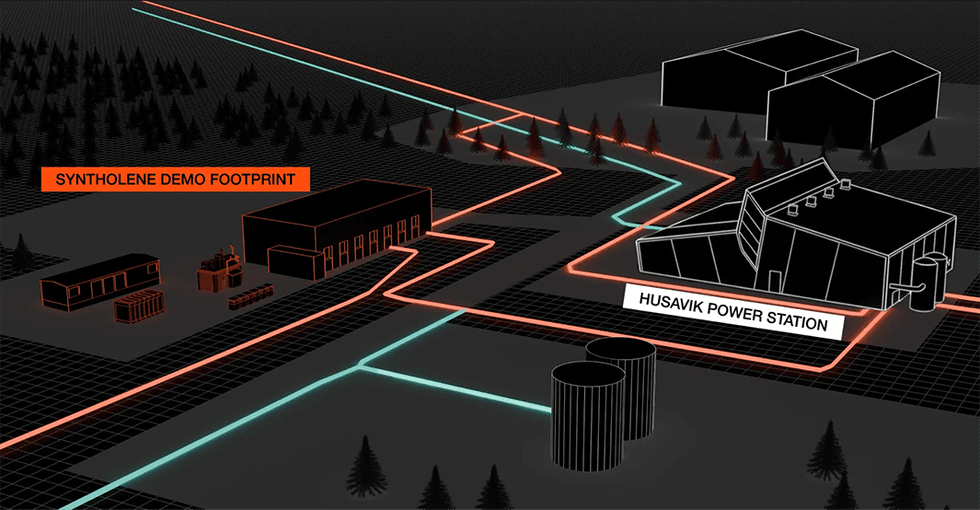
A key objective of the demonstration facility is to validate the company’s thermal integration strategy and confirm that efficiencies achieved during laboratory and prototype testing can be replicated under commercial operating conditions. The facility incorporates Syntholene’s proprietary Thermal Coupling technology, which converts geothermal steam into high-purity industrial steam suitable for use throughout the fuel production process. Management believes this technology is central to achieving the targeted 70 percent cost advantage relative to competing synthetic fuel pathways.
The project also benefits from significant expansion potential. Iceland has completed environmental permitting associated with a 200 MW regional grid expansion, supporting future industrial development in the region. Following a successful demonstration, Syntholene intends to advance a 20,000-tonne-per-year commercial facility design and subsequently scale production through facilities ranging from tens to hundreds of megawatts. Management believes the Húsavík location alone has the potential to support development capable of generating approximately US$500 million in annual revenue.
Management Team
Dan Sutton – Chief Executive Officer
Dan Sutton has spent the last 15 years founding and leading sustainable infrastructure businesses. As founder and CEO of Tantalus Labs, he designed, built and operated SUNLAB, scaled the company to 150 employees and grew annual revenue to approximately US$20 million. His expertise spans infrastructure deployment, project development, government relations, public markets and executive leadership.
Steve Oldham – Director
Steve Oldham is a globally recognized leader in carbon management and climate technology commercialization. As former CEO of Carbon Engineering, he helped establish direct air capture as a commercial industry and led the company through its acquisition by Occidental Petroleum at a US$1.6 billion valuation. He currently serves as CEO of Captura.
Canon Bryan – Director
Canon Bryan is a founder and company builder with more than 25 years of experience across advanced energy and resource development. He co-founded Terrestrial Energy, Uranium Energy and NioCorp and brings expertise in finance, corporate development, economic modelling and strategic planning.
John Kutsch – Chief Engineer
John Kutsch leads the integration and optimization of Syntholene’s fuel production platform. He brings more than 30 years of experience across industrial systems design, chemical processing, advanced energy technologies and reactor development, including work supporting high-temperature synthetic fuel systems.
Jack Williams – Head Engineer
Jack Williams specializes in high-temperature and high-pressure reactor systems and synthetic fuel technologies. His research at the University of Cambridge focused on electrolysis systems, catalytic reactor design, CO₂ capture and synthetic fuel production processes.
Grant Tanaka – Chief Financial Officer
Grant Tanaka has more than 15 years of senior financial leadership experience across the global natural resources sector. His background includes senior finance roles at Teck Resources, New Gold and Copper Mountain Mining, combining financial discipline with operational performance management. He was also appointed Corporate Secretary in May 2026.
Anna Pagliaro – Director
Anna Pagliaro is a senior commercial and risk management executive with extensive experience across the energy and mining sectors. Her career includes leadership positions at Vizsla Silver, Ausenco, NexGen Energy and Integra Gold, where she focused on governance, commercial strategy, negotiations and risk management.
Marc Mageau – Advisory Board Member
Marc Mageau joined the Advisory Board in June 2026. He brings more than three decades of operational leadership experience from Shell and Suncor, including expertise in refining, oil sands operations, logistics, infrastructure development and industrial asset management.
HY Lee – Advisory Board Member
HY Lee joined the Advisory Board in May 2026, adding further industrial, operational and strategic expertise as Syntholene advances toward commercial deployment of its synthetic fuel platform.
Browse Companies
MARKETS
COMMODITIES
CURRENCIES